Author: Michael Hobbs

Request a quote

Our blog

Latest news
& events

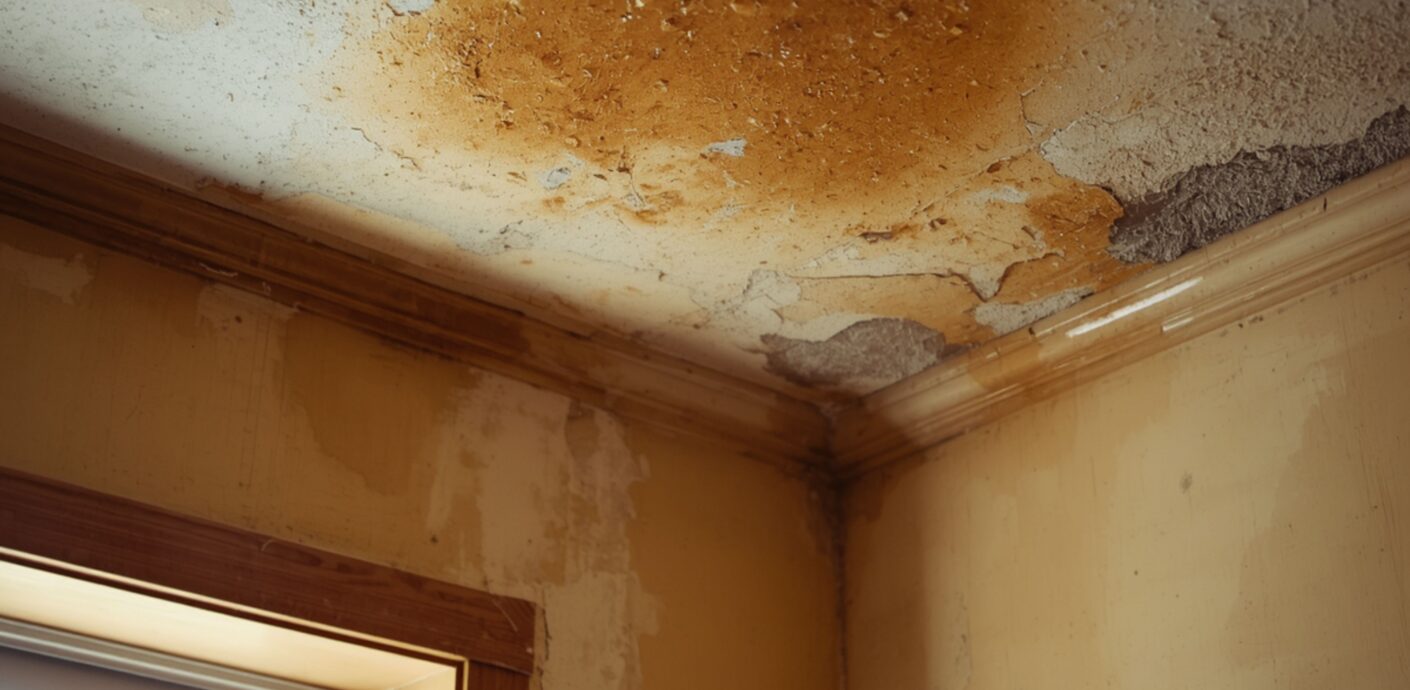
Water damage stains on a ceiling flagged during a home appraisal
Water Damage & Home Value: What Appraisers Flag

Water damage has a way of derailing a sale right when things feel like they are going smoothly. A faint ceiling stain might not worry you at all. An appraiser sees it differently, because that stain often hints at a bigger story. Knowing how water damage and home value connect, and what an appraiser flags before closing, puts you a step ahead. You get to handle problems on your own terms, not at the last minute.

By the end of this article, you’ll know:

  • The water-related conditions an appraiser looks for and writes up
  • Why a lender can stall your closing until water problems get fixed
  • What to repair and document before the appraisal happens
How Water Damage Affects Home Value

Most homeowners assume the hit to value equals the repair bill. It rarely works that cleanly. What worries a buyer, a lender, and an appraiser is what the water might have done out of sight. Water travels. A roof leak can rot the sheathing above a ceiling long before any stain shows up. Down in the basement, dampness might point to a grading or foundation issue. And a slow drip under a sink? That can feed mold behind the drywall for months before anyone notices.

That uncertainty is what moves the numbers. A home with visible water damage tends to draw lower offers, repair demands, or a longer stretch on the market. An appraiser’s job, after all, is to capture how the market reacts to what’s in front of it. So we note the visible conditions and weigh how they affect value and saleability.

What an Appraiser Will Notice

We are not home inspectors, and we do not go cutting into walls. But a trained appraiser spots the visible signs of a water problem fast during a standard residential appraisal. The usual flags:

  • Water stains on ceilings and walls
  • Standing water in a basement, crawlspace, or against the foundation
  • A musty smell that says moisture is still hanging around
  • Warped or swollen drywall, baseboards, and flooring
  • Roof leaks, or shingles that have clearly seen better days
  • Grading that sends rainwater toward the house instead of away from it

A lot of this matters because of what tends to follow water: mold. The EPA points out that mold needs ongoing moisture to grow. So a damp crawlspace, or a stain nobody can explain, earns more scrutiny than its size might suggest.

How Water Damage Can Hold Up Your Closing

Water damage can hold up the calendar, too. Lenders, especially on government-backed loans, hold a property to minimum condition standards.. Active water intrusion is one of the more common reasons an appraisal comes back “subject to repair.”

Once that happens, the lender usually wants it fixed and re-checked before the deal can close. Even a small repair can push your closing date back a week or two. Worse, when it only turns up at the appraisal, that lost time becomes the real cost for anyone working to a firm contract date.

Old Damage Reads Differently From Active Damage

Not every water stain carries the same weight. The question an appraiser really cares about is whether the source got fixed.

Picture a leak you repaired last spring. You replaced the ruined drywall and kept the receipts. In that case the worry mostly evaporates, because you can prove the problem is behind you. Now picture a fresh stain, a corner that’s still damp, and no paperwork. An appraiser has to treat that as a live issue, and so will the buyer.

What to Do Before the Appraiser Shows Up

A few moves keep a water issue from running your whole sale:

      1. Fix the source, first and always. Scrub a stain without stopping the water and it comes right back, usually at the worst possible moment.
      2. Keep the paperwork. Invoices, contractor notes, inspection reports. Good documentation answers the appraiser’s question before anyone asks it.
      3. Repair what shows. Swap out stained drywall, ceiling tiles, and warped trim, so nobody is writing up damage you have already handled.
      4. Speak up early. If the house has had a real water event, tell your agent and your appraiser up front. Then everyone plans around the facts instead of a surprise.
Why It Pays to Get Ahead of It

Water damage does not have to wreck your value or your timeline. Most of the harm to a sale comes from the unknowns, like what’s behind the wall and whether it’s still wet. Clear those up and the whole conversation shifts in your favor.

So track down the source, fix it, write it all down, and patch the visible damage before you list. Do that, and a water stain stays a footnote in your sale rather than the headline at your closing.

Worried water could cost you at the closing table?

Find out where your home really stands before a lender or a buyer raises the question. PahRoo delivers independent, defensible appraisals that give you answers, not guesswork.

Request Your Appraisal

Frequently Asked Questions

Does water damage lower a home’s appraised value?

It can, though not on its own. The effect depends on how bad it is, whether you’ve fixed the source, and how nervous it makes buyers. Often the real drag on value is what the damage hints at, rather than the damage you can see.

What does an appraiser look for when checking for water damage?

Visible clues, mostly: stains, standing water, musty smells, warped materials, signs of a roof leak, and poor drainage. An appraiser reports what’s in plain sight and won’t go digging behind walls or running lab tests.

Will water damage stop a home loan from closing?

It can slow things down. A lender may insist that active water intrusion gets corrected and re-inspected first, particularly on government-backed loans with condition standards to meet.

Do I need to fix water damage before selling?

Usually yes, especially when it’s visible or a buyer needs financing. Sorting it out before you list keeps the negotiation calmer and lowers the odds of a delayed closing.

Is old, repaired water damage still a problem for an appraisal?

Much less of one, as long as you fixed the source and have the records to show it. Repaired and documented damage sits in a very different category from something fresh or unexplained.

Need an Independent Appraisal?

Sometimes water damage, repairs, or condition questions cloud what a home is really worth. In those moments, an independent appraisal gives you a credible, well-supported answer before you negotiate or finance.

PahRoo Appraisal & Consultancy, LLC helps homeowners, attorneys, accountants, bankers, and real estate professionals make confident decisions. Whether you’re preparing to sell, settling an estate, removing PMI, navigating a divorce, or weighing how a property’s condition affects value, our team is ready to help.
The three types of home appraisals: full, exterior-only, and desktop
The 3 Types of Home Appraisals: Full, Exterior, Desktop

Not every home appraisal involves an appraiser walking through your living room. Some are done from the curb. Others happen entirely from a desk, with nobody visiting at all. So if you’re buying, refinancing, or settling a legal matter, knowing the types of home appraisals, and which one applies to you, tells you a lot about what you’re paying for and how much weight the result can carry.

By the end of this article, you’ll know:
  • What separates a full, exterior-only, and desktop appraisal
  • When a lender is likely to order each one
  • Why the familiar form numbers are about to disappear in 2026
What the Three Types of Home Appraisals Actually Mean

The difference comes down to one question: how much of the property does the appraiser actually see? That scope drives everything else, including cost, turnaround, and how confident anyone can be in the final number. Three scopes cover most situations, so let’s take them in order, from the most thorough to the lightest.

The Full Appraisal: Inside and Out

This is the one most people picture. First, the appraiser visits the property, inspects the exterior, and walks the interior room by room. We measure, photograph, note condition and quality, and flag anything that affects value. On the legacy forms, this is the 1004 for a single-family home.

A full appraisal carries the most weight, because the appraiser has seen the property firsthand. So for higher-stakes work, like an estate settlement, a divorce, or a property tax appeal, this is usually the scope you want. There is no data gap for anyone to poke at later.

The Exterior-Only Appraisal: A Look From the Curb

An exterior-only appraisal, sometimes called a drive-by, is what it sounds like. The appraiser views and photographs the outside of the home but does not go inside. For the interior, we rely on other sources, such as prior listings, public records, and whatever reliable data exists. On the legacy forms, this is the 2055.

It is faster and cheaper than a full appraisal. Still, there’s a trade-off. Without eyes on the interior, the appraiser cannot confirm condition, updates, or problems behind the front door. So lenders tend to reserve it for lower-risk situations, not for a purchase where the inside is a mystery.

The Desktop Appraisal: No Visit at All

A desktop appraisal goes one step further. The appraiser never visits the property. Instead, the whole analysis runs on data: MLS records, public records, and a floor plan that shows the interior walls. A licensed or certified appraiser still develops the opinion of value and signs the report, so it is a real appraisal, not an automated computer estimate.

Fannie Mae made desktop appraisals a permanent option back in March 2022, mainly for certain one-unit purchase loans. Their guidelines require a floor plan, not just an exterior sketch, so the appraiser can judge how the home actually functions. One rule is worth knowing: if a desktop appraiser ends up visiting and inspecting the property, it stops being a desktop and becomes a full appraisal. The scope defines the product, not the intention.

The three side by side
Scope Interior seen? Exterior seen? Legacy form Typical use
Full Yes, in person Yes, in person 1004 Purchases, high-stakes valuations
Exterior-only No (from data) Yes, in person 2055 Lower-risk refinances
Desktop No (data + floor plan) No (from data) 1004 Desktop Certain low-risk purchase and refi loans

One more option sits alongside these: the hybrid, where a trained third party collects the property data and the appraiser does the analysis from it. Still, the principle is the same. The less the appraiser sees in person, the more the result leans on someone else’s data.

Which One Will You Get?

For most home purchases, expect a full appraisal. It is the standard, and it gives the lender the most complete picture. By contrast, exterior-only and desktop appraisals show up more often in refinances and lower-risk loans, where the lender’s automated system signals that a lighter scope is acceptable.

Usually you don’t choose. The lender’s system decides what’s eligible. But you can ask which scope is being used, and it pays to ask. If you’re ordering an appraisal yourself, outside a loan, for a divorce, an estate, or a Cook County tax appeal, you can request a full interior appraisal. For those purposes, you generally should. After all, a value backed by an actual walkthrough is far harder to challenge.

What’s Changing in 2026

One big shift is landing in 2026, and it reshapes everything above. For example, the form numbers in this article, the 1004, the 2055, the 1004 Desktop, are being retired. Fannie Mae and Freddie Mac are replacing them with a single, dynamic report called the Uniform Residential Appraisal Report, or URAR, built on a data standard known as UAD 3.6.

Instead of a separate form for each scope, one report now flexes to fit the assignment, whether that’s a full interior inspection, an exterior-only, or a desktop. The timeline is set. In fact, lenders have been able to use the new format since early 2026. By November 2, 2026, it becomes mandatory, so every appraisal on a loan sold to Fannie Mae or Freddie Mac must use UAD 3.6. The old format then retires fully in May 2027. Fannie Mae’s UAD page tracks the details as they firm up.

So the labels are changing, but the underlying choice is not. Full, exterior-only, and desktop still describe how much the appraiser sees. That question outlives any form number.

The Form Changes, the Question Doesn’t

Strip away the form numbers and every appraisal answers the same thing: how well does the appraiser actually know this property? For instance, a full interior appraisal answers it with a walkthrough. An exterior-only answers it from the curb. A desktop answers it from data and a floor plan. Each has its place, and each carries a different level of certainty.

So when an appraisal lands on your desk, look past the format and ask what the appraiser was allowed to see. For anything that has to hold up, in court, in a negotiation, or in front of a lender, that scope is the whole ballgame.

Not sure which kind of appraisal your situation needs?

The right scope depends on what’s at stake. For an estate, a divorce, a tax appeal, or a lending decision, talk to PahRoo about the appraisal that will actually hold up.

Request an Appraisal

Frequently Asked Questions

What is the difference between a desktop and a full appraisal?
A full appraisal includes a physical inspection, inside and out. A desktop appraisal has no inspection at all; the appraiser works from data and a floor plan. Both are done by a licensed appraiser, but the full version rests on firsthand observation.
Does a desktop appraiser ever visit the property?
No. If the appraiser visits and inspects the home, it stops being a desktop appraisal and becomes a full one. The whole point of a desktop is that the analysis happens from data sources rather than a site visit.
Is an exterior-only appraisal less reliable than a full appraisal?
It carries less certainty about the interior. The appraiser sees the outside but relies on data for what’s behind the door. For lower-risk situations that’s often fine, but where interior condition matters, a full appraisal is stronger.
Which type of appraisal will my lender order?
Usually the lender’s automated system decides, based on the loan’s risk. Most purchases get a full appraisal. Lighter scopes like desktop or exterior-only show up more in refinances and lower-risk loans. You can always ask which one is being used.
Are appraisal forms like the 1004 going away?
Yes. By November 2026, Fannie Mae and Freddie Mac are replacing the legacy forms with one dynamic report called the URAR. The form numbers retire, but the scope choices, full, exterior-only, and desktop, carry over into the new report.

Need an Appraisal You Can Stand Behind?

As the industry shifts toward lighter, data-only products, the value of an appraiser who has actually seen the property only grows. So at PahRoo, the appraiser who develops the analysis is the one who signs the report. That accountability is the whole point.

PahRoo Appraisal & Consultancy, LLC helps homeowners, attorneys, accountants, bankers, and real estate professionals make confident decisions across the Chicago area. Whether you’re weighing a Cook County tax appeal, settling an estate, removing PMI, or navigating a divorce, our team is ready to help.

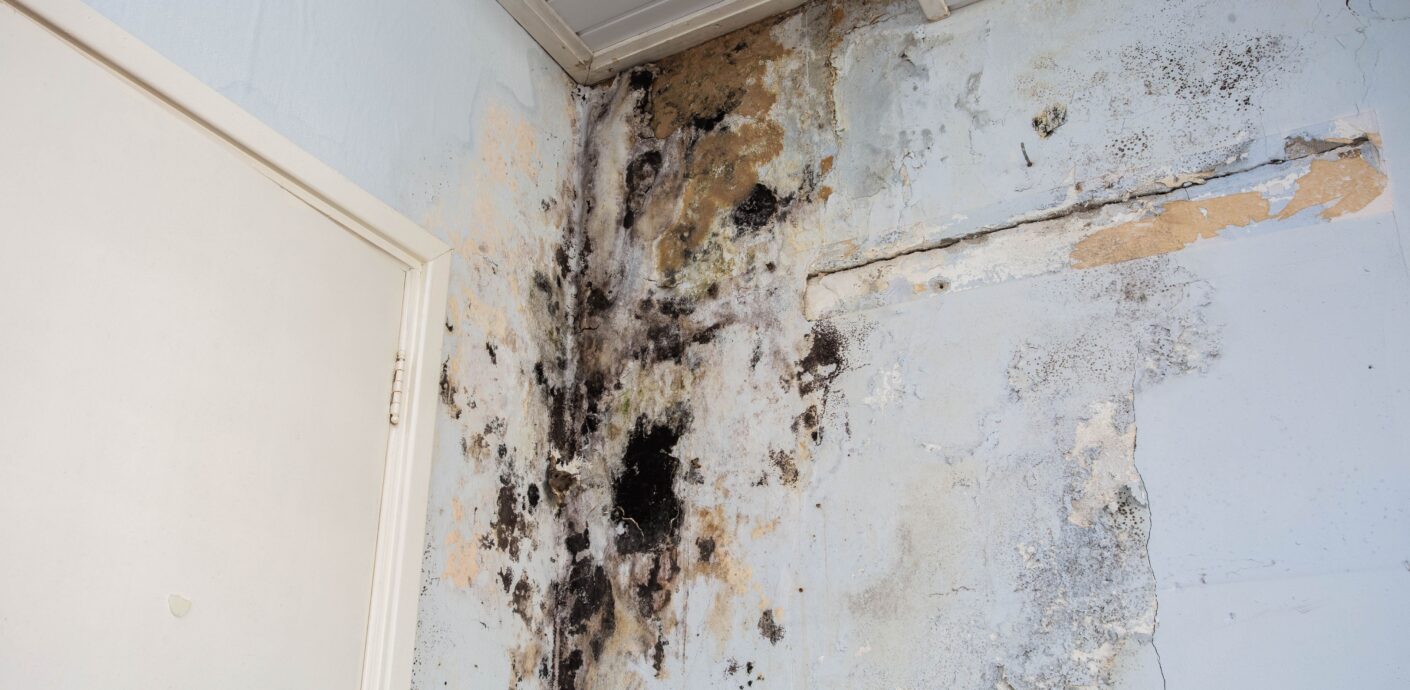
Mold remediation work completed before selling a home
How Mold Affects a Home Appraisal and Sale

Mold has a way of turning a smooth home sale into a tense negotiation. A small patch in a bathroom rarely sinks a deal. Visible growth spreading across a ceiling is a different conversation. If you’re getting ready to sell, knowing how mold affects a home appraisal helps you stay ahead of the questions buyers and lenders are about to ask.

By the end of this article, you’ll know:

  • Whether mold actually pulls down your appraised value
  • What a lender might demand before clearing the loan
  • How to handle mold before you list, and what to keep on file
How Mold Affects a Home Appraisal

Most sellers picture the cost of cleanup and stop there. The bigger issue is what mold usually signals. It points to moisture, and moisture points to a cause: a roof leak, a plumbing problem, poor ventilation, or water creeping in through the foundation. So when we spot mold, we start wondering what’s behind it.

That uncertainty is what worries buyers and lenders. A home with obvious mold often draws lower offers, or sits on the market longer than a comparable place with no moisture history. An appraiser’s job, after all, is to reflect how the market reads a property. So we note what’s visible and weigh how it affects value and sale ability.

What an Appraiser Will Notice

We are not mold inspectors, and we do not take air samples or open up walls. But during a standard residential appraisal, the visible signs of a moisture problem are hard to miss. The usual flags:

      • Visible mold on walls, ceilings, or around windows
      • Water stains and discolored patches
      • A musty smell that lingers in a room
      • Warped or damaged drywall
      • Signs of past leaks that were never fully sorted out

Much of this matters because of where mold leads. The EPA explains that mold needs steady moisture to spread. So a musty basement, or a stain nobody can account for, pulls more attention than its size might suggest.

How Mold Can Hold Up Your Financing

Mold can cost you time as well as money. Lenders watch closely for anything that reads as a health or safety concern. If visible mold turns up while a buyer is financing, the lender may pause and ask for more before clearing the loan.

That might mean remediation records, proof of repair, an extra inspection, or a professional evaluation. Each step adds days. Worse, when it all surfaces at the appraisal rather than earlier, the delay can put a contract date at risk.

Should You Remediate Before Selling?

There’s no single answer, because every house is different. Still, in most cases where the mold is visible or a buyer needs financing, dealing with it before you list pays off. It keeps the negotiation from collapsing into a fight over repairs, and it clears away a common reason for loan delays.

A few questions help you decide. How widespread is it? Have you fixed the moisture source, or only wiped away what you could see? Would a buyer notice it on a walkthrough? Could it trip up financing? Whatever you choose, hold on to the records. Good documentation reassures a buyer far more than a verbal “it’s been handled.”

A Word on Disclosure

Disclosure rules shift from state to state, and sometimes town to town. In a lot of places, sellers have to disclose known material defects, and mold can fall into that bucket. Hiding a known problem tends to create much bigger headaches later in the deal.

So before you list, get clear on what your state requires. When in doubt, ask a qualified agent or a real estate attorney. Being upfront builds trust, and it heads off arguments after closing.

What to Do Before the Appraiser Arrives
      1. Fix the moisture source first. Clean the mold without stopping the water and it comes right back, often worse than before.
      2. Keep your paperwork. Remediation invoices, contractor notes, inspection reports. Records answer the questions before anyone asks them.
      3. Repair what shows. Replace stained drywall and damaged materials, so nobody is writing up problems you have already solved.
      4. Flag it early. If the house has had a real mold issue, tell your agent and appraiser up front. Then everyone works from the facts.
Why Getting Ahead of It Pays Off

Mold does not automatically wreck a home’s value. What it does is shape how buyers, lenders, and the market see the place, and it can stall a sale when it shows up unaddressed. The real worry usually sits behind the mold: the moisture feeding it and the cost of putting things right.

So track down the source, fix it, document the work, and tidy up the visible damage before you list. Handle it early, and mold stays a manageable line item rather than the thing that derails your closing.

Not sure how mold could affect your home’s value?

Get a clear, independent read before a buyer or a lender turns it into a problem. PahRoo delivers defensible appraisals that show you exactly where you stand.

Request Your Appraisal

Frequently Asked Questions

Can mold cause a low home appraisal?

It can. If mold drags on the home’s condition, its saleability, or buyer interest, that can show up in the value. How much depends on how bad the problem is and how the market reacts to it.

Will an appraiser test for mold?

No. Appraisers aren’t mold inspectors, and we don’t run environmental tests. We will note visible mold or moisture damage if we see it during the walkthrough.

Should mold be removed before selling a house?

Often yes, particularly if it’s visible or a buyer is financing. Clearing it up early tends to steady buyer confidence and head off delays. The right call depends on how widespread it is and your local market.

Does mold affect property value?

It can. Value tracks buyer perception, repair costs, financing worries, and the overall condition of the property.

Can a lender deny financing because of mold?

Sometimes. A lender may ask for remediation, repairs, or an inspection before approving the loan if the mold raises a real health, safety, or condition concern.

Need an Independent Appraisal?

When condition concerns, repairs, or saleability questions cloud what a home is worth, an independent appraisal gives you a credible, well-supported answer before you negotiate or finance.

PahRoo Appraisal & Consultancy, LLC helps homeowners, attorneys, accountants, bankers, and real estate professionals make confident decisions. Whether you’re preparing to sell, settling an estate, removing PMI, navigating a divorce, or weighing how a property’s condition affects value, our team is ready to help.

Chicago housing market in June 2026 across city and suburban homes
Chicago Housing Market June 2026: A Four-County Split

There is no single Chicago housing market right now. That is the real story for the week ending 19 June 2026. Step back to the metro view and the picture looks calm and tight: few homes for sale, firm prices, steady sales. Look closer at the county level, though, and four very different markets come into focus. Knowing which one your home sits in matters far more than any citywide headline.

By the end of this article, you’ll know:

  • Why a metro-wide average can mislead you about your own home
  • Which Chicago-area counties have real buyer demand, and which are coasting on scarcity
  • Why a home selling “over asking” may not mean what you think
What the Chicago Housing Market Looks Like Right Now

Start with the wide-angle view. Across the metro, supply is very tight. Single-family homes and condos are both running near 1.4 months of supply, when a balanced market sits at four to six. Prices are up on the year, and condos are leading on demand. So by those headline numbers, it is a seller’s market.

The financing backdrop has a twist, though. The Federal Reserve has cut its policy rate over the past year, but the 30-year fixed mortgage rate has barely followed. It sits around 6.47%, while the federal funds rate is near 3.63%. Freddie Mac tracks that mortgage rate weekly, and the gap between the two is about 284 basis points. That is far wider than the 150 to 200 points that is normal. So the Fed’s cuts are getting stranded before they reach a buyer’s monthly payment.

One Metro, Four Different Markets

Once you split the metro by county, the calm surface breaks apart.

Cook County: firm prices, fading demand. Cook is the dense urban core, and it shows the most uneasy mix. For example, single-family pending sales are down about 11% on the year, and active inventory is down roughly 16%. Yet absorbed prices are up 9.6%. Prices are holding because there is so little to buy, not because buyers are pouring in. In other words, that is a more fragile kind of strength than it looks.

DuPage and Will: the real demand. These two suburban counties are the healthiest in the data. Single-family pending sales are up about 17% in DuPage and 15% in Will on the year, with inventory flat to rising. In short, this is demand-led growth, the kind that rests on people actually buying rather than on empty shelves.

Lake County: a big price number on thin support. Then there is Lake, with the strongest single-family price growth of the four, up 13.8% on the year. But that sits on falling inventory and only modest demand. It looks more like scarcity pricing than a real boom, so treat the figure as a single reading, not a trend.

Condos add one more wrinkle. Condo demand is positive in all four counties. Still, Will is adding condo inventory fast, up about 25% on the year, while buyers there are not keeping pace. Lake’s condo asking prices have dropped sharply too, though that comes from a small sample. Even so, both are early signs of softening at the edges. One note for condo shoppers: these figures leave out HOA dues, which are a real monthly cost and can change the math.

Single-family by the numbers
County Median sold price Price vs last year Buyer demand
Cook $390k +9.6% Down (scarcity holding prices)
DuPage $575k +8.1% Up strongly (demand-led)
Lake $529k +13.8% Modest (scarcity pricing)
Will $419k +4.8% Up strongly (demand-led)
Why “Over Asking” Can Be Misleading

This is where a little appraisal experience pays off. In Cook County, single-family homes show a sold-to-list ratio of 1.09. On the surface that reads as homes selling 9% over asking, a classic bidding-war signal. In fact, it almost certainly is not.

The ratio compares the median sold home to the median listed home, and those are two different baskets of houses. A number above 1.0 usually means the pricier homes are the ones selling while cheaper ones sit. In Cook right now, the affordable stock under about $360,000 is what’s left on the shelf, and the higher-priced homes are clearing. So the figure reflects which homes are selling, not buyers bidding each other up. Read it as a bidding war and you would badly overstate how hot the market really is. Pricing a property, or a loan against one, on that misread is how mistakes happen.

What This Means If You’re Buying, Selling, or Lending

If you’re selling, price to the market, not to a headline. About a quarter of listings in every county are cutting price, even with supply this tight. That tells you sellers are testing high, then trimming. An aspirational asking price tends to sit and then drop. By contrast, a realistic one moves.

If you’re buying, the genuine openings are in the demand-led suburbs, DuPage and Will, rather than in the headline price growth of Cook and Lake that leans on scarcity. In practice, if you’re eyeing a Will condo, the building inventory there may give you room to negotiate.

If you’re lending or valuing collateral, value is steadiest where price growth is demand-backed, which is DuPage and Will single-family. On the other hand, supply-led firmness, as in Cook and Lake, can reverse faster if inventory loosens. So a property-specific residential appraisal is the only way to know where a given home really stands.

For everyone, watch the mortgage spread, not just the Fed. Until the gap between mortgage rates and the policy rate narrows, a cheaper Fed policy will not automatically mean a cheaper mortgage.

Know Your County, Not Just the City

The Chicago housing market headline this week is firm prices and tight supply. That is true at the metro level, but it papers over four counties pulling in different directions. Cook is holding on scarcity. Meanwhile, DuPage and Will are carrying real demand. Lake is posting a big price number that may not hold.

So if you need to know what a specific property is worth in this market, the citywide average will not tell you. The county, the segment, and the individual home will. That is the difference between a number you can lean on and one that just sounds good.

A market headline won’t tell you what your home is worth.

Averages hide as much as they reveal, as this week shows. For a defensible read on your specific property, in your county, talk to PahRoo.

Request an Appraisal

Frequently Asked Questions

Is the Chicago housing market a buyer’s or seller’s market right now?

By the numbers, it’s a seller’s market across the metro. Supply sits near 1.4 months in both segments, well below the four to six months of a balanced market, and prices are up on the year. That said, conditions shift by county, so your local market may feel different.

Why are Chicago home prices rising while sales slow down?

In places like Cook County, prices are holding because there are so few homes for sale, not because demand is strong. When inventory shrinks faster than buyers fade, scarcity keeps prices up even as the number of sales falls.

Which Chicago-area counties have the strongest housing demand?

DuPage and Will lead on genuine demand. Single-family pending sales there are up roughly 15 to 17% on the year, with steady inventory. Cook shows falling demand, and Lake’s strong price growth rests on thin demand support.

Why haven’t mortgage rates dropped along with the Fed’s rate cuts?

Mortgage rates track long-term bond yields and lender risk pricing, not the Fed’s policy rate directly. The gap between the two is unusually wide right now, near 284 basis points, so most of the Fed’s easing isn’t reaching the mortgage rate a buyer actually pays.

If a home sells above asking price, does that mean there was a bidding war?

Not necessarily. A sold-to-list ratio above 1.0 across a whole market often just means the pricier homes are the ones selling while cheaper homes sit. It reflects which homes are clearing, not buyers bidding each other up. You need price-tier data to tell the two apart.

Need a Read on Your Specific Property?

Market reports describe the forest. An appraisal measures your tree. When you need to know what one property is worth, in one county, an independent appraisal gives you a credible, defensible answer.

PahRoo Appraisal & Consultancy, LLC helps homeowners, attorneys, accountants, bankers, and real estate professionals make confident decisions across the Chicago area. Whether you’re weighing a Cook County tax appeal, settling an estate, removing PMI, or navigating a divorce, our team is ready to help.


Family lawyer reviewing divorce property documents in Illinois
Disputed Property Value in Illinois Divorce: 3 Documents

Disputed Property Value in Illinois Divorce: Three Documents Every Family Lawyer Should Request

When property value is disputed in an Illinois divorce, family lawyers should request three documents before relying on either party’s estimate of value: property tax assessment records, prior mortgage appraisals, and broker price opinions. Reviewing these records early can uncover inconsistencies, strengthen negotiations, and help determine whether an independent appraisal is necessary.

Why Property Value Matters in Illinois Divorce

Real estate often makes Illinois divorce cases more difficult. Illinois law divides marital property through equitable distribution, meaning the court divides property fairly, not always equally.

For family lawyers, disputed property value in Illinois divorce cases can affect settlement leverage, asset division, support discussions, and trial strategy. A difference of even $50,000 or $100,000 can change the direction of negotiations.

Before relying on either party’s opinion of value, request these three documents.

Documents to Request When Property Value Is Disputed

The three most useful starting documents are:

Property tax assessment records
Prior mortgage or refinance appraisals
Broker price opinions or comparative market analyses

However, each document serves a different purpose. None should automatically replace a professional appraisal.

1. Property Tax Assessment Records

First, Family lawyers can often obtain property tax assessment records quickly and may provide useful background. For example, they can show assessed value, property classification, exemptions, and recent changes in assessment history.

However, assessors create tax records for property tax purposes. Tax authorities do not design these records to determine current market value in a divorce dispute.

Therefore, family lawyers should review assessment records to identify:

      • Sudden assessment changes
      • Possible tax appeal history
      • Exemption issues
      • Property classification concerns
      • Discrepancies between assessed value and claimed market value

Why this matters to your client:
Assessment records can reveal early warning signs before negotiations become more expensive, but attorneys should not treat them as the final answer.

2. Prior Mortgage or Refinance Appraisals

Next, if either spouse refinanced the property, obtained a home equity loan, or purchased the property during the marriage, a prior appraisal may exist.

In addition, these reports can provide helpful context, including property condition, comparable sales used at the time, prior market conclusions, and noted improvements.

Request copies of:

      • Mortgage appraisal reports
      • Refinance appraisal reports
      • Home equity appraisal reports
      • Purchase-related appraisal reports

While a prior appraisal may not reflect today’s market, it can show how the market viewed the property at a specific point in time.

Why this matters to your client:
Prior appraisals can expose unsupported claims, major market shifts, or changes in property condition that may affect settlement strategy.

3. Broker Price Opinions and Comparative Market Analyses

Finally, attorneys and real estate professionals commonly use Broker Price Opinions and Comparative Market Analyses during divorce discussions. They may help show what one party believes the property could sell for.

However, they are not the same as a real estate appraisal.

Brokers often prepare these opinions for listing strategy. Appraisers develop appraisals using a more formal scope of work, market analysis, and reporting process.

Family lawyers should request these documents to understand:

      • Each party’s position
      • Which comparable sales each party relies on
      • Whether assumptions are consistent
      • Whether a formal appraisal is needed

Why this matters to your client:
Understanding the basis for each side’s number helps reduce surprises and supports a more informed negotiation position.

When an Independent Appraisal Becomes Necessary

The three documents above can help frame the dispute; however, they may not resolve it.

Therefore, family lawyers should consider an independent appraisal when:

      • The spouses disagree on property value
      • The property contains significant equity
      • One party challenges the other party’s evidence
      • The property is unique
      • The case may proceed to litigation
      • The property includes rental, mixed-use, or commercial elements

Additionally, in Cook County and the Chicago metro area, market differences between neighborhoods can be significant. A property in Lincoln Park, Hyde Park, Oak Park, Evanston, or Naperville may require local market knowledge that generic online estimates cannot provide.

PahRoo’s Chicago appraisal services include residential and commercial appraisals, estate and divorce settlement appraisals, property tax assessment appeal support, and investment consulting.

FAQ: Disputed Property Value in Illinois Divorce
Question: What documents should a family lawyer request when property value is disputed?

Answer: Request property tax assessment records, prior mortgage or refinance appraisals, and broker 
price opinions or comparative market analyses. These documents help identify inconsistencies and determine 
whether an independent appraisal is needed.
Question: Can a property tax assessment be used as market value in divorce?

Answer: Not reliably. Assessors create tax assessments for taxation purposes. Those records may provide background 
information. It may help provide background, but it should not replace a professional appraisal in a disputed 
divorce matter.
Question: Is a broker price opinion the same as an appraisal?

Answer: No. A broker price opinion or comparative market analysis may support a listing discussion, but it is not 
the same as a real estate appraisal prepared for a legal or settlement-related purpose.
Question: When should a divorce attorney request an appraisal?

Answer: Attorneys should request an appraisal when the parties disagree on value, substantial equity is involved, 
the property is unique, or the case may proceed to litigation.
Protect Your Client with Better Property Evidence

Ultimately, disputed property value in Illinois divorce cases can delay settlements, increase conflict, and weaken negotiation strategy. By requesting the right documents early, family lawyers can identify weak assumptions, challenge unsupported claims, and protect their clients from avoidable risk.

When the value of real estate matters, do not rely on guesswork, outdated records, or informal opinions. Request a credible appraisal before property value becomes the obstacle that stalls the case.

Ready to clarify disputed property value in an Illinois divorce? Contact PahRoo to request an appraisal or speak with an appraisal expert today.

Chicago Housing Market 2026 showing home prices and inventory trends
Chicago Housing Market 2026: Prices Hold Firm as Demand Softens

Chicago Housing Market: What Week 24 Shows

The Chicago housing market continues to send mixed signals in 2026. Home prices remain resilient, inventory remains historically tight, and sellers continue to hold significant leverage. Yet beneath the surface, a different story is emerging: annual buyer demand is beginning to weaken.

The latest Chicago Metropolitan Statistical Area (MSA) housing data reveals a market that remains supply-constrained but increasingly affordability-constrained as well. While weekly activity improved during Week 24, year-over-year demand metrics suggest that elevated borrowing costs continue to limit transaction volume.

For real estate professionals, lenders, attorneys, and investors, understanding this divergence is essential when evaluating market conditions through the second half of the year.

Home Prices Continue to Rise Despite Demand Headwinds

One of the most notable findings from the latest market data is that prices continue to increase even as buyer activity softens.

Single-family homes recorded a median absorbed price of approximately $407,750, representing a 4.8% increase from the same period last year. Condominiums and townhomes experienced even stronger price growth, with median absorbed prices reaching nearly $324,000, an 8.0% year-over-year increase.

This pricing strength reflects one of the defining characteristics of today’s Chicago market: there simply are not enough homes available for sale.

Limited inventory continues to support values, allowing sellers to maintain pricing discipline despite slower transaction activity.

Inventory Remains Historically Low

Supply remains the foundation supporting today’s market.

Active single-family inventory is down more than 9% compared to last year, while condominium inventory has declined nearly 8%.

Perhaps more important is the months-of-supply metric. Both property segments are operating at approximately 1.3 months of inventory. In comparison, a balanced housing market typically contains five to six months of supply.

This severe shortage means buyers continue to compete for available properties, helping support prices even as affordability challenges reduce the number of active purchasers.

If you are advising clients on lending, estate planning, litigation, or tax matters, a real estate appraisal provides independent market analysis that helps reduce risk and support informed decisions.

Why Buyer Demand Is Beginning to Slow

Although prices remain firm, demand has weakened on an annual basis.

Single-family pending sales are now 4.4% below year-ago levels, while condominium pending sales have fallen 6.7%.

This marks a significant reversal from the stronger demand environment observed earlier this spring.

The primary driver appears to be affordability.

Many consumers expected lower Federal Reserve rates to create meaningful mortgage relief. However, mortgage rates have not declined as much as anticipated. According to data published through the Federal Reserve’s FRED database, mortgage financing costs remain elevated relative to recent monetary policy changes. The spread between mortgage rates and the Federal Funds Rate has widened substantially, limiting the impact of monetary easing on homebuyers.

As a result, financing costs remain elevated despite recent Federal Reserve actions.

What Chicago Housing Market 2026 Trends Mean for Real Estate Appraisals

Understanding the difference between market headlines and actual property value can help you avoid costly assumptions when making lending, legal, or investment decisions. Appraisers analyze local supply, demand, inventory levels, financing conditions, and comparable sales to determine credible opinions of value. As the Chicago Housing Market 2026 continues to show rising prices alongside weakening demand, professional appraisal analysis becomes increasingly important for lending, estate planning, divorce appraisal, tax appeal, and litigation-related decisions.

Monthly Payments Are Higher Than Last Year

One of the most important affordability indicators is not the mortgage rate itself, it is the monthly payment buyers must make. Recent housing research from the National Association of Realtors® continues to highlight affordability as one of the primary constraints affecting buyer activity nationwide.

Despite mortgage rates being slightly lower than a year ago, rising home prices have offset much of the benefit.

For a typical Chicago-area single-family home purchase, monthly principal and interest payments are now estimated to be slightly higher than last year. Condominium buyers have experienced an even larger increase due to stronger price appreciation in that segment.

Simply put, many buyers are paying more each month today than they would have paid a year ago.

This affordability pressure helps explain why annual demand metrics continue to soften even while prices remain strong.

Sellers Still Hold the Advantage

Current market conditions continue to favor sellers.

Several indicators support this conclusion:

      • Inventory remains extremely limited.
      • Months of supply remain well below balanced-market levels.
      • Price reductions have declined year over year.
      • Homes continue to sell close to asking prices.

However, the market is beginning to show subtle signs of adjustment.

New listings entering the market during Week 24 were priced slightly below the existing inventory pool. This suggests some sellers may be recalibrating expectations to align more closely with current buyer affordability constraints.

While this does not signal broad price weakness, it is an important trend worth monitoring during the summer selling season.

What This Means for Buyers, Sellers, and Investors

For Buyers

Affordability remains challenging, but opportunities may emerge as new listings enter the market at more competitive price points. Buyers should pay close attention to properties that have accumulated additional days on market.

For Sellers

Low inventory continues to provide leverage, but realistic pricing is becoming increasingly important. Homes priced in line with current market conditions are likely to outperform those anchored to aggressive expectations.

For Investors

The combination of firm pricing, constrained inventory, and slowing transaction volume favors a disciplined approach. Future appreciation assumptions should be conservative while mortgage financing conditions remain restrictive.

For Lenders and Financial Professionals

The disconnect between Federal Reserve policy and mortgage financing costs remains a key risk factor. Future demand will depend heavily on whether mortgage rate spreads begin to normalize.

The Outlook for the Chicago Housing Market

The Chicago housing market is not weakening in the traditional sense. Prices remain firm, inventory remains scarce, and sellers continue to maintain negotiating strength.

However, annual demand has clearly softened.

The market is transitioning from a supply-driven recovery toward an affordability-driven constraint. Unless mortgage financing conditions improve materially, transaction volume may continue to face pressure even while prices remain supported.

For now, the most likely scenario is a market characterized by limited inventory, stable-to-rising prices, and slower sales activity—a combination that creates both opportunities and challenges for real estate decision-makers throughout the Chicago metropolitan area.

Frequently Asked Questions About the Chicago Housing Market 2026
Question: How does the Chicago housing market affect real estate appraisals?
Answer: Real estate appraisers analyze local market conditions, inventory levels, buyer demand, financing trends, 
and comparable sales to develop credible opinions of value. Rising prices and changing demand patterns can influence 
appraisal conclusions depending on the specific property and market area.
Question: Should attorneys, accountants, and lenders rely on market headlines when determining property value?
Answer: No. Market headlines provide useful context, but property value is determined through detailed analysis of 
comparable sales, market conditions, and property-specific characteristics. A professional real estate appraisal provides 
a more reliable basis for financial, legal, and lending decisions.
Question: Why are home sales slowing if prices are still rising?
Answer: Affordability is the primary factor. Although mortgage rates have eased slightly, higher home prices have increased 
monthly payments for many buyers, reducing overall purchasing activity.

Whether you’re evaluating collateral risk, supporting litigation, planning an estate, or navigating a complex transaction, a professional real estate appraisal provides the independent analysis needed to make confident decisions.

Contact PahRoo Appraisal Consultancy to discuss your appraisal needs in the Chicago metropolitan area.

Speak with an Appraisal Expert

Real estate appraisal supporting family wealth transfer and estate planning decisions
Superadequacy in Estate Planning: Why Appraisals Matter

Superadequacy in estate planning refers to a situation where an estate has more assets than needed to meet the owner’s lifetime needs and family wealth-transfer goals. For estate attorneys, accountants, trustees, and financial advisors, that creates opportunity. However, it also creates risk when real estate values are based on assumptions instead of credible appraisal evidence.

When real estate represents a meaningful portion of the estate, an independent appraisal can help support gifting, trust funding, charitable planning, beneficiary equalization, and long-term wealth transfer decisions.

What Superadequacy Means in Estate Planning

Superadequacy often appears in high-net-worth estate planning when available assets exceed expected family needs. These estates may include primary residences, vacation homes, commercial buildings, rental properties, land, or family-held real estate.

Because these assets may appreciate over time, estate planning professionals must understand their current market value before recommending transfers or trust strategies.

Without credible property data, even a well-designed estate plan may rely on numbers that no longer reflect market reality.

Why Real Estate Can Complicate Wealth Transfer

Real estate values often influence estate and gift tax planning, particularly when significant assets are transferred during life or at death. Unlike cash or publicly traded investments, property value depends on location, condition, use, market demand, zoning, income potential, and comparable sales.

As a result, informal estimates can create problems.

For example, an outdated estimate may cause one beneficiary to receive more value than intended. Likewise, an unsupported property estimate may weaken tax planning, trust funding, or charitable giving decisions.

For attorneys and accountants, the risk is not just inaccurate numbers. The larger risk is building a planning strategy on unsupported assumptions.

When Estate Attorneys and Accountants Should Request an Appraisal

Estate planning professionals should consider a real estate appraisal when property value affects a legal, tax, or transfer decision.

Common situations include:

      • Funding a trust with real estate
      • Planning lifetime gifts
      • Preparing for estate tax exposure
      • Equalizing distributions among beneficiaries
      • Reviewing family-owned real estate
      • Supporting charitable contribution planning
      • Transferring partial property interests
      • Planning around commercial or income-producing assets

PahRoo provides estate and trust appraisal support for probate, estate planning, and wealth management needs across its service areas.

Appraisal Risks in Superadequate Estates

Superadequate estates often involve valuable assets, multiple advisors, and long-term family goals. Therefore, small appraisal errors can create large planning consequences.

The most common risks include:

      • Overstating or understating real estate value
      • Relying on online estimates
      • Using outdated property records
      • Ignoring highest and best use
      • Missing local market changes
      • Treating tax assessments as market evidence
      • Failing to document value before a transfer

These issues can affect beneficiary expectations, tax strategy, trust design, and professional recommendations.

For commercial or complex real estate, PahRoo’s appraisal services include residential, commercial, and tax appeal-related appraisal support for property professionals and clients who need reliable market evidence.

How Credible Appraisals Support Better Planning

A credible appraisal supported by Uniform Standards of Professional Appraisal Practice (USPAP) can provide objective market evidence for estate planning decisions. It helps attorneys, accountants, trustees, and advisors move from estimated numbers to documented market evidence.

That matters because real estate decisions often influence:

      • Which assets transfer first
      • Whether a trust is properly funded
      • How beneficiaries receive equitable treatment
      • Whether a gifting strategy is appropriate
      • How future disputes may be reduced
      • Whether a property should be retained, sold, or transferred

In markets such as Chicago, property values can vary significantly by neighborhood, property type, zoning, and condition. PahRoo’s Chicago appraisal services account for local market trends, diverse neighborhoods, and property-specific factors.

FAQ: Superadequacy in Estate Planning
Question: What is superadequacy in estate planning?

Answer: Superadequacy means an estate has more assets than needed to meet expected family, lifestyle, 
and wealth-transfer goals. It often leads to advanced planning around gifts, trusts, taxes, and 
generational wealth.
Question: Why does superadequacy require real estate appraisals?

Answer: Real estate appraisals help confirm market value before attorneys and accountants make planning 
recommendations. This reduces the risk of relying on outdated, informal, or unsupported property estimates.
Question: Can tax assessments replace appraisals in estate planning?

Answer: No. Tax assessments may provide background, but they do not replace a real estate appraisal 
prepared for estate planning, trust funding, or wealth transfer decisions.
Question: When should an appraisal be requested?

Answer: Request an appraisal when real estate affects gifting, trust funding, beneficiary distribution, 
tax planning, charitable giving, or estate administration.
Protect Wealth Transfer Decisions with Better Appraisal Evidence

Superadequacy in estate planning can create powerful opportunities for wealth preservation. However, those opportunities depend on clear, credible property information.

When real estate plays a major role in the estate, attorneys, accountants, trustees, and advisors should not rely on guesswork. A professional appraisal can clarify market value, reduce planning risk, and support stronger decisions for the client and future beneficiaries.

Ready to support an estate planning strategy with credible real estate appraisal expertise? Speak with PahRoo’s appraisal team today.

Equity buyout appraisal supporting divorce settlement negotiations
Equity Buyout Appraisal: Avoid Costly Divorce Mistakes

Equity Buyout Appraisal: Why Mid-Case Appraisals Beat Pre-Filing Estimates

When a divorcing couple owns real estate, one spouse may want to keep the property and buy out the other spouse’s share. That process depends on one critical number: the property’s current market value.

An equity buyout appraisal helps attorneys, accountants, bankers, brokers, and divorcing parties make that decision with more confidence. Like a professional divorce real estate appraisal, a mid-case appraisal provides a clearer, more defensible picture of a property’s value during active settlement negotiations. Instead of relying on an outdated pre-filing estimate, you can make important financial decisions based on current market evidence.

That timing matters.

Real estate markets shift. Interest rates change. Comparable sales update. Property condition may also change during the divorce process. Therefore, an estimate prepared before filing may no longer support a fair buyout months later.

For professionals guiding clients through divorce, the right appraisal timing can reduce disputes, protect financial interests, and support a more reliable settlement strategy.

Why Timing Matters for an Equity Buyout Appraisal

Divorce cases rarely move as quickly as expected. A pre-filing estimate may be several months old by the time attorneys begin serious settlement discussions.

During that time, the market can change in ways that affect equity. For example, a neighborhood may see stronger buyer demand, fewer comparable sales, rising inventory, or price softening. In addition, the property itself may need repairs, updates, or maintenance that were not part of the original estimate.

A mid-case equity buyout appraisal helps you work with current information instead of stale assumptions. As a result, both parties can negotiate from a more realistic financial position.

This is especially important when the property represents one of the largest marital assets.

Why Pre-Filing Estimates Can Create Risk

Pre-filing estimates can be useful for early planning. However, they are not always strong enough to support final buyout decisions.

Many early estimates come from online tools, informal opinions, or broad market assumptions. These sources may not fully account for:

      • Interior condition
      • Recent improvements
      • Deferred maintenance
      • Functional layout issues
      • Local comparable sales
      • Market changes after filing
      • Unique property characteristics

Consequently, the estimate may be too high, too low, or difficult to defend.

For the spouse keeping the property, an inflated estimate may lead to overpayment. For the spouse being bought out, an understated estimate may reduce their fair share. For attorneys and financial professionals, weak value support can create avoidable conflict during settlement.

A professional appraisal helps reduce that risk.

Why Mid-Case Appraisals Support Stronger Divorce Negotiations

A mid-case appraisal is completed after the divorce is underway but before final settlement decisions are made.

This timing gives attorneys and advisors a stronger foundation for negotiation because the appraisal reflects current market evidence. Instead of debating an old estimate, both sides can review a professional report supported by comparable sales, property analysis, and documented reasoning. In divorce matters, objective real estate evidence can help reduce valuation disputes and support more productive negotiations. The American Academy of Matrimonial Lawyers offers resources focused on family law issues and settlement considerations.

That matters because divorce negotiations often become emotional. A credible appraisal can help shift the conversation from personal opinion to market-supported facts. This is one reason why appraisals in divorce proceedings often play an important role in supporting productive settlement discussions.

For attorneys, this can support mediation, settlement conferences, and court preparation. For accountants and financial advisors, it can clarify asset division, cash flow planning, refinancing needs, and long-term financial impact.

For brokers and bankers, it provides a clearer basis for next steps when a refinance, sale, or ownership transfer is part of the divorce strategy.

What an Equity Buyout Appraisal Helps You Clarify

A well-timed equity buyout appraisal helps answer practical questions that affect the settlement.

These may include:

      • What is the property worth now?
      • How much equity is available?
      • Is the buyout amount reasonable?
      • Does refinancing appear realistic?
      • Are both parties relying on the same market evidence?
      • Could the value conclusion withstand scrutiny?

This clarity can help prevent delays. It can also reduce the chance that one party later challenges the buyout because the value was based on an outdated estimate.

In other words, the appraisal is not just about the property. It is about reducing financial uncertainty at a critical point in the case.

What Actually Distorts the Buyout Math

A buyout looks simple: take the appraised value, subtract the mortgage, split the equity. One spouse refinances or writes a check for the other’s share.

But three things quietly distort that math and each one can turn a fair-looking agreement into one that unwinds later.

  • Selling costs that never get counted. If the house actually sold, the sale would cost roughly 6–8% in commissions, transfer taxes, and closing costs. A buyout at full appraised value hands the leaving spouse a number they could never have netted in a real sale. Whether to adjust for this is genuinely debated, but it belongs on the table before the value is locked.
  • Refinance reality. The spouse keeping the house usually has to refinance to fund the buyout. Often on one income, at today’s rates. If they can’t qualify, the agreement can collapse after the decree is signed.
  • Market risk transfer. The spouse who keeps the house takes on all of it, every future rise or decline. The leaving spouse locks in a fixed number. In an uncertain market, that’s a real allocation of risk, not a footnote.

All three rest on one thing: an appraised value that is actually current and correct. If it’s off, every adjustment built on top of it is off too.

When Should You Order a Mid-Case Divorce Appraisal?

A mid-case appraisal is often helpful when the divorce has moved beyond early planning and settlement terms are beginning to take shape.

You should consider ordering one when:

      • One spouse plans to keep the property
      • The case has been pending for several months
      • The market has shifted since filing
      • The property has significant equity
      • Earlier estimates are inconsistent
      • Mediation or settlement discussions are approaching
      • A refinance or cash buyout is being considered

The goal is to avoid waiting until the final stages, when a disputed property value can stall progress.

By ordering the appraisal before settlement pressure intensifies, professionals can give clients better information and more room to negotiate.

Why Attorneys and Financial Professionals Benefit

For attorneys, a current appraisal can strengthen the legal and financial basis of a proposed settlement. It provides support for negotiations and helps reduce reliance on unsupported estimates.

For accountants, the appraisal can help clarify the client’s broader financial picture. Real estate equity often affects tax planning, liquidity, retirement assets, and future housing decisions.

For bankers, a realistic property value can inform refinancing discussions and buyout feasibility.

For brokers, the appraisal can help clients compare the financial impact of keeping the property versus selling it.

Therefore, the professional benefit is clear: better information leads to better guidance.

Equity Buyout Appraisal vs. Online Estimate

Online estimates are convenient, but convenience is not the same as credibility.

An online estimate may be generated without seeing the property, reviewing its condition, or analyzing the most relevant comparable sales. In a divorce, that can be a costly weakness.

An equity buyout appraisal provides a more reliable foundation because it considers the property itself, not just public data. It also creates documentation that attorneys and financial professionals can use when explaining or supporting the buyout number.

That documentation matters when both parties need confidence in the result.

What This Means for Your Settlement

In a divorce equity buyout, timing can change the outcome.

A pre-filing estimate may help start the conversation, but it should not carry the weight of a final settlement months later. By the time both sides are negotiating seriously, the market may have moved, the property condition may be clearer, and the financial stakes are usually sharper.

A mid-case equity buyout appraisal gives attorneys and advisors a stronger number to work from. It helps reduce guesswork, narrow disputes, and support a buyout that both sides can evaluate with greater confidence.

For clients, that means fewer surprises. For professionals, it means better support for settlement decisions.

FAQ: Does an equity buyout appraisal determine how much one spouse must pay the other?
Answer: Not necessarily. An appraisal provides an independent opinion of the property's market value. 
The final buyout amount may also be influenced by mortgage balances, other marital assets, negotiated 
settlement terms, and guidance from legal or financial advisors.
FAQ: Can an equity buyout appraisal be used if the property is jointly owned with other family members?
Answer: In some situations, yes. However, the ownership structure and purpose of the appraisal may affect 
the scope of work. When multiple owners are involved, attorneys and advisors often use the appraisal as one 
component of a broader ownership or settlement discussion.
Need Support for a Divorce Equity Buyout?

Navigating a divorce involving real estate can be complex. PahRoo provides independent appraisals that help attorneys, financial professionals, and property owners make informed decisions when equity buyouts are being considered.

Property condition concerns identified during home appraisal inspection
Pest Infestations and Property Appraisals

Pest Infestations and Property Appraisals: When an Inspection Becomes a Safety Issue

The fleas started jumping almost immediately.

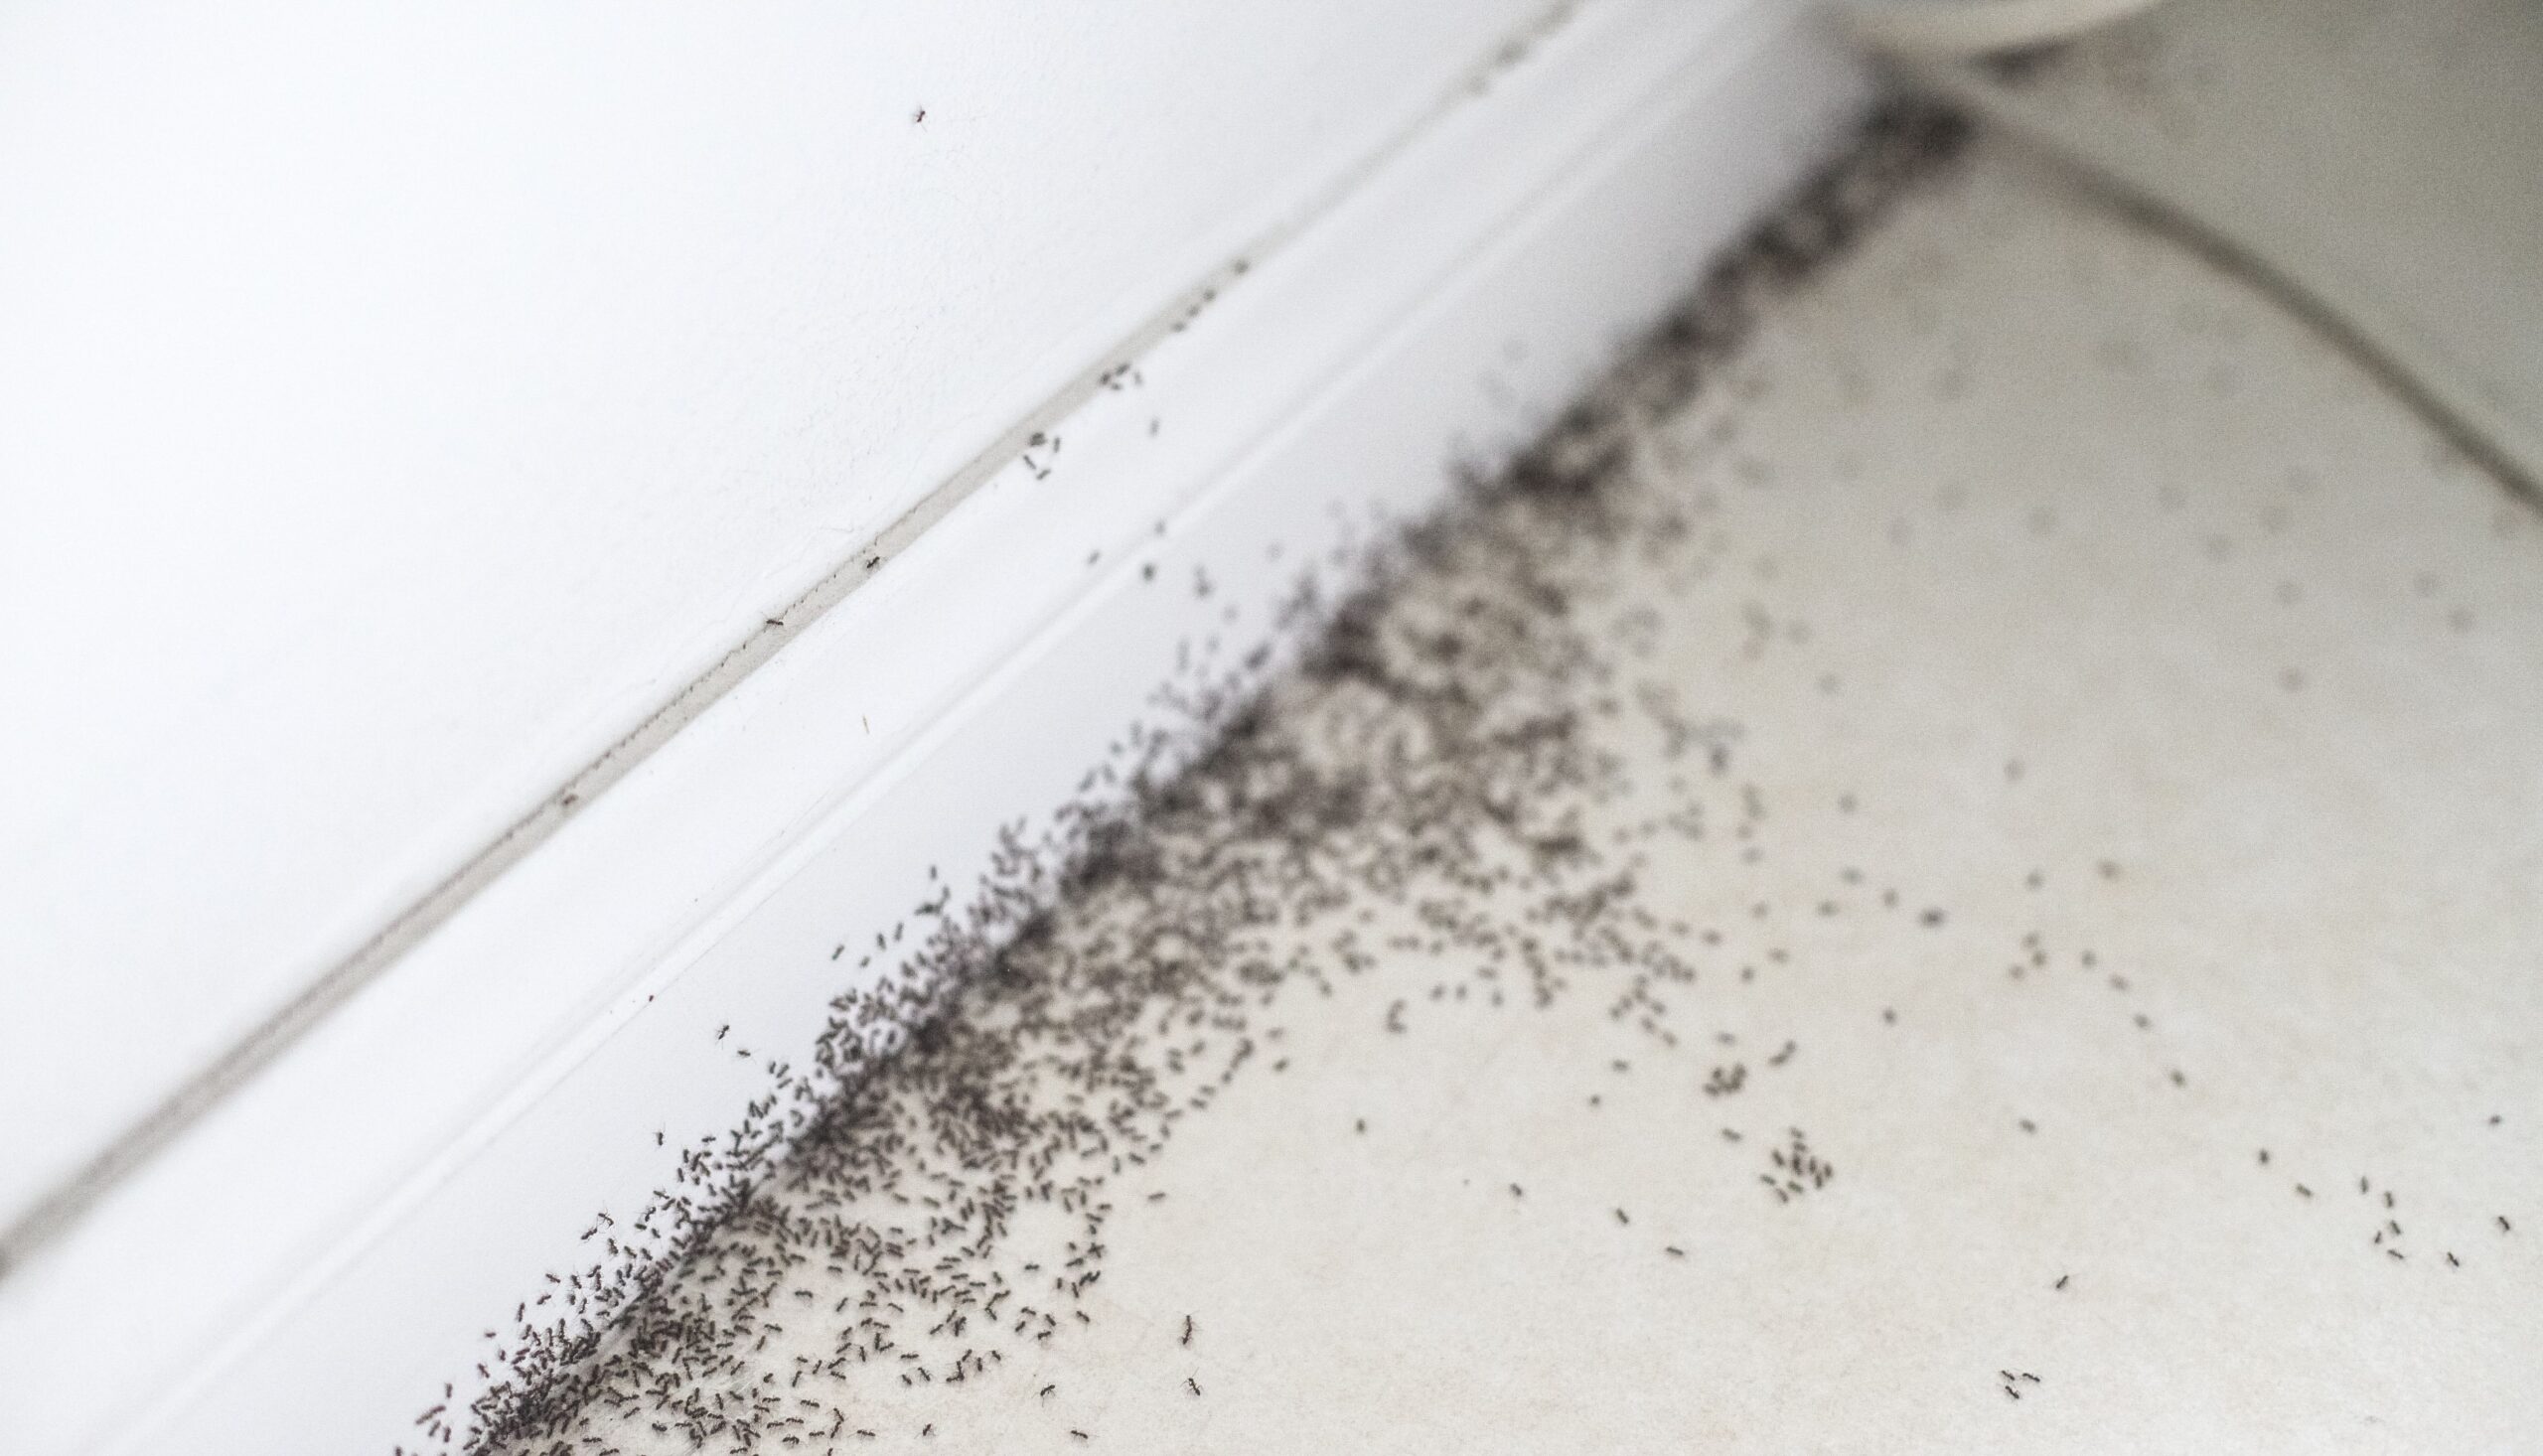
A routine residential appraisal inspection quickly turned into something more serious. As one of our appraisers moved through the home, active fleas were present throughout the property. The appraiser saw cockroaches in multiple areas. The appraiser could not treat the condition as isolated, minor, or easy to ignore.

At that point, the assignment was no longer just about documenting bedrooms, measuring the structure, and observing finishes.

It became a safety issue.

For appraisers, brokers, lenders, attorneys, accountants, and property owners, this type of situation raises an important question: when does a pest infestation become more than a condition concern?

The answer matters because pest infestations can affect safety, marketability, financing, and the timeline of a transaction.

Why Pest Infestations Matter in a Property Appraisal

Appraisers are not pest inspectors. Their role is not to diagnose infestations, determine treatment plans, or certify whether a property is pest-free.

However, an appraiser must observe and report visible property conditions that may affect the assignment.

That distinction is important.

Visible fleas, roaches, rats, or other pests may point to larger concerns during an inspection., the issue may point to larger concerns, including deferred maintenance, moisture problems, sanitation issues, damage, or reduced marketability.

For the client, this matters because visible infestation can create risk before closing. A lender may require additional review. A buyer may hesitate. A broker may face delays. An attorney may need clearer documentation for a legal matter.

When the appraiser identifies the issue early, everyone can respond sooner.

When the Inspection Becomes a Safety Concern

No appraisal assignment is worth risking personal health or safety.

In this case, the appraiser had to make a professional judgment call. Continuing the inspection meant prolonged exposure to active pests. Leaving too soon could limit the available property observations. Ignoring the issue was not an option.

That is where experience matters.

An appraiser must document what is observable, communicate clearly with the client, and avoid making unsupported conclusions. The appraiser should also note any limitations when the condition prevents a full or safe inspection.

For property owners and professionals, this creates an important takeaway: unsafe property conditions can limit the inspection and may affect how the appraisal report is completed.

Property condition concerns identified during home appraisal inspection

Condition Issue or Value Issue?

A pest infestation usually starts as a condition issue.

But depending on severity, it can become a marketability or financing concern.

A minor, isolated issue may have limited impact if it is quickly corrected. A severe infestation may raise questions about habitability, buyer resistance, repair needs, or lender requirements.

That does not mean every pest problem automatically changes the final opinion of value. It means the condition must be considered in context.

The appraiser may need to ask:

      • Does the infestation appear active?
      • Is it widespread?
      • Could it affect health or safety?
      • Did it limit the inspection?
      • Would typical buyers react negatively?
      • Could the lender require treatment or further inspection?

These questions protect the integrity of the appraisal and give the client a clearer picture of risk.

Why Lenders Care About Pest Infestations

Lenders are concerned with collateral risk. If a property has obvious health, safety, or habitability concerns, the lender may need those issues addressed before the loan can move forward. For FHA-related assignments, HUD guidance requires appraisers to consider property conditions connected to safety, security, and soundness, which is why visible infestation concerns may need additional review. See the FHA Single Family Housing Policy Handbook 4000.1.

That can lead to further inspection, treatment documentation, repair requirements, or a subject-to appraisal.

For brokers and borrowers, this matters because unresolved infestations can delay financing. For bankers, it creates a collateral review issue. For attorneys and accountants, it may affect estate, divorce, litigation, or tax-related property decisions.

A credible appraisal helps decision-makers understand what the appraiser observed and why it matters.

When a Subject-To Appraisal May Be Needed

In some cases, the appraiser may complete the appraisal subject to corrective action.

For pest infestations, this may include professional treatment, repair of related damage, or verification that the condition has been addressed.

This is not about creating unnecessary obstacles. It is about protecting the client, lender, and transaction from avoidable risk.

Clear documentation helps prevent confusion when a property condition could affect safety, habitability, or market acceptance.

What Brokers and Realtors Can Learn From This

Early disclosure helps everyone.

Early disclosure of known pest activity, water intrusion, odor, damage, or other condition concerns can prevent last-minute surprises.

For brokers, this can mean fewer financing delays, better client expectations, and stronger professional credibility.

An appraiser walking into a severe infestation without warning creates unnecessary risk. A broker who communicates known issues upfront helps the process move with fewer disruptions.

What Attorneys, Accountants, and Bankers Should Know

For professional decision-makers, pest infestations are not just a property nuisance.

They can affect the reliability of assumptions, the timing of reports, the need for additional documentation, and the usefulness of the appraisal in financial or legal decisions.

In divorce, estate, tax appeal, lending, or litigation matters, property condition can materially affect how a property is understood.

A well-supported appraisal gives you clearer documentation, stronger decision support, and fewer surprises.

The Professional Takeaway

The lesson from this inspection is simple: appraisers must know when a routine assignment has become a risk issue.

Appraisers should document pest infestations carefully, communicate them professionally, and handle them with sound judgment. The appraiser should not overstep into pest inspection work, but should never ignore visible conditions.

For clients, the benefit is clarity.

You gain a better understanding of how property condition may affect financing, timing, marketability, and risk. You also gain professional documentation that supports smarter decisions before a transaction, dispute, or financial review moves forward.

When property conditions create uncertainty, the right appraisal can bring the issue into focus.

Don’t Let Property Conditions Derail Your Transaction

Whether you’re dealing with a lending decision, estate settlement, divorce proceeding, tax appeal, litigation matter, or pre-sale planning, unexpected property conditions can create significant risk if they are not properly documented and understood.

A credible appraisal provides more than a number. It provides the independent analysis, market insight, and professional documentation needed to make confident decisions and avoid costly surprises.

If you need a residential appraisal and want experienced professionals who understand both the property and the risks behind it, PahRoo is ready to help.

Discuss your situation with an experienced appraiser and receive the guidance you need before making an important real estate, financial, or legal decision.

Frequently Asked Questions About Pest Infestations and Property Appraisals
Question: Can a pest infestation affect a home appraisal?

Answer: A pest infestation can affect a property appraisal when it raises concerns about safety, habitability, 
deferred maintenance, or marketability. While appraisers do not diagnose pest problems, they must report 
observable conditions that could influence a lender's decision, a buyer's perception, or the overall 
appraisal assignment.

Question: Will a lender require pest treatment before closing?

Answer: It depends on the severity of the infestation and the loan program. 
Significant pest activity may prompt a lender to request additional inspections, treatment documentation, 
or repairs before the loan can move forward. Addressing known issues early can help reduce delays 
during underwriting.
Question: What should property owners do before an appraisal if they know there is a pest problem?

Answer: Property owners should address active infestations whenever possible and disclose any 
condition issues that may affect the property. Early treatment and transparency can help prevent 
surprises, reduce transaction delays, and provide a clearer understanding of the property's condition during 
the appraisal process.

NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712