Category: Residential Appraisal

Request a quote

Our blog

Latest news
& events

ppraiser photographing a house from the sidewalk during a drive-by appraisal
The Appraiser Stayed Outside. Is That Normal?

Maybe your lender said the appraiser won’t need to come inside. Or maybe you heard there won’t be an appraisal at all. A drive-by appraisal, a desktop appraisal and a hybrid appraisal each value a home with less time on site than a traditional appraisal. Some loans skip the appraisal entirely. This guide covers how each one works and when it’s worth asking for more.

By the end of this article, you’ll know:

  • What a drive-by, desktop and hybrid appraisal each include
  • Why some loans close with no appraisal at all
  • What the new appraisal report changes starting November 2

What a Drive-By Appraisal Includes

A drive-by appraisal is another name for an exterior-only appraisal. The appraiser visits the property but stays outside. They look at the house, the lot and the street, and they take photos. Then they fill in the interior details from public records, listing data and past reports. Our post on the types of home appraisals compares full, exterior and desktop appraisals.

Fannie Mae and Freddie Mac have long used a separate report for this, the Exterior-Only Inspection Residential Appraisal Report. It’s known as the 2055. It’s one of the older forms now being replaced, according to the Fannie Mae and Freddie Mac lender readiness kit.

The limitation is easy to see. An appraiser on the sidewalk can’t see a new kitchen, a finished basement or water damage. So the value leans on how accurate the records are. Either way, the appraiser has to state what was and wasn’t inspected. That disclosure is part of the national appraisal standards, as state appraiser regulators explain.

Desktop Appraisals Happen Without a Visit

A desktop appraisal skips the site visit completely. Under Fannie Mae’s desktop appraisal rules, the appraiser doesn’t inspect the home or the comparable sales in person. Instead, they work from records, listing data, photos, video and a floor plan. The homeowner or another party can supply some of that. Still, the appraiser has to verify it with a source that has no stake in the deal.

For a Fannie Mae loan, a desktop appraisal is only an option when all of these are true.

  • The home is a one-unit property, such as a house or a unit in a planned development.
  • You’ll live in it as your main home.
  • It’s a purchase, not a refinance.
  • The loan is 90% of the home’s value or less.
  • Fannie Mae’s automated underwriting system approves the loan.

Condos, second homes, investment properties and every type of refinance are left out. So if you’re refinancing, don’t expect a desktop appraisal on a Fannie Mae loan.

Hybrid Appraisals Split the Work in Two

A hybrid appraisal divides the job between two people. First, a trained third party visits the home and collects data on the inside and outside. Fannie Mae’s hybrid appraisal rules name real estate agents, insurance inspectors and appraisers as examples. Then a licensed appraiser uses that data to reach a value.

Hybrids cover more situations than desktops do. They can be used for purchases and refinances, including cash-out refinances. One-unit homes and condos qualify, and so do second homes and investment properties. Two- to four-unit buildings and manufactured homes don’t.

For you, the visit may feel a lot like a standard home appraisal. The difference is that the person walking through may not be the person who signs the report.

When the Lender Skips the Appraisal

Sometimes there’s no appraisal at all. Fannie Mae’s underwriting system can offer what it calls value acceptance. When the lender takes that offer, no appraisal is required. In general, Fannie Mae needs to already have a prior appraisal of the home in its data before it will consider this.

You may still hear the older name. This used to be called an appraisal waiver, but Fannie Mae dropped that term in its September 3, 2025 Selling Guide update. There’s also a middle option called value acceptance plus property data. In that case, someone collects information at the home, but nobody writes an appraisal report.

Skipping the appraisal can save time and a fee. It also means no appraiser has looked at this particular home for this loan.

What the New Appraisal Report Changes

Starting November 2, 2026, appraisals on loans sold to Fannie Mae and Freddie Mac move to a new format. The old numbered forms, including the exterior-only, desktop and hybrid versions, are replaced by one report. It’s called the Uniform Residential Appraisal Report. According to Freddie Mac’s FAQ on the redesign, that report supports traditional, hybrid, desktop and exterior appraisals. So all four types continue. The report simply labels which one it is, instead of using a different form number. Our article on the new appraisal report shows what changed on the page.

Some lenders got extra time, though. Fannie Mae and Freddie Mac offered a one-time policy exception that lets approved lenders keep sending the older format through May 19, 2027.

A Few Pointers for Loan Officers

If you’re a lender or loan officer, three things can save a borrower some confusion. First, don’t promise a desktop appraisal on a refinance, because Fannie Mae doesn’t allow one. Second, form numbers are going away, so the new report identifies the type by its valuation method instead. So your order should spell out which one you need. Finally, tell borrowers that desktop and exterior-only appraisals lean on records. If they added a bathroom or finished the basement, permits and accurate listing details are what the appraiser will see.

When You Order the Appraisal Yourself

Not every appraisal is for a mortgage. Homeowners also hire appraisers for inherited homes, divorces, tax appeals and private sales. Our guide on when you need a home appraisal covers each one. In those cases, the lender rules above don’t apply. Instead, the appraiser decides the scope of work, including how much of the property to inspect, based on how the appraisal will be used.

That’s why an exterior-only appraisal can sometimes work, for example when nobody can get inside a relative’s house. Even so, if the interior affects the value, say so up front. A recent remodel, an unfinished basement or storm damage can all move the number. If you’re in the Chicago area, our Chicago real estate appraisals page explains how ordering works.

Ask Which Type You’re Getting Before the Visit

Whether a lender orders the appraisal or you do, it’s fair to ask which kind it is and what the appraiser will actually see. Then you can share anything the records might miss, like recent upgrades or repairs. A short conversation before the visit usually means fewer surprises when the report comes back.

Not Sure Which Appraisal Fits Your Situation?

Tell us what the appraisal is for and what’s changed at the property. We’ll talk through what kind of inspection makes sense.

Ask About Your Appraisal

Frequently Asked Questions

Is a drive-by appraisal the same as an exterior-only appraisal?

Yes. Both terms describe an appraisal where the appraiser inspects the outside of the home but doesn’t go in. Interior details come from records, listing data and past reports.

Can I get a desktop appraisal for a refinance?

Not on a Fannie Mae loan. Fannie Mae limits desktop appraisals to purchases of one-unit homes you’ll live in, with a loan of 90% of the value or less.

What is value acceptance?

Value acceptance is Fannie Mae’s offer to approve a loan without an appraisal. It used to be called an appraisal waiver, and Fannie Mae retired that name in September 2025.

Who visits the home in a hybrid appraisal?

A trained third party, such as a real estate agent, insurance inspector or appraiser, collects data at the home. A licensed appraiser then uses that data to complete the appraisal.

Do these appraisal types still exist under the new report?

Yes. The new Uniform Residential Appraisal Report supports traditional, hybrid, desktop and exterior-only appraisals. The type is labeled inside the report instead of by a form number.

About PahRoo

PahRoo Appraisal & Consultancy is an independent appraisal firm based in Lincolnwood, Illinois, led by Michael Hobbs, MAI, SRA. We appraise homes and commercial property in Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix and Naples. If you have a question about an appraisal you’ve been offered, email appraisal@pahroo.com or call 773-388-0003.

Two printed pages of a new appraisal report on a wooden desk
Your Appraisal Report Looks Different Now

If you’re buying or refinancing a home this fall, the appraisal your lender sends you may not look like the one you got last time. Starting November 2, 2026, most appraisals for loans sold to Fannie Mae and Freddie Mac move to a new appraisal report. The work behind it is the same. The paperwork just reads differently.

By the end of this article, you’ll know:

  • Why your appraisal report looks different starting this November
  • What changed on the page and what stayed the same
  • Why some loans will still get the old version for a while

Why the New Appraisal Report Is Showing Up Now

For years, mortgage appraisals came on a set of fixed forms. A house had one form, a condo had another, and a small rental building had a third. Anything extra went into a free-form addendum at the back.

Fannie Mae and Freddie Mac are replacing that system. According to Freddie Mac’s UAD 3.6 FAQ, the two companies are retiring more than a dozen older forms. One redesigned Uniform Residential Appraisal Report, or URAR, takes their place. You may also see the name of its data standard, UAD 3.6, in lender emails.

The new report becomes the rule for new appraisals submitted on or after November 2. Still, lenders could start using it in January, so you may have seen one already.

What Looks Different on the Page

The biggest change is that the report now follows your home instead of a form number. Freddie Mac says the property’s own data drives the report. So a condo, a bungalow with a coach house, and a two-flat all use the same report, and it adjusts to what the property actually has.

It may also feel more familiar. Freddie Mac says the redesigned report has a similar look and feel to the loan application and the Closing Disclosure you already sign. The old General Addendum also disappears. Instead, the appraiser’s comments sit inside each section, right next to the details they explain.

Condition and quality ratings got clearer definitions. The report can now rate the inside and outside of a home separately, which helps when one is in much better shape than the other. Accessory units, like a coach house, also show up in a more consistent way.

Finally, if your loan officer ever called it “a 1004,” that label is on its way out. The form numbers retire along with the forms.

See What the New Appraisal Report Looks Like

Reading about a report only goes so far, so here’s how to see one. Fannie Mae publishes sample reports on its UAD webpage. Scroll to the UAD Documentation section and choose Appendix D-1, URAR Sample Scenarios and XML Files. It downloads as a zip file, and each sample inside comes as a PDF.

If you only open one, start with the sample labeled SF5. Fannie Mae calls it the best example of a typical, straightforward appraisal in the new format. Two others, SF3 and SF4, show a home with an accessory unit, one in a separate building and one in the basement.

Still, don’t expect yours to match the samples exactly. The report only shows what applies to your home and the work the appraiser did, so no two will look the same.

What Stays the Same

This redesign changes the report’s layout and the way it’s delivered. Freddie Mac says the purpose of the report has not changed. It is still an appraiser’s opinion of value for a mortgage decision. The condition and quality rating scale is also the same, even though Fannie Mae and Freddie Mac rewrote its definitions.

The new format also covers every kind of assignment. It handles a full inspection, a hybrid, a desktop, or an exterior-only appraisal. Our guide to the types of home appraisals explains how those differ.

You also keep the right to see it. The CFPB explains that for a first-lien mortgage, your lender must give you a free copy. It has to arrive promptly after the appraiser finishes and no later than three days before closing. If this is your first appraisal, our home appraisal process guide walks through each step.

Why Some Loans Will Still Get the Old Version

Not every report switches on the same day. The rule depends on when the report is first submitted to the Fannie Mae and Freddie Mac portal, not on when you applied for the loan.

Some lenders also asked for more time. Under the published transition timeline, a lender with an approved exception can keep sending the old format until May 19, 2027.

Government-backed loans run on their own schedule. FHA began accepting the new format on October 1, 2026. But lenders can still send FHA appraisals in the old one, and FHA has not set a mandatory date. VA and USDA set their own timelines as well.

So if you refinance in December and the report looks like the old version, that’s not a mistake. It may just be your lender’s timing or your loan type.

For Lenders, the Submission Date Is What Counts

If you’re a lender or loan officer, the real risk sits in your pipeline. The mandate follows the first UCDP submission date, so an old-format report ordered in October but submitted after November 2 needs an exception.

Three habits help. First, state UAD 2.6 or 3.6 in the engagement letter, which is where Freddie Mac says the appraiser should find it. Second, match formats on follow-up work. UCDP won’t accept mixed standards under one Doc File ID, so an update or completion report has to match the original. For FHA cases, keep one format for every submission on a case number.

Third, mark March 1, 2027 on the calendar. If you’re working under an exception, UAD 2.6 reports lose collateral rep and warranty relief for value from that date.

Reading Your Report When It Arrives

Give the new layout a few minutes before you judge it. Find the opinion of value first. Then check the basics, like the address, square footage, and the number of bedrooms and bathrooms. If something looks wrong, raise it with your lender, since the appraiser prepared the report for the loan. A clear question about a specific fact is easier to resolve than a general worry about the number.

Need an Appraisal Outside the Mortgage?

Selling, settling an estate, dividing a home in a divorce, or questioning a tax bill? You can hire PahRoo directly for those. Tell us about the home and what the value is for.

Request a Home Appraisal

Frequently Asked Questions

What is the new appraisal report?

It’s the redesigned Uniform Residential Appraisal Report, or URAR, from Fannie Mae and Freddie Mac. It replaces more than a dozen older appraisal forms with one report that adjusts to the property.

What is UAD 3.6?

UAD 3.6 is the data standard behind the new report. It is required for new appraisals submitted to Fannie Mae and Freddie Mac on or after November 2, 2026, though lenders with an approved exception can use the old format until May 19, 2027.

Does the new appraisal format change my home’s value?

The format changes how the report is organized and delivered. Freddie Mac says the report’s purpose has not changed, and the condition and quality rating scale is the same. Your value still comes from the appraiser’s analysis of your home and your market.

Do FHA and VA loans use the new appraisal report?

FHA started accepting it on October 1, 2026, but has not set a mandatory date, so lenders can still use the old format for FHA loans. VA and USDA set their own schedules.

Will I get a copy of my appraisal?

Yes. For a first-lien mortgage, your lender has to give you a free copy promptly after it’s completed and no later than three days before closing.

A Chicago Team Already Working in the New Format

PahRoo Appraisal & Consultancy appraises homes and condos for homeowners, lenders, and attorneys across Chicago and Cook County, and our residential team already produces reports in the new format. Michael Hobbs, MAI, SRA, signs our Illinois reports. See our Chicago appraisal services to learn how we work.

Appraiser filling up an appraial report of a Chicago brick home during a home appraisal
When Do You Actually Need a Home Appraisal?

Most people think about an appraisal only when a lender orders one. So when do you need a home appraisal? More often than that, and a few of those moments carry real money, because the number ends up in a tax return, a settlement, or a closing statement.

By the end of this article, you’ll know:

  • Which life events usually call for an appraisal, and which ones don’t
  • When the lender handles it and when you order one yourself
  • What a buyer can do if the appraisal comes in low

When Do You Need a Home Appraisal for a Mortgage?

If you’re buying with a loan or refinancing, the lender orders the appraisal and you usually pay for it. The report protects the lender’s collateral. It tells them the home supports the loan amount.

That isn’t always the case anymore, though. On some loans, Fannie Mae’s underwriting system can offer value acceptance, which means no appraisal for that transaction. It’s the lender’s option, not yours. Two to four unit buildings and homes priced at $1,000,000 or more don’t qualify. If you’re curious about the trade-offs, we wrote about the risks of skipping the appraisal.

When there is an appraisal, you get to see it. Federal rules under the Equal Credit Opportunity Act require the lender to give you a copy promptly, or three business days before closing if that comes first. You can waive that timing, but think twice before you do.

Buying a Home? Read the Appraisal Before You Close

Buyers often skim the appraisal for one number and move on. Instead, read the whole thing. Check the square footage, the bedroom and bathroom count, and the condition notes. Then look at the comparable sales and ask whether they really match your block.

If the value comes in below the contract price, you have a few paths. You can ask the seller to lower the price, cover the gap in cash, or lean on an appraisal contingency if your contract has one. Your agent or attorney can tell you how many days you have and what the contract allows.

You can also challenge the number. On Fannie Mae loans, a buyer can request one reconsideration of value per appraisal, through the lender, with up to five alternative comparable sales. It has to happen before closing. So gather your sales early, and pick ones that are recent, close by, and similar in size.

Paying cash? No lender means no required appraisal. Still, a cash buyer has the most to lose from overpaying, and an online estimate won’t catch a failing roof. Our piece on Zestimates versus appraisals explains why the two numbers drift apart.

Dropping PMI Before It Ends on Its Own

If you put down less than 20 percent on a conventional loan, you’re probably paying private mortgage insurance. According to the Consumer Financial Protection Bureau, you can ask your servicer to cancel it once your balance reaches 80 percent of the home’s original value. The servicer can ask for evidence, such as an appraisal, that the value hasn’t dropped below that original figure.

PMI also ends automatically at 78 percent of original value if you’re current on payments. Your servicer, or investors like Fannie Mae and Freddie Mac, may allow earlier removal under their own guidelines. Before you pay for a report, call your servicer and ask which appraisers and report types they accept. If they’ll take an independent report, PMI removal is one of the residential assignments we handle across Chicago.

Inheriting, Settling an Estate, or Gifting a Home

This is where a lot of families get caught. When you inherit a house, IRS Publication 551 says your basis is generally its fair market value on the date of death. An alternate valuation date can apply if the estate’s representative elects it. That basis affects the tax when you sell, so a documented value matters even if you plan to sell quickly.

The appraisal in that case looks backward. It values the home as of the date of death, sometimes months or years later. Our guides on appraisals for inherited property and the date-of-death appraisal walk through how that works.

Gifts follow different basis rules, tied to what the giver paid. A donation to charity brings its own qualified appraisal requirements. Either way, your CPA should weigh in on the tax side before the deed changes hands.

Divorce, Buyouts, and Splitting a Home

When a marriage ends and one spouse keeps the house, the buyout number usually starts with an appraisal. The attorneys or the court set the valuation date, and the appraiser values the home as of that date. If both sides hire their own appraisers, the reports often differ, and the gap becomes part of the negotiation. Once you have a value, our marital home buyout calculator gives a rough sense of the payment after the mortgage and other liens.

The same logic applies when siblings split an inherited home or co-owners part ways. One person keeps the property, and everyone needs a value they can trust. We cover this in more depth in appraisals in divorce proceedings and our article on marital home buyouts.

Appealing a Property Tax Assessment

If your assessment notice looks high, you can appeal. In Cook County, the Board of Review hears appeals from owners who believe their property is over-valued. An appraisal is one of the stronger pieces of evidence you can bring, especially when your home differs from what the assessor’s model assumed. Our Cook County Board of Review guide covers timing and what the Board looks at.

Selling Without Guessing

Nobody requires a seller to get an appraisal. But a pre-listing appraisal can keep you from pricing too high and sitting, or too low and leaving money behind. It also gives you a head start if the buyer’s appraisal comes in short. Here’s how appraisers help sellers price a home.

Start With Why You Need the Number

The reason drives everything else. A lender’s appraisal answers the lender’s question, at the date of inspection. An estate, a divorce, or a tax appeal usually needs a different date and a report written for that purpose. So before you order anything, know who will read the report and what date the value has to match. Then ask the appraiser to build the assignment around that.

Not Sure Which Appraisal Fits Your Situation?

Tell us what happened, whether it’s an inheritance, a buyout, PMI, or a tax notice, and we’ll scope the right report and the right date of value.

Tell Us What You Need

Frequently Asked Questions

Do I need an appraisal if I’m paying cash for a home?

No lender means no required appraisal. Many cash buyers still order one because they carry all the risk if they overpay, and an independent appraiser looks at condition and local sales that online estimates miss.

Can I get a copy of my lender’s appraisal?

Yes. For a first mortgage on a home, federal rules require the lender to give you a copy promptly after it’s done, or three business days before closing if that comes first. You can waive the timing, but reading it early gives you time to spot errors.

What can I do if the home appraisal comes in low?

You can renegotiate the price, cover the difference, or use an appraisal contingency if your contract has one. On Fannie Mae loans, you can also request one reconsideration of value per appraisal through your lender before closing, with up to five alternative comparable sales.

Can I reuse my mortgage appraisal for an estate or divorce?

Usually not. A mortgage appraisal answers the lender’s question as of the inspection date. Estates and divorces typically need a value as of a different date, in a report written for that purpose, so a new appraisal is the safer route.

Do I need an appraisal to remove PMI?

Often, if you ask to cancel it early. The CFPB says you can request cancellation once your balance reaches 80 percent of the original value, and the servicer can ask for evidence, such as an appraisal, that the value hasn’t dropped. Check with your servicer before ordering one.

About PahRoo Appraisal & Consultancy

Whatever brought you here, an inheritance, a buyout, or a tax bill, PahRoo starts by pinning down the purpose and the date of value, then builds the report around them. We’re headquartered in Lincolnwood and also serve Dallas, Philadelphia, Phoenix, and Naples, with residential, commercial, litigation support, and property tax appeal work. See our Chicago real estate appraisal services or learn more about our team.

Renovated Chicago home kitchen listed for sale with unpermitted work
How to Sell a House With Unpermitted Work in Chicago

I was appraising a home in Bucktown last month. Beautiful renovation: open kitchen, custom cabinetry, new bathrooms, updated electrical. None of it had ever been permitted. So can you sell a house with unpermitted work? Yes, but not at the price her broker had assumed, and not to every buyer.

When unpermitted work surfaces during an appraisal, four things happen at once. The appraiser must disclose it. The lender’s underwriting shifts. The buyer pool narrows. And the seller lands in a conversation nobody planned for. Here is how each plays out, and what to do before the appraisal is ordered.

By the end of this article, you’ll know:

  • How appraisers and lenders are required to treat unpermitted renovations
  • How Chicago’s retroactive permit process works, and what it costs in time
  • Three pricing strategies for listing a home with unpermitted work

What Happens When You Sell a House With Unpermitted Work

The appraiser cannot look away. Under USPAP and the Fannie Mae Selling Guide B4-1.3-05, an appraiser who identifies unpermitted additions or improvements must comment on the quality and appearance of the work. Then they must assess its effect, if any, on market value.

That analysis turns on three questions. Was the work done in a workmanlike manner, with sound structure and materials that match the neighborhood? Would a typical buyer in this market accept it, or treat it as a negotiating problem? And if the work had to be permitted retroactively or removed, what would that cost?

Unpermitted work is not automatically excluded from value. A skilled renovation, typical of the market, may contribute close to its full worth. A poorly executed one may contribute very little. But either way, it gets analyzed and disclosed. Our residential appraisers see this in Chicago constantly, and the sellers who fare best are the ones who knew before the report landed.

How Different Lenders React to Unpermitted Work

Financing programs do not treat unpermitted work the same way, and this is where the buyer pool starts shrinking.

Fannie Mae and Freddie Mac will generally finance a property with unpermitted work once the appraiser has addressed quality and market impact. The space can even count toward gross living area if it is workmanlike and typical for the market. Individual lenders may layer on stricter overlays.

FHA is tougher. The property must meet the Minimum Property Requirements in HUD Handbook 4000.1. Significant unpermitted work can push the appraisal to “subject to” status, meaning the loan cannot close until the work is permitted or corrected. VA loans follow a similar pattern under their own property requirements.

Cash buyers face no lender rules at all. They simply use the unpermitted status to negotiate the price down. So a home with substantial unpermitted work often ends up competing for cash buyers and flexible conventional borrowers, while government-insured buyers drop out entirely.

The Chicago Retroactive Permit Process

For many sellers, permitting the work after the fact is the cleanest fix. The Chicago Department of Buildings handles it in a recognizable sequence: application, plan submission, plan review, inspection, correction of any deficiencies, then permit issuance.

The plans are usually the first surprise. Electrical, plumbing, and structural work typically require professional drawings of what was already built, which means architect or engineer fees before the city sees anything. The second surprise is the inspection. The completed work must meet current code, so older wiring, unvented plumbing, and unsupported structural changes all trigger correction orders before the permit issues.

Plan for roughly two to four months on a typical residential project, longer when corrections stack up. Costs run from a few thousand dollars for simple work to far more when code fixes are required. Chicago also charges more for work started without a permit, and fines can apply on top. Worse, if the city discovers the work before the seller addresses it, a stop-work order can freeze everything mid-transaction.

Three Ways to Price a Home With Unpermitted Work

Brokers have three workable strategies, and each trades money for time in a different direction.

The first is pricing at unpermitted market value. List at what the property is worth given its actual permit status. This attracts cash and flexible conventional buyers immediately. It is the fastest path to closing and the lowest number.

The second is permitting before listing. The seller completes retroactive permitting first, then lists a fully documented property to the entire buyer pool at full market value. It usually produces the best financial outcome, if the seller can absorb the months of delay and the upfront cost.

The third is disclosing and negotiating. List near full market value with the unpermitted status clearly disclosed, then handle it through price reductions or credits during the deal. This approach is common. It also produces the most extended escrows and the most collapsed contracts, because the buyer’s lender gets a vote.

Ask About Permits Before the Listing Agreement Is Signed

The intake walkthrough is where this problem should surface, not the appraisal. Ask every seller: What has been renovated since you bought the home? Which projects had permits pulled, and do you have the final inspection approvals? Was anything done by a prior owner? Has the electrical panel been upgraded, plumbing rerouted, or rooms reconfigured?

If the answers point to unpermitted work, the broker can recommend retroactive permitting, adjust the pricing strategy, or walk away from the listing. The one option that fails is assuming the appraisal will not catch it. A pre-listing appraisal answers the value question before a lender’s appraiser answers it for you, and it gives the seller real numbers to choose a strategy with.

Listing a Home With Unpermitted Work?

A pre-listing appraisal from PahRoo tells you what the property is worth as it stands, and what permitting would change, before a buyer’s lender decides for you.

Get a Pre-Listing Appraisal

Frequently Asked Questions

Can you sell a house with unpermitted work in Chicago?

Yes. Unpermitted work does not block a sale, but it must be disclosed, the appraiser must analyze it, and some financing programs will not close until it is permitted or corrected. The practical effect is a smaller buyer pool and pricing pressure.

Does unpermitted work count in the appraised value?

Sometimes. Fannie Mae guidance lets appraisers give value to unpermitted improvements that are workmanlike and typical for the market. Poor-quality work may contribute little or nothing. The appraiser must comment on the work and its market impact either way.

Will FHA finance a home with unpermitted renovations?

Only if the property still meets FHA Minimum Property Requirements under HUD Handbook 4000.1. Significant unpermitted work often makes the appraisal “subject to” repairs or permits, which delays or blocks closing until resolved.

How long does a retroactive permit take in Chicago?

Plan for roughly two to four months on a typical residential project. The timeline covers application, professional drawings, city plan review, inspection, and any code corrections. Complex projects or required repairs extend it.

Should a seller permit the work before listing or just disclose it?

Permitting first usually brings the best price because the full buyer pool returns. Disclosing and negotiating is faster to market but tends to mean longer escrows and lender complications. A pre-listing appraisal quantifies the gap so the seller can decide with real numbers.

Know the Number Before the Buyer’s Lender Does

PahRoo Appraisal & Consultancy provides pre-listing, lending, and litigation-ready real estate appraisal services across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Our team appraises renovated and Chicago-area homes with unpermitted improvements every week. Questions about a specific property? Contact our team or call 773-388-0003.


As-is appraisal of an older home with deferred maintenance before a pre-foreclosure sale.
As-Is Appraisal: What It Means in Pre-Foreclosure

An as-is appraisal is an opinion of value based on your property exactly as it stands today, deferred repairs and all. No promises about work you might do later. Just the house as it sits on the effective date. For a homeowner facing pre-foreclosure, that single number often carries more weight than any other document in the file.

By the end of this article, you’ll know:

  • What an as-is appraisal measures, and how it differs from a subject-to value
  • Why homes in pre-foreclosure are almost always valued as-is
  • How to put that number to work with your lender, attorney, or agent

What an as-is appraisal actually values

An as-is appraisal answers one question. What is this property worth right now, in its current condition? The appraiser inspects the home, rates its condition, and researches recent sales of similar properties. Peeling paint, a dated kitchen, a roof near the end of its life: all of it stays in the picture. Nothing gets erased or assumed away.

That matters because most other valuations quietly assume a cleaned-up house. A lender’s automated estimate does not see your water-stained ceiling. An agent’s list price often bakes in repairs you have not made. An as-is number does not flatter the property. It reflects what a buyer would actually pay for it today, which is exactly why the figure is useful when the stakes are high. Our real estate appraisal services page walks through how we build these reports.

As-is vs. subject-to: two different numbers

The counterpart to as-is is a subject-to appraisal. A subject-to value assumes certain repairs or improvements get finished. Think of it as the “after” value once the work is done.

Appraisers rely on two tools here, both defined by the Uniform Standards of Professional Appraisal Practice. An extraordinary assumption treats something uncertain as if it were true, like assuming a furnace works when we could not test it. A hypothetical condition values the home as if something false were real, like a finished basement that is still framed studs. The Appraisal Institute guide notes spell out how each one gets disclosed.

So one property can support two very different values. As-is reflects today. Subject-to reflects a future that may or may not happen. In a pre-foreclosure sale, the as-is figure is usually the honest one, because those repairs are not going to get done first.

Where FHA fits, and where it does not

FHA loans add a wrinkle. When a buyer uses FHA financing, the appraisal has to confirm the home meets HUD’s Minimum Property Requirements, which is HUD’s way of saying safe, sound, and secure. If the property clears that bar with only minor wear, the appraiser can report it as-is.

When there is a real health or safety problem, the rules change. A broken window, exposed wiring, or a failing furnace usually forces a subject-to appraisal, meaning the value assumes those items get repaired first. The HUD Handbook 4000.1 lays out these requirements, and the lender, not the appraiser, decides which repairs are mandatory.

One point causes confusion. A client cannot simply instruct an appraiser to ignore FHA repair items on a financed purchase. So if you are selling to an FHA buyer, plan for those repairs to surface. If the sale is a cash or conventional deal, an as-is report is often the right fit.

Why pre-foreclosure homes get appraised as-is

Homes heading toward foreclosure tend to share a pattern. Money got tight, so maintenance slipped. The furnace limped along and the roof went another season. By the time the property needs a value, it rarely shows well.

That creates a real challenge for the appraiser. The cleanest comparable sales are often homes in better shape. So we adjust. We look at the cost to cure each deficiency, then we test how the market actually reacts to that condition, and we bring the comparable values down to match the subject. Buyers discount a tired house by more than the raw repair bill, and a credible report captures that.

The result is a defensible as-is value: the price a real buyer would pay, supported by real sales. That kind of report holds up when a lender, a judge, or an opposing party pushes back. Our team handles foreclosure and distressed-property appraisals with that scrutiny in mind.

How to put an as-is value to work

An appraisal will not stop a foreclosure. What it does is give you an accurate number to make decisions around, and something solid to hand the people who can help.

A few common uses. In a short sale, an independent as-is value helps you and your agent price the home so the lender approves it. A low, well-supported figure can also back your case when you ask the bank to accept less than the balance owed. In a loan modification or deed-in-lieu, it shows the servicer what the collateral is really worth. And if the bank’s own valuation came in oddly high or low, a full appraisal gives you grounds to push back.

Foreclosure decisions are legal and financial ones, so loop in a HUD-approved housing counselor or an attorney early. Our job is the value. We give you a clear, USPAP-compliant number you can stand behind, whatever path you choose. If you are weighing your options, start by finding out what your home is truly worth today.

Not sure what your home is really worth right now?

Whether you are pricing a short sale, answering a lender, or just weighing your options, an independent as-is appraisal gives you solid ground to stand on.

Get Your As-Is Value

Frequently Asked Questions

What does an as-is appraisal mean?

An as-is appraisal is an opinion of value based on the property’s current condition, with no assumption that repairs or upgrades will be made. It reflects what a buyer would pay for the home exactly as it stands on the inspection date.

Is an as-is value lower than a repaired value?

Usually, yes. If a home needs work, its as-is value sits below its subject-to (repaired) value. The gap reflects both the cost to cure the problems and how much buyers discount a property in that condition.

Can I get an as-is appraisal if I am behind on my mortgage?

Yes. Homeowners in pre-foreclosure, short sales, and loan workouts often order an independent as-is appraisal. It gives you and your advisors an accurate value to negotiate around. An appraisal does not stop foreclosure, but it supports better decisions.

Does an FHA appraisal have to be subject-to repairs?

Only when the property fails to meet HUD’s Minimum Property Requirements for health and safety. If the home is safe, sound, and secure with only minor wear, an FHA appraisal can be completed as-is. The lender decides which repairs are required.

Who uses an as-is appraisal in a distressed sale?

Homeowners, real estate agents, lenders, and attorneys all rely on it. It helps set a short-sale price, respond to a servicer’s valuation, or support a loan modification or deed-in-lieu request.

Know Your Home’s Value Before You Decide

PahRoo Appraisal & Consultancy is a Chicago-based firm on the FHA appraiser roster, with more than two decades valuing homes across Cook County and beyond. We handle foreclosure and short-sale appraisals, divorce and estate work, and everyday residential valuations with the same care. When the number has to hold up, we are ready to stand behind it. Have questions first? Get in touch.


Modest single-family suburban home with gray siding and a small covered entry, used to illustrate valuing a marital home in a divorce.
The Date of Value Problem: Why Timing Changes What the Marital Home Is Worth

Two appraisers can look at the same marital home and reach different numbers, both correct. The reason is usually the date of value. Set it on one day and the house is worth one figure. Set it on another, and the number moves. In a divorce, that single choice can shift a settlement by thousands, which is why the date of value in a divorce appraisal deserves attention early, not after the report lands.

By the end of this article, you’ll know:

  • What the date of value is and why it changes the number
  • Which date Illinois courts generally use for the marital home
  • When a retrospective appraisal is the right tool

What the Date of Value Means in a Divorce Appraisal

The date of value, also called the effective date, is the exact day an appraiser’s opinion of value applies to. It is not always the day the appraiser visits the home. The appraiser can measure market value as of today, or as of a date in the past, and the report states which one it used.

This matters because markets move. Interest rates shift, inventory tightens, a neighborhood heats up or cools off. So a home worth one figure in the spring may carry a different figure by the fall. The Uniform Standards of Professional Appraisal Practice treat the effective date as a core part of the assignment, and a credible report ties every comparable sale back to it.

Which Date Illinois Courts Use

Illinois gives the court discretion here, but there is a strong default. Under 750 ILCS 5/503, marital property is generally valued as of the date of trial, or the date the marriage is dissolved, using a fair market value standard. The court can pick another date if the parties agree or if the facts call for it.

One rule trips people up. The separation date is usually not the valuation date. Value tends to keep accruing until the case is decided, so growth in the home’s worth between separation and trial often stays in the marital estate. Courts also avoid using different dates for different assets, which keeps the division consistent.

When a Retrospective Appraisal Comes In

Sometimes the question is not what the home is worth now, but what it was worth years ago. That is a retrospective appraisal. The appraiser sets a past effective date, such as the date of marriage, and reconstructs the market using sales that closed around that time.

This is often how a spouse traces separate property. If one party owned the home before the marriage, the value at the date of marriage helps separate premarital equity from the appreciation that built up during it. CPAs lean on the same figure to keep the tax and division math straight. So the choice of date is not a technicality. It decides what counts as marital in the first place.

How the Date Moves the Number

Picture a home that a couple bought near a market peak, then watched cool as rates climbed. An appraisal dated at filing might land higher than one dated at trial a year later. Neither is wrong. They answer different questions.

That gap is exactly why the effective date can become a bargaining point. A spouse hoping for a lower buyout may prefer a softer date, while the other pushes for the stronger one. The appraiser does not pick sides. But the attorney who sets the date early controls the terms of the fight instead of reacting to a number that already exists.

Set the Date Before You Order the Appraisal

Decide the effective date first, then order the work to match. If the case may need both a current value and a past one, say so up front, because a retrospective analysis takes different data. Confirm the appraiser can support the chosen date with real sales from that period, and can explain the choice if the report is challenged. Timing is a decision, so make it on purpose.

Need the Value Fixed to the Right Date?

PahRoo prepares both current and retrospective divorce appraisals, tied to the effective date your case needs and ready to defend.

Ask About a Date-of-Value Appraisal

Frequently Asked Questions

What is the date of value in a divorce appraisal?

The date of value, also called the effective date, is the specific day an appraiser’s opinion of value applies to. It fixes the moment the home’s market value is measured. Two appraisals of the same house with different effective dates can reach different numbers, because the market moves over time.

Does a home get appraised at the date of separation or the date of trial?

In Illinois, marital property is generally valued as of the date of trial or the date the marriage is dissolved, not the date of separation. Under 750 ILCS 5/503, the court has discretion to use the trial date or another date the parties agree to, so the separation date is usually not the valuation date.

What is a retrospective appraisal?

A retrospective appraisal estimates what a property was worth on a specific past date, such as the date of marriage. The appraiser reconstructs the market as of that date using sales that closed around then. It is common when tracing how much of a home’s value is separate versus marital property.

Can the chosen date change the settlement?

Yes. Because home values shift over time, the effective date can change the appraised value, and that changes the equity each spouse divides. In a fast-moving market, the gap between two candidate dates can be large enough to matter in a negotiation.

Can you appraise a home for a past date?

Yes. A licensed appraiser can prepare a retrospective appraisal with a past effective date, relying on comparable sales from that period rather than today’s market. The report states the effective date clearly, so everyone knows what point in time the value reflects.

Need an Independent Divorce Appraisal?

PahRoo Appraisal & Consultancy prepares current and retrospective valuations across Cook County and the wider Chicago area. For background on how we support attorneys and their clients, see our overview of appraisals in divorce proceedings and our residential appraisal services, or contact us to set the right effective date for your case.

Vintage home appraisal story about a 1901 Chicago brick house with a bedroom and no closet.
Vintage Home Appraisal: The Bedroom With No Closet

One of our residential appraisers recently stood in a Chicago bedroom built in 1901 and noticed something missing. There was no closet. On a modern checklist, that looks like a problem. In a vintage home appraisal, it tells a story about how people actually lived.

By the end of this article, you’ll know:

  • Why homes built before the 1920s often have bedrooms without closets
  • Whether a room needs a closet to count as a bedroom
  • How market support saved a three-bedroom count after a renovation removed a closet

What a Vintage Home Appraisal Sees That a Checklist Misses

Plenty of people believe a room without a closet cannot be a bedroom. It is one of the most persistent myths in residential real estate. In fact, Fannie Mae’s appraisal guidance contains no closet requirement. A bedroom needs adequate size, ceiling height, privacy, heat, and a window or door for emergency egress. The closet rule comes from habit, not from the standards appraisers follow.

Still, habit shapes markets. Buyers expect closets, agents list rooms based on them, and an appraiser who treats every house like new construction will mark a closet-free room down without a second thought. That is where experience earns its fee. Our residential appraisal work across Chicago’s older housing stock means we read a 1901 floor plan on its own terms, then test that reading against real market evidence.

Why Homes Built in 1901 Rarely Have Bedroom Closets

In 1901, families did not organize their lives around hanging rods. Most clothing lived in wardrobes and large cedar trunks, often one trunk per person, parked at the foot of the bed. Some homes went a step further and built a single oversized cedar closet for the whole household. Individual bedrooms stayed small and simple, sized for a bed and a trunk and little else.

Chicago’s early twentieth century housing boom produced tens of thousands of these homes. The Chicago History Museum documents how bungalows and workers’ cottages filled the city’s neighborhoods as the population surged. Organizations like the Chicago Bungalow Association now work to preserve these layouts as a signature of the era. So when you walk into a vintage bedroom and find no closet, you are not looking at a defect. You are looking at 1901.

The Bathroom Addition That Nearly Erased a Bedroom

Now the story. The subject property was a three-bedroom home, built in 1901, with one and a half bathrooms. In 2025, the owners added a second full bathroom. Smart move on paper, because bathrooms carry real value in older housing stock. But the new bathroom took its space from a bedroom closet, which was removed entirely.

Here is the trap. Judged purely by modern convention, the home now reads as two bedrooms plus an office. That single reclassification can shift the comparable pool, the marketing story, and the final value. A renovation meant to add value would have quietly subtracted a bedroom instead. The owners had no idea. Most owners never do, because nobody warns them that a closet can carry that much weight on a report.

How Market Support Kept the Third Bedroom on the Report

Our appraiser did not simply declare the room a bedroom and move on. Sympathy is not a valuation method. Instead, she built the case. The home’s 1901 construction date placed it firmly in Chicago’s vintage stock, where closet-free bedrooms are a documented, common layout. Comparable vintage homes in the market sell as three-bedroom houses with the same configuration, and buyers in this segment accept the trade.

That is market support: a conclusion backed by evidence of how actual buyers and sellers behave, not by personal opinion. With the era established and the comparables in hand, the report could credibly carry the home as a three-bedroom. The bedroom count survived, the new bathroom added its value, and the renovation did what the owners intended. The difference between those two outcomes was never the house. It was the appraiser’s knowledge of what 1901 means.

What Owners of Older Chicago Homes Should Do Before an Appraisal

First, learn your home’s era before you remodel it. A change that seems harmless, like absorbing a closet into a new bathroom, can alter how a room is classified. Second, keep records of what your home originally looked like, because floor plans and old listing photos help an appraiser reconstruct the vintage layout. Third, and most important, choose an appraiser who knows your housing stock. A checklist can count rooms. Only experience can explain them. If your home was built before the 1920s, ask directly how the appraiser handles vintage layouts. The answer will tell you a lot.

Own a Vintage Home? Get an Appraiser Who Can Read Its Era

A 1901 floor plan deserves more than a modern checklist. PahRoo’s appraisers know Chicago’s vintage housing stock and back every conclusion with market evidence.

Request Your Appraisal Quote

Frequently Asked Questions

Does a bedroom need a closet to count in an appraisal?

No. Fannie Mae guidelines and the International Residential Code do not require a closet. A bedroom needs adequate size, ceiling height, a heat source, privacy, and a window or door for emergency egress. The closet rule is a common myth.

Why do older homes have bedrooms without closets?

Before the 1920s, most families stored clothing in wardrobes and cedar trunks rather than built-in closets. Many vintage Chicago homes also used one large shared cedar closet instead of individual bedroom closets. The layout reflects how people lived at the time.

Can a renovation lower my home’s appraised value?

It can. A renovation that removes a feature buyers expect, such as a bedroom closet, may change how a room is classified. Before you remodel an older home, consider what the change does to room count and functional utility, not just the new feature you gain.

What does market support mean in an appraisal?

Market support means the appraiser backs a conclusion with evidence from actual sales. If comparable vintage homes with closet-free bedrooms sell as three-bedroom houses, the market treats those rooms as bedrooms. The appraiser can then classify the subject home the same way.

Should I add closets to my vintage home before an appraisal?

Not automatically. In many vintage markets, buyers accept period layouts, and forcing modern closets into small rooms can hurt function. Talk with an appraiser who knows your local vintage housing stock before spending money on changes.

Need an Independent Appraisal?

PahRoo Appraisal & Consultancy has appraised Chicago’s housing stock for decades, from 1901 workers’ cottages to new construction. Whether you need a residential appraisal, an independent valuation for divorce proceedings, or simply a straight answer about what your vintage home is worth, our team is ready. Learn more about PahRoo or contact us today.


Divorce home appraisal of a marital home, with keys and a property settlement document.
Why a Divorce Home Appraisal Is Not the Same as a Realtor’s Price Opinion

When a marriage ends, the house is usually the largest asset on the table. Both spouses want a number they can trust, and many start by asking a real estate agent what the home would list for. That figure has a job to do. A divorce home appraisal does a different job, and courts treat the two very differently.

By the end of this article, you’ll know:

  • What separates a divorce home appraisal from a broker price opinion
  • Why courts want an independent, standards-based value
  • When your situation actually calls for a formal appraisal

What a Divorce Home Appraisal Actually Measures

A divorce home appraisal is an independent opinion of a property’s market value, prepared by a licensed or certified appraiser. The appraiser inspects the home, studies comparable sales, and documents how each conclusion was reached. The report follows the Uniform Standards of Professional Appraisal Practice, or USPAP, the recognized rulebook for appraisers in the United States.

The point of the report is defensibility. A judge, an opposing attorney, or a spouse can question the number, and the appraiser has to stand behind it. So the work is built for scrutiny, not for a quick answer. PahRoo prepares these reports as part of its residential appraisal services, with the divorce context in mind from the first phone call.

Where a Broker Price Opinion Fits, and Where It Falls Short

A broker price opinion, or BPO, is an agent’s estimate of what a home could sell for. A comparative market analysis, the close cousin most sellers see, does much the same thing. Both are useful tools. Agents produce them quickly, often at no charge, to help set a listing price or win the listing.

The catch is the purpose behind the number. A pricing tool is built to move a house, so it leans toward what will attract buyers or reassure the seller. It also skips the formal standards an appraisal must follow. A trusted agent’s read on the market has real value early in a case. It just was not built to survive an opposing expert or a skeptical judge. So if you rest a contested value on a listing estimate, you hand the other side an easy target.

Appraisal vs. Broker Price Opinion at a Glance

  Divorce Home Appraisal Broker Price Opinion
Prepared by Licensed or certified appraiser Real estate agent or broker
Built for A defensible opinion of market value Setting or winning a listing
Follows USPAP Yes No
Holds up in court Designed to, and the appraiser can testify Easy for opposing counsel to challenge
Cost and speed Fee-based, takes longer to produce Often free and fast
Best use in divorce Contested value, buyout, refinance, trial Early ballpark when both sides agree

Why Courts Lean on the Appraisal

Illinois divides marital property by equitable distribution. Under 750 ILCS 5/503, the court splits property in “just proportions,” which does not always mean a straight 50/50 cut. The statute also directs judges to make specific findings on the value of each asset.

A court cannot make those findings on a guess. It needs a value that was developed under recognized methods and can survive cross-examination. An appraisal is designed to do that. A price opinion, however helpful for listing, was never meant to carry that weight.

When Your Case Actually Needs One

Not every separation calls for a formal appraisal. If both spouses agree on the value and plan to sell, an agent’s pricing may be enough to get moving. The appraisal earns its cost when the number is contested or the stakes are high.

The most common trigger is a buyout, where one spouse keeps the home and pays the other for their share. You also want a defensible value when the parties disagree on price, when a lender requires it for a refinance, or when the case is heading toward trial. In each of those, a soft number invites a challenge down the road.

Start With a Value That Holds Up

If the house sits at the center of your settlement, begin with a number built to withstand pressure. An independent appraisal costs more than a quick estimate and takes longer to produce. It also removes a common source of delay, because neither side can easily wave it away. Ask early whether your situation needs one, then order it from an appraiser who will explain and defend the work.

Need a Value Both Sides Can Trust?

PahRoo prepares court-ready, USPAP-compliant appraisals for divorcing homeowners and their attorneys. Get one number that stands up to scrutiny.

Request Your Appraisal

Frequently Asked Questions

What is a divorce home appraisal?

A divorce home appraisal is an independent, USPAP-compliant opinion of a marital home’s market value, prepared by a licensed or certified appraiser to support property division. It documents the comparable sales and reasoning behind the value, so it can hold up if a spouse, attorney, or judge questions it.

Is a realtor’s price opinion accepted in a divorce?

A realtor’s price opinion can inform early discussions, but courts generally prefer a formal appraisal when the value is contested. A price opinion is built to set a listing price, not to meet appraisal standards, so it is easier to challenge in a property division dispute.

Who should appraise a house in a divorce?

A licensed or certified real estate appraiser should value the home, ideally one experienced with divorce work and willing to testify if needed. Some couples save time and money by jointly retaining one neutral appraiser instead of each hiring their own.

How much does a divorce home appraisal cost?

The cost depends on the property type, its complexity, and whether court testimony may be required. A standard single-family home runs less than a luxury or multi-unit property that needs deeper analysis. PahRoo quotes each assignment individually, so you can request an estimate for your specific home.

Can you use a Zillow estimate in a divorce?

A Zillow estimate is an automated model, not an appraisal, and it cannot account for a specific home’s condition or recent updates. Courts do not treat it as reliable evidence of value, so it should not anchor a settlement. An appraisal gives a defensible figure instead.

Need an Independent Divorce Appraisal?

PahRoo Appraisal & Consultancy has valued homes across Cook County and the wider Chicago area since 1999. Our team prepares reports for attorneys, homeowners, and other professionals who need a value that stands up. To learn more, read our overview of appraisals in divorce proceedings, or contact us to talk through your situation.

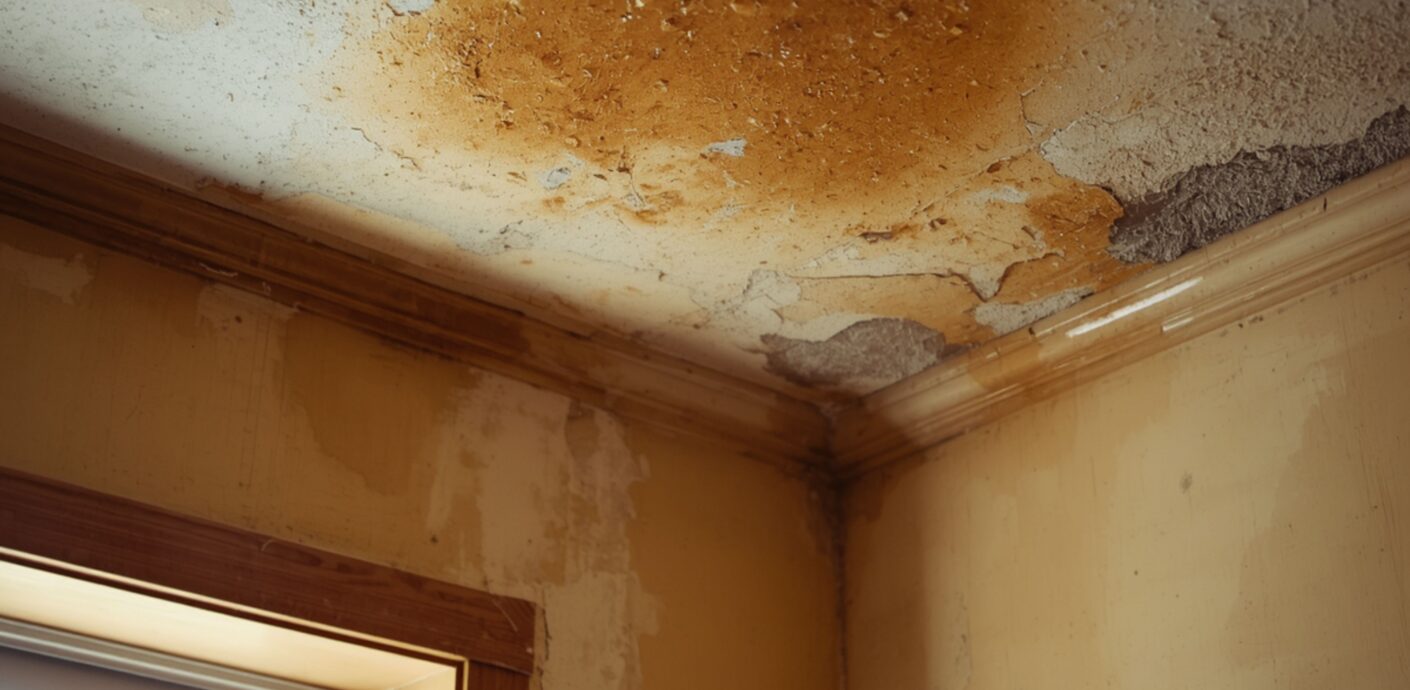
Water damage stains on a ceiling flagged during a home appraisal
Water Damage & Home Value: What Appraisers Flag

Water damage has a way of derailing a sale right when things feel like they are going smoothly. A faint ceiling stain might not worry you at all. An appraiser sees it differently, because that stain often hints at a bigger story. Knowing how water damage and home value connect, and what an appraiser flags before closing, puts you a step ahead. You get to handle problems on your own terms, not at the last minute.

By the end of this article, you’ll know:

  • The water-related conditions an appraiser looks for and writes up
  • Why a lender can stall your closing until water problems get fixed
  • What to repair and document before the appraisal happens
How Water Damage Affects Home Value

Most homeowners assume the hit to value equals the repair bill. It rarely works that cleanly. What worries a buyer, a lender, and an appraiser is what the water might have done out of sight. Water travels. A roof leak can rot the sheathing above a ceiling long before any stain shows up. Down in the basement, dampness might point to a grading or foundation issue. And a slow drip under a sink? That can feed mold behind the drywall for months before anyone notices.

That uncertainty is what moves the numbers. A home with visible water damage tends to draw lower offers, repair demands, or a longer stretch on the market. An appraiser’s job, after all, is to capture how the market reacts to what’s in front of it. So we note the visible conditions and weigh how they affect value and saleability.

What an Appraiser Will Notice

We are not home inspectors, and we do not go cutting into walls. But a trained appraiser spots the visible signs of a water problem fast during a standard residential appraisal. The usual flags:

  • Water stains on ceilings and walls
  • Standing water in a basement, crawlspace, or against the foundation
  • A musty smell that says moisture is still hanging around
  • Warped or swollen drywall, baseboards, and flooring
  • Roof leaks, or shingles that have clearly seen better days
  • Grading that sends rainwater toward the house instead of away from it

A lot of this matters because of what tends to follow water: mold. The EPA points out that mold needs ongoing moisture to grow. So a damp crawlspace, or a stain nobody can explain, earns more scrutiny than its size might suggest.

How Water Damage Can Hold Up Your Closing

Water damage can hold up the calendar, too. Lenders, especially on government-backed loans, hold a property to minimum condition standards.. Active water intrusion is one of the more common reasons an appraisal comes back “subject to repair.”

Once that happens, the lender usually wants it fixed and re-checked before the deal can close. Even a small repair can push your closing date back a week or two. Worse, when it only turns up at the appraisal, that lost time becomes the real cost for anyone working to a firm contract date.

Old Damage Reads Differently From Active Damage

Not every water stain carries the same weight. The question an appraiser really cares about is whether the source got fixed.

Picture a leak you repaired last spring. You replaced the ruined drywall and kept the receipts. In that case the worry mostly evaporates, because you can prove the problem is behind you. Now picture a fresh stain, a corner that’s still damp, and no paperwork. An appraiser has to treat that as a live issue, and so will the buyer.

What to Do Before the Appraiser Shows Up

A few moves keep a water issue from running your whole sale:

      1. Fix the source, first and always. Scrub a stain without stopping the water and it comes right back, usually at the worst possible moment.
      2. Keep the paperwork. Invoices, contractor notes, inspection reports. Good documentation answers the appraiser’s question before anyone asks it.
      3. Repair what shows. Swap out stained drywall, ceiling tiles, and warped trim, so nobody is writing up damage you have already handled.
      4. Speak up early. If the house has had a real water event, tell your agent and your appraiser up front. Then everyone plans around the facts instead of a surprise.
Why It Pays to Get Ahead of It

Water damage does not have to wreck your value or your timeline. Most of the harm to a sale comes from the unknowns, like what’s behind the wall and whether it’s still wet. Clear those up and the whole conversation shifts in your favor.

So track down the source, fix it, write it all down, and patch the visible damage before you list. Do that, and a water stain stays a footnote in your sale rather than the headline at your closing.

Worried water could cost you at the closing table?

Find out where your home really stands before a lender or a buyer raises the question. PahRoo delivers independent, defensible appraisals that give you answers, not guesswork.

Request Your Appraisal

Frequently Asked Questions

Does water damage lower a home’s appraised value?

It can, though not on its own. The effect depends on how bad it is, whether you’ve fixed the source, and how nervous it makes buyers. Often the real drag on value is what the damage hints at, rather than the damage you can see.

What does an appraiser look for when checking for water damage?

Visible clues, mostly: stains, standing water, musty smells, warped materials, signs of a roof leak, and poor drainage. An appraiser reports what’s in plain sight and won’t go digging behind walls or running lab tests.

Will water damage stop a home loan from closing?

It can slow things down. A lender may insist that active water intrusion gets corrected and re-inspected first, particularly on government-backed loans with condition standards to meet.

Do I need to fix water damage before selling?

Usually yes, especially when it’s visible or a buyer needs financing. Sorting it out before you list keeps the negotiation calmer and lowers the odds of a delayed closing.

Is old, repaired water damage still a problem for an appraisal?

Much less of one, as long as you fixed the source and have the records to show it. Repaired and documented damage sits in a very different category from something fresh or unexplained.

Need an Independent Appraisal?

Sometimes water damage, repairs, or condition questions cloud what a home is really worth. In those moments, an independent appraisal gives you a credible, well-supported answer before you negotiate or finance.

PahRoo Appraisal & Consultancy, LLC helps homeowners, attorneys, accountants, bankers, and real estate professionals make confident decisions. Whether you’re preparing to sell, settling an estate, removing PMI, navigating a divorce, or weighing how a property’s condition affects value, our team is ready to help.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712