Category: Commercial Appraisals

Request a quote

Our blog

Latest news
& events

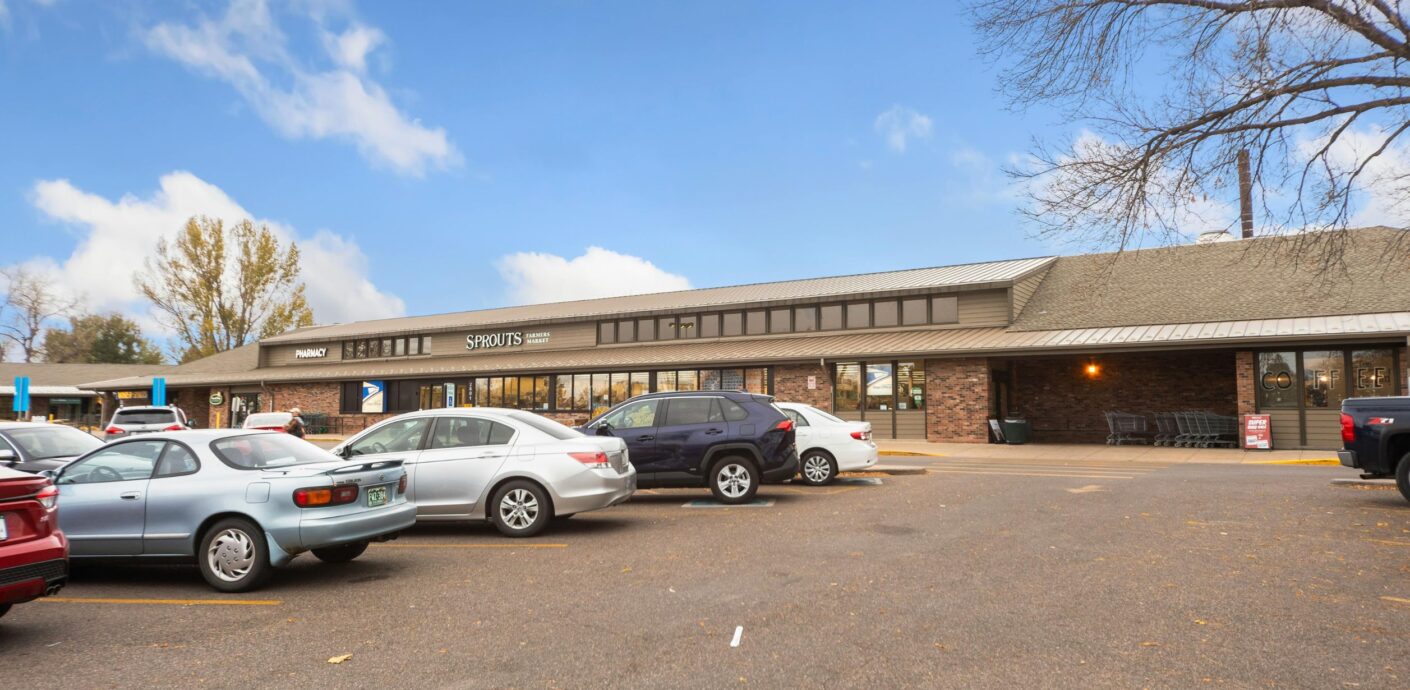
Partially leased retail strip center being appraised for a commercial refinance
What to Expect From a Commercial Refinance Appraisal

Thinking about refinancing a building you own? Before a lender sets the new loan amount, it needs a supported opinion of what the property is worth today. That is the job of the commercial refinance appraisal, and it shapes how much you can borrow, how much cash you can take out, and sometimes whether the deal works at all.

By the end of this article, you’ll know:

  • How the appraised value sets the size of a refinance loan
  • Who orders the appraisal, and when a new one may not be needed
  • What owners and lenders can do to keep the process moving

How a Commercial Refinance Appraisal Sets Your Loan Amount

Lenders look at two things in a refinance. First, can the property’s income cover the payment? Second, is the building worth enough to secure the loan? According to the Interagency Appraisal and Evaluation Guidelines, the ability to repay comes first. Still, a bank must also consider the value of the real estate behind the loan.

That value usually caps the loan through a loan-to-value limit in the lender’s policy. Consider a hypothetical. A lender caps the loan at 70 percent of value, and your building appraises at $3,000,000. The most it would lend is $2,100,000. If you still owe $2,300,000, you would need to bring $200,000 to closing or find another lender.

So a few percent in value can move real money. That’s why it helps to understand what goes into the number before the appraiser shows up.

Your Lender Orders the Appraisal, Not You

This part surprises a lot of owners. The bank picks and engages the appraiser, and federal guidance says it can’t use a report the borrower ordered. Our article on commercial appraisals for lending covers those independence rules in detail.

For a refinance, the practical point is simple. An appraisal you order yourself can help you decide whether refinancing makes sense before you talk to lenders. It just won’t stand in for the appraisal the bank orders for the loan.

When a Refinance May Not Need a New Appraisal

Some refinances skip the full appraisal. Under the OCC’s appraisal rule at 12 CFR 34.43, an existing loan at the same bank can be refinanced without one in either of two cases. In the first, no new money goes out beyond reasonable closing costs. In the second, nothing obvious and material has changed in the market or the property that threatens the bank’s collateral.

The same rule exempts commercial real estate deals of $500,000 or less. In both cases, though, the bank still needs an evaluation, which is a simpler written estimate of market value. A bank can also order a full appraisal anyway, and the guidelines point that way for higher risk loans.

Two more points matter here. Moving the loan to a new lender takes it outside the existing loan exemption, since that exemption only covers credit already at the lending bank. And a cash-out refinance adds new money, so it qualifies only if the market and the property haven’t materially changed. The FDIC and the Federal Reserve have parallel rules for the banks they supervise, and credit unions follow the NCUA’s version.

What Moves the Value of a Leased Building

For most income property, the appraiser leans hard on the income. Our guide to the income approach shows how rent turns into value. Our explainers on net operating income and cap rates cover the two numbers that drive it.

Leases count too. The federal guidelines require lending appraisals to analyze deductions and discounts for partially leased buildings and non-market lease terms. So a half-empty building, or a big tenant paying well under market rent, will show up in the number.

Time plays a part as well. The guidelines list factors that can make an older appraisal stale, including the passage of time, changes in financing terms, lack of maintenance, and shifts in cap rates and lease terms. In other words, what your building was worth at purchase may not be what a refinance lender sees today.

Who occupies the building matters too. If your own company fills the space, our piece on owner-occupied and investment property appraisals explains why the two get valued differently.

How Owners Can Prepare for the Appraisal

You can’t pick the appraiser, but you can make the work go smoother. Have a current rent roll, every lease with its amendments, recent operating statements, and a list of capital improvements ready before the inspection. Our lending article above has a fuller checklist.

A refinance adds one more step. Find your last appraisal and write down what has changed since. A new roof, a lease renewal at a higher rent, or a tenant who moved out are exactly the facts that decide whether the old value still holds. So hand them to your lender early, before anyone has to ask.

One thing to leave out is a target value. The guidelines tell lenders not to give an appraiser a predetermined value, a loan amount, or a target loan-to-value ratio. For what happens next, see what goes into a commercial appraisal report and how long a commercial appraisal takes.

For Lenders, Set Up the Refinance Assignment Right

Bankers already know the ordering rules, and our lending article covers them. A refinance adds two decisions of its own.

First, decide whether the existing appraisal still holds. The guidelines let a bank use an existing appraisal for a later transaction. However, the credit file should show the facts and analysis behind that call, weighed against the staleness factors listed above. So document the check, even on a renewal with no new money that is exempt from a new appraisal.

Second, match the value premise to the new loan. If cash-out proceeds fund a renovation or a lease-up, the guidelines say a bank would generally ask for the as-is value. As applicable, it would also ask for a prospective value upon completion or stabilization.

If the building sits outside Cook County, our Dallas, Philadelphia, Phoenix, and Naples teams take commercial assignments in those markets. In Cook County, our Chicago appraisal team handles the work.

Planning a Refinance on a Building You Own?

Your lender orders the appraisal behind the loan. If you want a supported value first, to plan or before you talk to lenders, PahRoo can prepare one. Bankers can engage us for refinance assignments too.

Request a Commercial Appraisal Quote

Frequently Asked Questions

What is a commercial refinance appraisal?

It is an appraisal a lender uses to decide how much it will lend on a new loan secured by income-producing or business property. The appraised value usually caps the loan through the lender’s loan-to-value limit.

Can my bank reuse the appraisal from when I bought the building?

Sometimes. A bank can rely on an existing appraisal for a later loan if it documents why the value still holds. The passage of time, lease changes, or a shift in cap rates can make an older value stale.

Does every commercial refinance need a new appraisal?

No. For an existing loan at the same bank, federal rules may allow an evaluation instead when no new money goes out or when the market and property haven’t materially changed. The bank decides which it needs.

What should I have ready for a commercial refinance appraisal?

A current rent roll, every lease and amendment, recent operating statements, and a list of capital improvements. Plan for access to the whole building, including vacant space.

Does a cash-out refinance need a new appraisal?

Not always. At the same bank, a cash-out refinance can skip a new appraisal only if nothing obvious and material has changed in the market or the property. Otherwise it generally needs one, or an evaluation for smaller loans.

Refinance Appraisals That Hold Up in Credit Review

When a lender needs a value it can underwrite, PahRoo Appraisal & Consultancy prepares commercial appraisals for banks, investors, and owners in Chicago and Cook County, Dallas, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, signs our Illinois reports. See our commercial appraisal services for the property types we cover.
Business owner in the loading bay of the light industrial building her company occupies, the subject of an owner-occupied appraisal
Why Owner-Occupied and Investment Property Appraisals Differ

Two buildings sit side by side, same size, same age, same street. One is full of your own company. The other houses a tenant you have never met. An owner-occupied appraisal and an investment property appraisal can land on different numbers for these two buildings. The reason has less to do with the bricks than with the question the appraiser answers.

By the end of this article, you’ll know:

  • Why the appraiser uses market rent on a building you occupy and the actual leases on a building you rent out
  • How a below-market or above-market lease moves value, with a worked example
  • Why the value of your business stays out of the real estate number, and what lenders should tell the appraiser up front

What an Owner-Occupied Appraisal Actually Values

When you own the building and run your business in it, nobody is paying rent. So there is no lease for the appraiser to read. Instead, the appraiser asks a simpler question. What would this space rent for if it hit the open market tomorrow?

That figure is market rent. It comes from comparable leases on similar buildings nearby, adjusted for size, condition, and location. The appraiser then builds an income approach on that rent. Sales of similar buildings come in too, and sometimes a cost approach.

Here the appraiser usually values the fee simple interest. In plain terms, that means full ownership with no lease attached. Since no tenant holds any rights, the value rests on what the market would pay for the building itself. Our guide to the income approach for commercial property walks through how that rent becomes a value.

Investment Property Starts With the Leases

Once you rent a building to someone else, the leases become part of what you own. Now the appraiser reads them closely. The rent a tenant actually pays is contract rent. It may or may not match market rent.

If the leases run at market, the two numbers line up and the gap is small. But leases signed years ago often drift. A tenant paying well under market holds a bargain that the owner cannot take back until the lease ends. A tenant paying above market adds income, though only as long as that tenant can keep paying.

Federal appraisal rules for bank loans address this directly. Under 12 CFR 34.44(d), appraisals for federally related transactions must analyze deductions and discounts for non-market lease terms. Partially leased buildings get the same treatment. So the appraiser cannot just assume every lease is at market. Each one gets tested.

A Hypothetical Building, Valued Two Ways

Consider a hypothetical 20,000-square-foot light industrial building in a Chicago suburb. We invented every figure below for illustration.

First, assume the owner’s company occupies all of it. Comparable leases suggest market rent of $10 per square foot, net. That gives $200,000 a year in potential rent. Take out 5 percent for vacancy and collection loss, and you have $190,000. Then subtract $10,000 for costs a landlord would typically absorb, such as management and reserves. Net operating income comes to $180,000. At a 7.5 percent capitalization rate, the indicated value is $2,400,000.

Now change one fact. An unrelated tenant leases the same building at $8 per square foot. Six years remain on the lease. Contract rent is $160,000 a year. That is $40,000 a year below market, every year, until the lease ends.

The appraiser has to account for that shortfall. In this case, the leased fee value would likely come in under $2,400,000. How far under depends on the discount rate and the tenant’s credit. It also depends on the market when those six years run out. Flip the facts, with a strong tenant paying $12, and the leased version could come in higher.

The Owner’s Business Is Not the Building

Owner-users sometimes expect their company’s success to show up in the appraisal. After all, the building is where the money gets made. But a real estate appraisal values the real estate, and the business is a separate asset.

This matters most for restaurants, hotels, and car washes. In those, the operation and the building can feel like one thing. The Interagency Appraisal and Evaluation Guidelines address this. For federally related transactions, they bar using going concern value or value in use as market value. An appraisal can still report those values separately, as long as they are clearly identified.

In practice, the appraisal on your building will often come in below what the whole operation feels worth. That is by design. The SBA has its own rules on separating business value. Our article on SBA appraisal requirements covers them.

What Lenders Should Put in the Engagement

For bankers, occupancy changes more than the appraisal. It also shapes how you classify the loan. The 2006 interagency guidance on CRE concentrations excludes certain loans on owner-occupied buildings. The test is whether repayment comes mainly from the operations of the owner or its affiliate. It covers nonfarm nonresidential loans when 50 percent or more of repayment comes from third-party, nonaffiliated rental income. SBA uses a different test. For an existing building, 13 CFR 120.131 requires the borrower to occupy at least 51 percent. It may lease out the other 49 percent.

So a few lines in the engagement letter save a revision later. Tell the appraiser the current occupancy split, in square feet, between the borrower and outside tenants. State the interest you need valued, fee simple or leased fee. Does the borrower’s real estate LLC lease to its own operating company? Then send that lease too, and ask for a comparison to market rent. Related-party leases are often set for tax or convenience reasons, not market terms.

Finally, ask the appraiser to state a market rent figure even on a fully owner-occupied building. If the borrower’s business struggles, that number tells you what the space could earn from a tenant. Our overview of commercial appraisals for lending covers the rest of what credit reviewers check.

Plan for the Building You Might Own Next Year

If you occupy your building today, the value turns on market rent. Lease part of it out or plan a sale-leaseback, and the lease terms you sign will shape the appraisal for years. A lease set well below market to help your own company can drag down value later.

So before you sign, refinance, or sell, decide which interest you actually need valued. Then give the appraiser the leases, the occupancy split, and the intended use of the report. That keeps the number tied to the question you are asking.

Own the Building Your Business Runs From?

Whether you occupy it, lease part of it, or are weighing a sale-leaseback, we’ll value the right interest. We work from market rent and real lease data in your submarket.

Get a Commercial Quote

Frequently Asked Questions

What is the difference between an owner-occupied and an investment property appraisal?

An owner-occupied appraisal usually values the fee simple interest. So the appraiser estimates what the space would rent for at market. An investment property appraisal values the building subject to its existing leases. Contract rents, lease terms, and tenant strength all feed into that value.

Do appraisers use market rent for owner-occupied property?

Yes, in most cases. The owner pays no rent, so the appraiser studies comparable leases on similar buildings to estimate market rent. That rent then drives the income approach, alongside comparable sales.

How is contract rent different from market rent?

Contract rent is what a tenant actually pays under its lease. Market rent is what the space would likely rent for today on typical terms. When a lease runs below or above market, the appraiser accounts for that gap over the remaining term.

What is going-concern value?

Going-concern value is the value of an established business as a whole. That includes its real estate, equipment, and intangible assets. For federally related transactions, interagency guidelines bar using it as market value. An appraisal can still report it separately if clearly identified.

If my company leases the building from my own LLC, is it an investment property?

For valuation, the appraiser reads that lease and tests it against market rent. Related-party leases often stray from market terms. How to classify the loan is a separate question for the lender. Still, the 2006 federal CRE guidance treats space occupied by the owner or its affiliate as owner-occupied.

About PahRoo Appraisal & Consultancy

Owners, investors, and lenders come to PahRoo when they need a commercial value they can defend. Our commercial appraisal team works from our Lincolnwood office. We serve Chicago, Dallas, Philadelphia, Phoenix, and Naples, with deep coverage across Cook County through our Chicago appraisal services. Michael Hobbs, MAI, leads the firm.

Loan officer reviewing a commercial appraisal for lending at a bank office desk.
Commercial Appraisals for Lending and What Banks Require

When a credit officer orders a commercial appraisal for lending, the report has two jobs. It has to support the loan decision, and it has to hold up when an examiner pulls the file. Most of what banks require comes from one set of federal rules and the guidance built on them. So it pays to know where loan files usually come up short.

By the end of this article, you’ll know:

  • When a federally regulated lender needs a full appraisal, and when an evaluation will do.
  • What appraisal independence means for who orders the report and who talks to the appraiser.
  • What credit review should check before the appraisal goes to committee.

What a Commercial Appraisal for Lending Has to Meet

The rules trace back to Title XI of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989, better known as FIRREA. Title XI requires each federal banking agency to set appraisal standards for the institutions it oversees. So when a banker asks for a FIRREA appraisal, they mean a report that meets those agency rules.

Each agency publishes its own version. The OCC’s sits in 12 CFR Part 34, Subpart C, and it sets a clear minimum. The appraisal must follow USPAP, unless safe and sound banking calls for a stricter standard. It must be in writing, with enough analysis to support the decision to make the loan. It must also use the regulation’s definition of market value.

The same rule asks for deductions and discounts where they apply. That covers proposed construction or renovation, partially leased buildings, and leases written below market. Finally, a state licensed or certified appraiser has to do the work. But a credential alone does not prove competency, according to the rule. Experience with the property type counts too.

When an Evaluation Will Do and When It Won’t

Not every loan needs a full appraisal. The rule exempts several kinds of transactions, and three thresholds come up most often.

  • Commercial real estate transactions with a transaction value of $500,000 or less.
  • Business loans of $1 million or less, if repayment does not depend mainly on real estate sales or rental income.
  • Residential transactions with a transaction value of $400,000 or less.

For a loan, transaction value means the loan amount, not the property’s value. And an exempt loan still needs an evaluation of the collateral. The agencies raised the commercial threshold from $250,000 to $500,000 in 2018. Keep that in mind, because the interagency guidance still quotes the older figure.

There is a line on the other end, too. Once the transaction value reaches $1 million, the rule calls for a state certified appraiser.

Consider two hypothetical loans. A $450,000 loan on a small retail building falls under the commercial threshold, so an evaluation would satisfy the rule. A $1.2 million loan on the same kind of building needs a full appraisal by a certified appraiser. Still, an exemption only sets the minimum. The guidance says lenders should consider an appraisal for higher-risk deals even when an exemption applies.

An evaluation still needs substance. The guidance expects it to describe the property and its use, estimate market value as of an effective date, and explain how condition was confirmed. It should also name its sources and, when a person prepares it, identify that person.

Appraisal Independence Starts With Who Orders the Report

The lender or its agent has to engage a fee appraiser directly. The appraiser can have no interest in the property or the deal. Staff appraisers, in turn, have to stay independent of lending, investment, and collection.

The Interagency Appraisal and Evaluation Guidelines go further. If a bank uses an appraisal the borrower ordered or provided, it violates the agencies’ rules. Independence also suffers when the borrower recommends the appraiser, or when loan production staff pick one for a deal.

That does not mean the appraiser works in silence. A lender may share the sales contract on a purchase. It may also ask the appraiser to consider more information about the property or the comps, and to fix factual errors. What it can’t do is push the appraiser, directly or indirectly, toward a number.

Engagement letters belong in the same conversation. The guidance says lenders should use written engagement letters, and work should not start until the appraiser is engaged. A good letter states the intended use and the property interest. It also says whether you need an as is value alone, or prospective values upon completion or stabilization as well.

Using an Appraisal Another Bank Ordered

Participations and loan transfers raise a common question. Can you rely on an appraisal another lender ordered? Under the rule, yes, if another financial services institution engaged the appraiser directly. The appraiser also must have had no interest in the property or the transaction.

Even then, the receiving bank has to review the report as closely as it would its own and document that review. It should also confirm the original lender, not the borrower, ordered it. And it must not accept a report altered to hide the original client.

What Credit Review Should Check Before Committee

Every appraisal used for lending needs a review for USPAP compliance. Reviewers should be independent of the transaction and shielded from loan production staff. A reviewer cannot change the value the original appraiser reached. But a qualified reviewer can develop a second opinion of market value through a USPAP review. In practice, these are the points worth checking first.

  • The approaches. The appraisal has to include each approach that applies and explain any it leaves out. Our guide to the three approaches to value shows how each one works.
  • The income support. On income property, trace the net operating income back to the rent roll and the cap rate back to market evidence.
  • The value premise. For construction loans, banks generally ask for the as is value, plus prospective values if the deal calls for them. Those should rest on current and reasonably expected market conditions.
  • The leases. Vacancy in a partially leased building and leases below market should show up as deductions where they apply.

Those details feed straight into loan sizing. Take a hypothetical building appraised at $2.8 million from $196,000 of net operating income at a 7 percent cap rate. A $1.96 million loan sits at 70 percent loan-to-value. If the market supports 8 percent instead, the same income points to $2.45 million. Then that loan runs at 80 percent of value.

What Borrowers Can Do to Keep the Appraisal Moving

If you own the property or are buying it, you can’t hire the bank’s appraiser. But you can make the assignment faster and cleaner.

  • Tell your lender early if a recent appraisal exists. The guidance lets a borrower point the bank to it, so the bank can request it directly from the lender that ordered it.
  • Have current leases, a rent roll, and two or three years of operating statements ready before the inspection.
  • Pull together the survey, any environmental reports, and a list of recent capital work with costs.
  • Plan for access to tenant spaces, the roof, and mechanical rooms.

Questions about value should go through your loan officer, not to the appraiser. Also ask the lender early about timing and whether you will get a copy of the report. Practices vary from bank to bank, and knowing up front keeps the closing date realistic.

Most Lending Appraisal Problems Start at the Order

A borrower-supplied report or a vague engagement letter causes more trouble than any single comp. Get the order right, and the review tends to go faster. This article summarizes the federal rules in plain terms. How your institution applies them is a question for your compliance team and counsel.

Have a CRE Loan Heading to Credit Committee?

PahRoo prepares USPAP-compliant commercial appraisals with the support a reviewer looks for, from the rent roll to the cap rate.

Request a Commercial Quote

Frequently Asked Questions

What appraisal do banks require for a commercial loan?

A federally regulated bank generally needs a written, USPAP-compliant appraisal from a state licensed or certified appraiser the bank engages directly. Commercial real estate loans of $500,000 or less, and certain business loans up to $1 million, can use an evaluation instead. At $1 million and above, the appraiser must be state certified.

What is a FIRREA appraisal?

It is an appraisal that meets the rules the federal banking agencies adopted under Title XI of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989. Those rules require USPAP compliance, a written report with enough analysis to support the loan decision, the regulation’s definition of market value, and an independent appraiser.

Can a borrower order the bank’s appraisal?

No. Interagency guidance says a lender’s use of a borrower-ordered or borrower-provided appraisal violates the agencies’ appraisal regulations. A borrower can tell the lender that an appraisal already exists, and the lender can then request it directly from the institution that ordered it.

What is the difference between an evaluation and an appraisal?

An evaluation is an estimate of market value allowed for transactions exempt from the appraisal requirement, such as commercial real estate loans of $500,000 or less. It does not have to meet professional appraisal standards or be prepared by a licensed or certified appraiser. An appraisal must meet both.

What is appraisal independence?

It means the appraiser’s judgment stays separate from the lending side of the deal. The lender or its agent engages the appraiser directly, the appraiser has no interest in the property, loan production staff do not pick the appraiser, and no one pressures the appraiser toward a value.

Commercial Appraisals Built for Credit Review

Lenders, owners, and their advisors bring commercial assignments to PahRoo Appraisal & Consultancy across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Our commercial appraisal services page lists the property types we cover. For Chicago-area loans, our Chicago appraisal services page explains how to place an order.


Former church building on a residential block, a common subject of a special use property appraisal
When There Are No Comps for a Mixed-Use or Special Use Building

What do you tell a client who asks what a former church is worth? Or a bowling alley, or a storefront with four apartments upstairs? A special use property appraisal starts where the usual shortcuts stop. There may be no recent sales of anything like it, and no rental market to borrow from. So the report has to show more of its reasoning, and counsel should know where to look.

By the end of this article, you’ll know:

  • What makes a property special use or mixed-use, and why comparable sales fall short.
  • How highest and best use and the cost approach carry the analysis.
  • Which value, interest, and use questions to settle before the engagement letter goes out.

Why a Special Use Property Appraisal Takes More Work

A special use property is a building designed around one purpose. Its layout, structure, or equipment fits that use and little else. Think of a house of worship, a school, a theater, a car wash, a gas station, or a bowling alley. Appraisal texts usually call it special purpose property, but the idea is the same.

The trouble starts with the market. Few buyers want a building they would have to gut, so these properties sell rarely. When one does sell, the price often reflects a conversion or a teardown. Because of that, the sale may say little about what the building is worth in its current use.

So the appraiser widens the search. Sales from other counties or other states may come in, along with older ones. Each needs more adjustment and more explanation. The income approach has limits too, because many of these buildings have no rental market to speak of. Our guide to the three approaches to value explains how each one works on ordinary commercial property.

Highest and Best Use Comes Before Any Number

Every appraisal rests on a use. Highest and best use is the use that passes four tests. It has to be legally permissible, physically possible, financially feasible, and maximally productive. On a special use building, that analysis can decide the whole assignment.

Take a closed church on a residential block. It may be worth the most to another congregation. Or a developer may pay more to convert it to housing, if zoning allows. Sometimes the land is worth more with the building gone. Those are three different values for the same parcel.

The first test is where your work and ours meet. Zoning, a special use permit, legal nonconforming status, deed restrictions, and easements all shape what a buyer can do. The appraiser reports what the analysis relied on. But if the legal status is in doubt, that call belongs to counsel, not to us. In that case the report should state the assumption plainly, so any reader knows what the value depends on.

Federal bank guidance takes the same view. Under the Interagency Appraisal and Evaluation Guidelines, market value should reflect the property’s actual physical condition, use, and zoning as of the effective date. If the highest and best use is redevelopment, demolition and site preparation costs also belong in the analysis.

Where the Cost Approach Earns Its Place

When sales and rents are thin, the cost approach often carries the most weight. It adds land value to the cost of building the improvements new, then subtracts depreciation. On a special use building, depreciation is the hard part.

Physical wear is easy enough to see, but functional obsolescence takes more judgment. A 600-seat sanctuary or a 40-lane bowling center may cost far more to build than the market would pay for it today. That gap has to come off the cost, and the report should say how the appraiser measured it.

Consider a hypothetical single-purpose building. Say the land is worth $600,000 and the improvements would cost $3,200,000 to replace. Physical depreciation of 35 percent takes off $1,120,000. Functional obsolescence then takes off another $480,000. So the improvements contribute $1,600,000, and the cost approach indicates $2,200,000.

In a dispute, that $480,000 line is the one the other side will test. The same goes for the land value, which still comes from sales. The interagency guidelines also expect the appraiser to explain any approach left out. If the report skips sales comparison, it should say why.

Mixed-Use Property Is Several Buildings in One

Mixed-use property has the opposite problem. There is plenty of market evidence, but it belongs to different markets. A building with retail at grade and apartments above answers to retail rents and apartment rents at once. Each part has its own vacancy pattern, expense load, and lease structure.

So the income approach gets built one component at a time. The appraiser estimates net operating income for the retail and for the apartments, then asks who buys the building as a whole. The cap rate should come from sales of buildings with a similar mix. If it can’t, the report should explain how the appraiser blended the rate.

Leases need a close read as well. The interagency guidelines note that a long lease below market rent can make the leased fee worth less than the fee simple. For that reason, the report must state which interest it values.

In Cook County, the mix also drives the tax line. Under the Assessor’s class definitions, revised in December 2024, a mixed-use building with six or fewer units and under 20,000 square feet is Class 2-12. That class sits at a 10 percent level of assessment, while commercial classes sit at 25 percent. Larger buildings can end up split between the two. The Assessor makes that call, but the appraisal still has to model the taxes a buyer would expect.

The Real Estate Is Not the Business

Some special use properties sell as operating businesses. A car wash or a hotel changes hands with its equipment and its customer base. That total is going concern value, and it is not the value of the real estate.

The distinction matters for lending. The same federal guidelines say going concern value, value in use, and value to a specific user may not stand in for market value in a federally related transaction. An appraisal can report them, but only as separate opinions with clear labels.

SBA lending went a step further. In a 2015 notice, SBA said going concern appraisals of special purpose property must allocate separate values to land, building, equipment, and intangible assets. SBA has revised its procedures since then, so confirm the current rule with the lender.

Still, the allocation question comes up in purchase agreements, collateral descriptions, and ownership disputes too. How those pieces get characterized legally is your call. Our job is to support each number.

What Owners and Investors Should Hand the Appraiser

If you own or are buying one of these buildings, the file you hand over shapes the report. So pull these together first.

  • Every commercial lease, plus a rent roll that separates commercial space from apartments.
  • Three years of income and expenses, with shared costs such as taxes and insurance split by component where you can.
  • The certificate of occupancy and any special use permit, variance, or zoning letter.
  • For a single-purpose building, the construction costs or recent contractor bids.
  • A list showing which equipment stays with the building and which belongs to the business.

If your own company occupies the building, put a written lease in place at a rent you can support. Then the appraiser has something to analyze besides your word. Also, before you buy a special use building, price the exit. Ask a contractor what conversion would cost, because the next buyer will ask the same thing.

Settle Four Questions Before the Engagement Letter Goes Out

Most trouble with these appraisals starts before anyone hires the appraiser. So settle four points up front and put them in the engagement letter.

  • Start with the value, whether market value of the real estate, value in use, or going concern.
  • Then name the interest, fee simple or leased fee.
  • Next comes the use, as the property stands today or under a stated zoning or conversion assumption.
  • Finally, fix the date, either today or a past date the matter turns on.

A special use property appraisal that answers those four on page one is far easier to defend. It is also easier to compare when the other side produces its own report.

Drafting Around a Hard-to-Value Building?

PahRoo lays out the highest and best use, the approaches, and any allocation step by step, so counsel can follow how the value was reached.

Discuss Your Commercial Assignment

Frequently Asked Questions

What counts as special use property?

A property built for one purpose, with a design or layout that suits that use and little else. Common examples are houses of worship, schools, theaters, car washes, gas stations, and bowling alleys. Appraisers often call it special purpose property. Because few buyers want such a building as it stands, sales are scarce.

How do you appraise a church or school?

Usually with the cost approach in the lead. The appraiser values the land from sales, estimates the cost to build the improvements new, then subtracts physical wear and functional obsolescence. Sales of similar buildings, often from a wider area, serve as a check. Highest and best use analysis comes first, since conversion or redevelopment may be worth more than continued use.

How is mixed-use property valued?

Mostly through the income approach, built one component at a time. Retail, office, and apartment space each get their own market rent, vacancy, and expense analysis. The appraiser then applies a cap rate supported by sales of buildings with a similar mix, and checks the result against those sales directly.

What is a going concern in appraisal?

It is the value of an operating business together with its real estate, equipment, and intangible assets. Federal bank guidance says going concern value may not be used as market value for a federally related transaction, though an appraisal may report it as a separate, clearly identified opinion.

Why are special use properties hard to value?

They rarely sell, and many have no rental market, so two of the three approaches have little data. The cost approach fills the gap, but it depends on a judgment about how much value the specialized design has lost. That judgment needs clear support in the report.

Appraisals for Buildings That Don’t Fit a Template

Odd buildings are regular work at PahRoo Appraisal & Consultancy. Our MAI and SRA designated team serves Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. See our commercial appraisal services for the property types we cover, mixed-use and special purpose assignments included. Or start with our Chicago appraisal services page for local scope questions.


Brick courtyard apartment building in Chicago, the subject of a multifamily appraisal
The Rent Roll Is Where Apartment Value Lives

A multifamily appraisal lands on a lender’s desk with one number on the cover and forty pages behind it. But those pages matter more than the number. An apartment building sells for its rents, so the appraisal stands or falls on the rent roll, the expenses, and the cap rate. If you underwrite apartment loans, those are the pages to read first.

By the end of this article, you’ll know:

  • How a multifamily appraisal turns a rent roll into value.
  • Which rent roll and expense details deserve a second look in the report.
  • What owners can prepare so a refinance appraisal holds up.

How a Multifamily Appraisal Values an Apartment Building

Apartment buildings trade on income, so the income approach carries the most weight. The appraiser estimates what the building should earn in a typical year. Then the cost to run it comes off, and the result converts into value. The sales comparison approach checks that answer against recent apartment sales, usually on a price per unit basis. The cost approach rarely drives the number on an existing building, though it can matter on new construction.

Unit count changes the paperwork too. Under the OCC’s appraisal rule for national banks, a transaction not secured by a single 1-to-4 family residential property counts as a commercial real estate transaction. So a five-unit building falls on the commercial side. The same rule calls for a State certified appraiser on federally related commercial transactions over $500,000. Two- to four-unit buildings still go on the residential Fannie Mae Form 1025, where the income approach is a simple gross rent multiplier. At five units and up, the work usually moves to a full commercial income analysis instead.

The Rent Roll Comes First

The rent roll lists every unit in the building and what each one pays. A usable one shows unit number, unit type, tenant, lease start and end, contract rent, and any concession. It should also flag vacant units, down units, and units set aside for staff. The appraiser checks it against the leases and the trailing twelve months of operating statements. In many assignments, bank deposits get checked too.

Then contract rents get compared to market rents. If in-place rents sit well below market, the building has upside a buyer will pay for, but only with time and turnover. If rents sit above market, that extra income may not survive the next lease cycle. Concessions matter here as well. One free month on a 12-month lease cuts the effective rent by about 8.3 percent, and a rent roll showing only face rent hides that.

From Occupancy to Net Operating Income

Occupancy comes in two versions. Physical occupancy simply counts occupied units. Economic occupancy compares the rent actually collected against the rent the building could earn. A building can be 96 percent physically occupied and still collect far less because of concessions, delinquency, or below-market leases. So the appraiser applies a vacancy and collection loss based on the market and the building’s history, not just today’s snapshot.

Operating expenses get the same scrutiny. Property taxes, insurance, owner-paid utilities, repairs, payroll, management, and replacement reserves all come out before net operating income. Then appraisers usually test each line per unit against comparable buildings. An owner who self-manages still carries a market management fee in the analysis, because a buyer would pay one. We walked through the full build in our guide to net operating income in commercial real estate.

Cap Rate, Price Per Unit, and the Gross Rent Multiplier

Direct capitalization divides one year of stabilized NOI by a market cap rate. That rate should come from confirmed sales of similar apartment buildings, not a national survey. Our explainer on the cap rate in commercial real estate covers where those rates come from. For a building in lease-up or mid-renovation, the appraiser may run a discounted cash flow instead, as our income approach guide explains.

Consider a hypothetical 24-unit building averaging $1,650 a month per unit. That comes to $475,200 a year in potential rent. Add $14,400 in parking and laundry income, then take 5 percent for vacancy and collection loss. Effective gross income lands at $465,120. Subtract $6,800 per unit in expenses, including reserves, and NOI comes to $301,920. At a 6.75 percent cap rate, the indicated value is about $4,470,000, or roughly $186,000 per unit.

Now move the cap rate to 7.25 percent. Same building, same rents, and the value drops to about $4,160,000. Half a point cost more than $300,000. That is why the cap rate support deserves as much attention as the rent roll.

The gross rent multiplier is the quick check. It divides price by gross rent, so it skips expenses entirely. Here, $4,470,000 over $475,200 in annual rent is about 9.4. If similar buildings nearby traded closer to 8 times rent, the appraiser has some explaining to do.

What Lenders Should Check Before Relying on the Number

A lender does not need to redo the appraisal. But a handful of checks catch most problems.

  • Rent roll date. It should sit close to the effective date, and the unit count should match the building.
  • Contract versus market rent. The report should show both and say which one drives the income.
  • Concessions and delinquency. Look for the adjustment, not just the face rents.
  • Expense support. Per-unit expense comparables, a market management fee, and reserves.
  • Cap rate support. Confirmed apartment sales in the same submarket, with the income extracted for each.
  • As is versus as stabilized. If the report gives both, know which one your loan depends on.

The OCC rule also expects appraisals to analyze and report deductions for partially leased buildings and non-market lease terms. That applies directly to a building mid-turnover or full of below-market leases. If the report skips it, ask why.

Where the Apartment Market Sits Right Now

Market data sets the backdrop for those assumptions. CBRE’s Q2 2026 multifamily figures put national vacancy at 4.3 percent, with average rent at $2,257 a month. Net absorption also beat new completions for a second straight quarter. In its release, CBRE said the Midwest led the country in annual rent growth at 2 percent.

Chicago looks tighter than most. Cushman & Wakefield’s Chicago MarketBeat reported 94.9 percent occupancy in Q2 2026, above the 10-year average of 93.8 percent. Effective rents rose 3.2 percent year over year. Still, a metro average does not appraise a 24-unit walk-up in Rogers Park. Instead, the submarket, the building’s condition, and its actual leases decide that.

For Owners: Get the File Ready Before the Appraiser Calls

If you own the building and a refinance is coming, most appraisal delays trace back to missing paperwork. So pull these together before the lender orders the report.

  • A current, dated rent roll with concessions and vacant or down units marked.
  • The trailing 12 months of income and expenses, plus the two prior calendar years.
  • Copies of the leases, or at least a sample, plus any commercial leases in the building.
  • Recent tax bills, the insurance declarations page, and the utility bills you pay.
  • A dated list of capital work, such as roofs, boilers, and unit renovations, with what each cost.

Then reconcile the rent roll to your bank deposits yourself. If they don’t match, the appraiser will find it, and the explanation takes longer later than now. Don’t annualize your best month either. Appraisers work from the trailing twelve months and the market, so an optimistic pro forma won’t carry the value. A clean file won’t raise the number. Still, it keeps an appraiser from discounting the number for uncertainty.

Underwrite the Rent Roll, Not the Offering Memo

An offering memo shows the building at its best. A credible multifamily appraisal shows it the way a typical buyer would see it, with market rents, real expenses, and a cap rate taken from actual sales. So read the rent roll analysis before the value on the cover. If the income holds up there, the number usually does too.

Underwriting an Apartment Loan This Quarter?

PahRoo appraises apartment buildings from the rent roll up, with market rent, expense, and cap rate support your credit team can check line by line.

Request a Multifamily Appraisal Quote

Frequently Asked Questions

How are apartment buildings appraised?

Mainly through the income approach. The appraiser analyzes the rent roll and operating statements, estimates market rent, vacancy, and expenses, and converts net operating income into value with a cap rate drawn from comparable sales. Price per unit and gross rent multiplier comparisons from recent apartment sales serve as a check.

What is a rent roll?

A unit-by-unit list of a building’s tenants and rents. It typically shows unit number and type, tenant, lease start and end dates, contract rent, concessions, and which units are vacant. Appraisers compare it against the leases and operating statements before relying on it.

How does NOI work for multifamily?

Net operating income is effective gross income minus operating expenses. For an apartment building, that means potential rent plus other income such as parking or laundry, less vacancy and collection loss, less taxes, insurance, owner-paid utilities, repairs, payroll, management, and reserves. Debt service is not deducted.

What is a gross rent multiplier?

The ratio of a property’s sale price to its gross rent. Fannie Mae’s Form 1025 for two- to four-unit properties multiplies gross monthly rent by a GRM to indicate value. For larger apartment buildings it works mainly as a quick check on the full income analysis, since it ignores expenses.

How many units make a property commercial?

Under federal bank appraisal rules, a loan secured by anything other than a single one-to-four family residential property counts as a commercial real estate transaction, so five units and up falls on the commercial side. Two- to four-unit properties usually go on residential appraisal forms. Individual lenders may draw their own lines for specific loan programs.

Multifamily Valuation for Lenders and Owners

Every apartment assignment at PahRoo Appraisal & Consultancy starts with the rent roll, across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Our commercial appraisal services page lists the property types we cover. For local scope and timing questions, start with our Chicago appraisal services page.

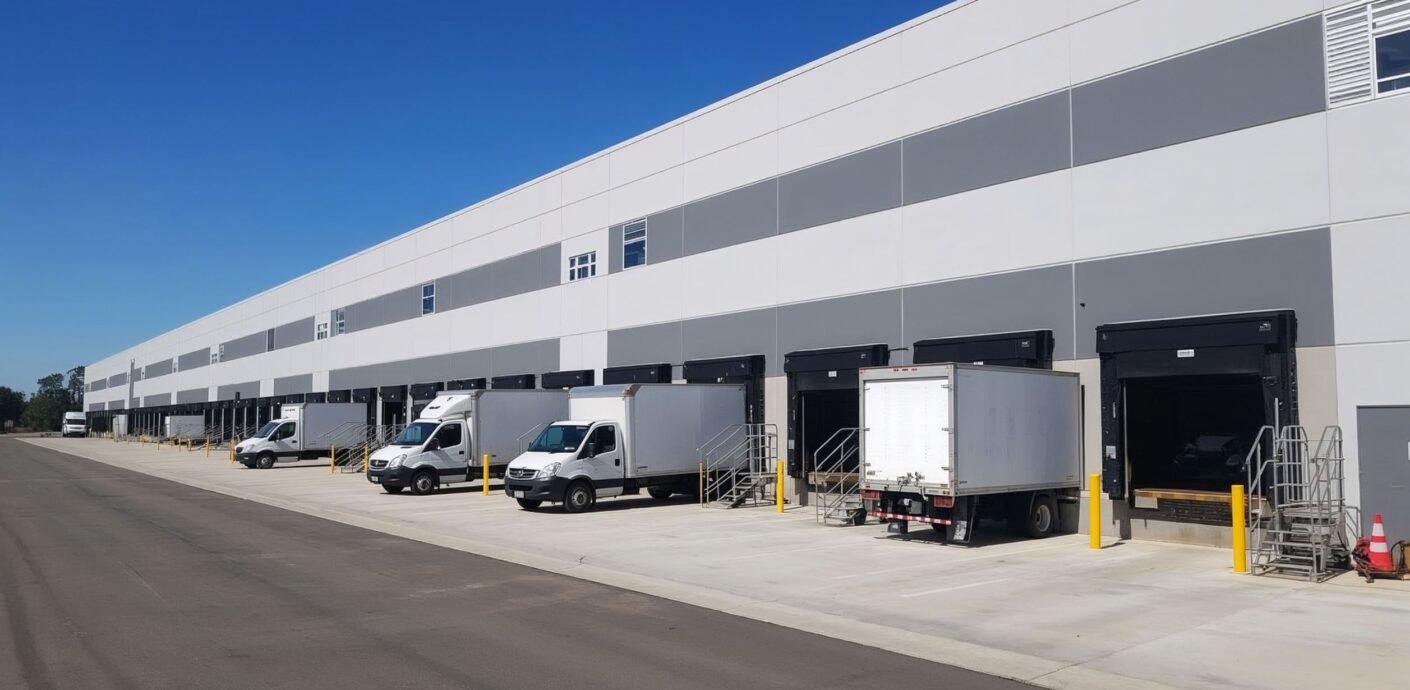
Modern distribution center with loading docks, subject of an industrial property appraisal
What Your Warehouse’s Walls Are Really Hiding

An industrial property appraisal comes down to a simple question. How fast can product move through this building, and how much space does it hold while doing it? Curb appeal barely matters here. A plain concrete box with the right clear height and enough dock doors can out-value a prettier building down the street. Instead, the reason sits in the numbers behind the walls.

By the end of this article, you’ll know:

  • The five factors that carry the most weight in an industrial valuation.
  • Why clear height and dock ratios move value more than square footage alone.
  • What is fueling warehouse and logistics demand right now, and what it means for your number.

What an Industrial Property Appraisal Weighs Most

Five factors do most of the work in an industrial valuation.

  • Location inside the logistics network. Proximity to highways, intermodal rail, and the labor pool that staffs the building.
  • Clear height and functional layout. How much usable cubic space the building offers, not just its footprint.
  • Loading and circulation. Dock door count, trailer parking, and truck court depth relative to building size.
  • Tenant credit and lease structure. Who is paying rent, on what terms, and for how long.
  • Building age and systems. Power capacity, sprinkler class, and the capital needed to bring the space current.

Most industrial buildings, in practice, get valued through a blend of two approaches. Leased distribution centers and multi-tenant parks lean on the income approach. A buyer there is purchasing the rent stream, not just the shell. Owner-user buildings lean harder on the sales comparison approach instead. Appraisers weigh those sales against similar buildings in the same size and height class. The cost approach plays a supporting role too, mostly on newer or purpose-built facilities. Our commercial appraisal services also cover all three, across office, retail, and industrial property.

Income, NOI, and the Cap Rate Behind the Number

For leased industrial, the rent roll gets read closely. Contract rents get compared against market rents. Expirations then get mapped across the holding period, and the reimbursement structure gets checked line by line. Industrial leases run triple net far more often than office leases do. The tenant typically covers taxes, insurance, and most maintenance instead of the landlord. So that keeps the landlord’s expense load lighter, and the income more predictable. That predictability is part of why industrial has held cap rates tighter than office through the same rate cycle. We walked through how that income figure gets built in our guide to net operating income in commercial real estate. The same mechanics apply here. Tenant concentration still matters too. A single-tenant distribution building lives or dies with one renewal decision. So appraisers weigh that risk against the size of the rent check.

Clear Height, Docks, and the Physical Specs That Move Value

Clear height matters more than almost any other industrial spec. It is the unobstructed vertical space from the floor to the lowest hanging obstruction. That obstruction could be a joist, a light, or a sprinkler head. Still, older buildings across the Chicago market commonly top out around 24 to 28 feet. Modern Class A distribution space runs 32 to 36 feet instead. Large e-commerce fulfillment buildings increasingly push past 40 feet to support automated storage systems. That gap is not cosmetic. Moving from a 30-foot to a 36-foot clear height can add 10 to 25 percent of usable storage capacity. It does that without adding a single square foot to the building’s footprint. So appraisers price that extra cubic space directly into value.

Dock doors, trailer parking ratio, and column spacing round out the physical picture. A building with too few docks for its size creates a bottleneck. That bottleneck shows up as functional obsolescence in the appraisal. It happens even when the square footage checks every box on paper. Brokers advising an owner ahead of a listing can get ahead of this instead of explaining it after the fact. Pull the actual clear height and dock count before setting an asking price. Then anchor the comp set to buildings in the same height class, not the metro average. An appraisal that lands under the listing price on an older building usually traces back to a spec gap, not a market swing. So flagging it early keeps the deal from stalling at the lender’s desk.

Why Logistics and E-commerce Demand Is Driving Industrial Value

Industrial has been a standout sector for years. The current data backs that up. According to CBRE’s Chicago Industrial Figures for the second quarter of 2026, the metro’s industrial availability rate fell to 8.6 percent. That is down 30 basis points from the prior quarter. Net average asking rents climbed to $9.30 per square foot, up 7.4 percent year over year. Net absorption jumped to 6.1 million square feet in the quarter. That is well ahead of the 1.1 million square feet absorbed in the first quarter. Another 11.8 million square feet remained under construction, split evenly between speculative and build-to-suit projects.

Nationally, CBRE’s second-quarter research reported the first decline in industrial vacancy since 2022. Demand broadened beyond third-party logistics providers too, as manufacturers picked up a larger share of leasing activity. E-commerce fulfillment, manufacturing reshoring, and tighter big-box supply are feeding the same story from different directions. For an appraisal, that shows up as stronger market rent growth assumptions. In many submarkets, cap rates have also held firmer than other property types through the same financing environment.

The Number Should Match the Building, Not the Market Average

A market average is only a backdrop. Still, it does not appraise your specific building. Two distribution centers half a mile apart can carry very different values. Clear height, dock ratio, and lease structure decide that, not the address. Before a sale, refinance, or partnership buyout, get a number built from the building’s actual specs and tenants instead. After all, a market headline is not a substitute.

Ready to Put a Real Number on Your Industrial Building?

PahRoo appraises warehouses, distribution centers, and manufacturing buildings across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples.

Request a Commercial Appraisal Quote

Frequently Asked Questions

How is industrial property appraised?

Most industrial buildings are valued through a blend of the income approach and the sales comparison approach. Leased distribution centers rely mainly on income, built from the rent roll, market rents, and expenses. Owner-user buildings lean more on comparable sales of similar buildings in the same size and clear height class. The cost approach plays a supporting role, particularly on newer or purpose-built facilities.

What is clear height in a warehouse?

Clear height is the unobstructed vertical space from the floor to the lowest hanging obstruction. Common examples are a joist, a light, or a sprinkler head. Older industrial buildings often run 24 to 28 feet. Modern Class A distribution space commonly runs 32 to 36 feet, and large e-commerce fulfillment buildings increasingly reach 40 feet or more to support automated storage systems.

Why is industrial real estate in such high demand?

E-commerce fulfillment, reshoring of manufacturing, and a slowdown in new construction have kept demand ahead of supply in most markets. CBRE’s second-quarter 2026 research recorded the first national decline in industrial vacancy since 2022. Manufacturers also took a growing share of leasing activity alongside traditional logistics tenants.

What is a distribution center worth?

There is no single number that applies across a market. Value depends on the building’s clear height, dock doors, and trailer parking ratio. It also depends on tenant credit, lease term, and location relative to highways and rail. Two similar-sized buildings in the same submarket can carry very different values once those specs are compared.

How does location affect an industrial appraisal?

Proximity to highway interchanges, intermodal rail, and the local labor pool drives both achievable rent and buyer demand. Submarkets along major logistics corridors typically see tighter vacancy and stronger rent growth than the metro average. Appraisers weigh that submarket-level data rather than a single citywide figure.

Built From the Building, Not the Headlines

PahRoo Appraisal & Consultancy appraises commercial property across five markets. That also includes industrial, office, and retail, for owners, investors, brokers, and lenders. For a similar look at income mechanics in another property type, see our office building breakdown of what drives the value of an office building. Or start with our Chicago appraisal services page for scope and timing questions.

Neighborhood strip center with grocery anchor and inline shops, the subject of a retail property appraisal
Retail Property Appraisal and What Moves the Value

Two strip centers on the same road, same size, same age, same asking price. One is worth 15 percent more than the other, and nothing about the buildings explains why. The leases do. A retail property appraisal spends less time on the roof and the parking lot than brokers expect. It spends far more on who signed the leases, how long they run, and what happens to the rent when they end. So here is how location, tenants, and lease terms each move the number.

By the end of this article, you’ll know:

  • How trade area, access, and co-tenants set the ceiling on retail rent
  • Why tenant credit and tenant category can move a cap rate more than the building does
  • What a rent roll and lease abstract have to show before the appraisal can start

Location Sets the Ceiling

Retail rent is a function of what a tenant can sell from that spot. So the appraiser starts outside the property line. The trade area is the geography a center actually draws from. That may be a one-mile ring for a grocery-anchored neighborhood center, or a 20-minute drive for a destination power center. Population, household income, and daytime employment inside that area tell the appraiser what rent the market can bear. Then traffic counts, visibility, and access decide whether a tenant can capture it.

Co-tenancy matters almost as much as the corner. An inline space next to a strong grocer rents for more than the same space next to a vacant box. The grocer brings the cars. Anchors, shadow anchors across the street, and out-parcel pads all shape the rent an inline tenant will pay. So when the appraiser selects rent comparables, the first filter is not square footage. It is whether the comparable center has the same kind of draw.

Tenants Set the Cap Rate

Once the rent is established, the question shifts to how reliable it is. Two centers with the same net operating income can trade at very different prices. A buyer pays more for income that is likely to arrive. A national credit tenant on a long lease is income a buyer can underwrite. A first-year local operator is a bet. The appraiser reflects that difference in the capitalization rate. In practice, the spread between a credit-anchored center and a local-tenant center can be wider than the spread between a new building and an old one.

Tenant category matters too, and the national numbers show why. The Census Bureau’s July 2026 retail sales release put total retail and food services sales up 5.0 percent from a year earlier. Underneath that headline, nonstore retailers were up 7.7 percent and restaurants and bars were up 5.0 percent. Furniture stores were down 1.2 percent. So a center full of restaurants and service tenants is riding a different current than a center full of furniture showrooms. The appraiser’s vacancy and credit loss assumptions should say so.

Where tenant sales are available, the occupancy cost ratio is the health check. Rent plus recoveries, divided by sales, tells the appraiser whether a tenant can afford its lease. A tenant paying more of its sales than its category can sustain is a renewal risk no matter what the lease says. Most appraisals do not get sales data, though. Then the appraiser leans on category trends and the tenant’s public reporting where it exists.

Lease Terms That Change the Number

This is the section that does the work, and the one most rent rolls are least prepared for. The lease structure comes first. Under a triple net lease, the tenant pays its share of taxes, insurance, and common area maintenance on top of base rent. So the landlord’s net income sits close to the base rent. Under a gross lease, the landlord absorbs those costs, and rising taxes come straight out of net operating income. A modified gross lease splits them. Two centers with identical base rents can have very different net income. That is why our guide to net operating income starts with the recovery structure.

Term and rollover come next. A center where 40 percent of the income expires within 24 months carries costs a fully leased center does not: downtime, tenant improvement allowances, and leasing commissions. The appraiser models those costs in the year they land. So a long-term rent roll and a short-term rent roll with the same current income do not support the same value under the income approach. Renewal options, and whether they are at fixed rent or market, sit inside the same analysis.

Then the clauses that brokers sometimes skip. A co-tenancy clause lets a tenant reduce rent or leave if an anchor goes dark or occupancy drops below a threshold. So one vacancy can cascade. An exclusive-use clause blocks the landlord from leasing to a competing use. That narrows the pool of replacement tenants. Rent escalations, percentage rent breakpoints, and caps on CAM recoveries all change the income stream. None of them show up on a one-page rent roll. All of them show up in value.

What a Retail Property Appraisal Needs From the Rent Roll

A usable rent roll lists every suite with tenant name, square footage, lease start and expiration, and current base rent. It also shows the escalation schedule, recovery structure, renewal options, and any abatement still running. Behind it, the appraiser needs lease abstracts or the leases themselves for anchors and any tenant over about ten percent of the income. Add the last two years of CAM reconciliations and operating statements. Vacant suites need asking rent and the date they went dark.

When that package is complete, the appraisal moves quickly and the conclusions are defensible. When it is missing, the appraiser fills gaps with market assumptions. Market assumptions rarely favor the seller. The same package is what the buyer’s lender will ask for. So assembling it once serves the listing, the appraisal, and the closing.

A Hypothetical Neighborhood Center

Consider a 25,000 square foot center: a 12,000 square foot grocer on a triple net lease with 11 years left, six inline tenants, and one 1,800 square foot vacancy. Net operating income is $504,000. Suppose the inline leases are staggered, with no more than one expiring in any year, and the grocer is a regional credit. An appraiser might support a 7.0 percent cap rate, indicating $7,200,000.

Now change one fact. Four of the six inline leases expire within 18 months, and two tenants are month-to-month. The grocer has a co-tenancy clause tied to inline occupancy. Same building, same income today. An appraiser might now support an 8.0 percent rate, landing near $6,300,000, and deduct lease-up costs on top. The gap is close to $900,000 before those deductions. Every dollar of it lives in the leases.

Where Owners Get Ahead of the Appraisal

For an owner planning a sale or a refinance, the highest-return work happens before the appraiser is engaged. Renew the tenants whose leases expire inside the next two years, even at a modest concession. Term is worth more than the last dollar of rent. Resolve open co-tenancy exposure by backfilling the space that triggers it. Finish the CAM reconciliations so recovery income is documented rather than estimated. And abstract every lease so the rollover schedule, options, and clauses sit in one place. Each step converts an assumption into a fact the appraiser can cite.

Read the Rent Roll Before You Read the Cap Rate

When a retail appraisal lands on your desk, skip the cover value and go to the rent roll analysis. Check that lease structures are identified suite by suite and the rollover schedule is laid out by year. Check that the anchors’ clauses are addressed by name. Then check that the cap rate reflects the tenants actually in the building, not a survey average. If those pieces are there, the value will hold up with the buyer’s lender. If they are not, the number is a guess with a decimal point. Our overview of the three approaches to value shows how the income analysis fits with the others. For retail, it is nearly always the one that decides.

Pricing a Center With Rollover on the Horizon?

PahRoo appraises retail property from the leases up, with rollover modeling and cap rate support a buyer’s lender will accept.

Request a Retail Appraisal Quote

Frequently Asked Questions

How is a retail property appraised?

Primarily through the income approach. The appraiser analyzes the rent roll and leases to establish net operating income, evaluates tenant credit and lease term to select a capitalization rate, and models lease-up costs for expiring or vacant space. Sales comparison serves as a check on the result, and location analysis of the trade area, traffic, and co-tenancy frames the rent the market will bear.

What is a triple net lease and why does it matter to value?

Under a triple net lease the tenant pays its share of property taxes, insurance, and common area maintenance in addition to base rent. The landlord’s net income is close to the base rent and is insulated from rising expenses. Under a gross lease the landlord absorbs those costs, so the same base rent produces lower net operating income and a lower value.

How does tenant credit affect the cap rate?

Buyers pay more for income they are confident will arrive, so a center anchored by a national or regional credit tenant on a long lease supports a lower capitalization rate than a center leased to local operators on short terms. The appraiser reflects that in the rate, and the spread between the two can move value more than the age or condition of the building.

What is a co-tenancy clause?

A lease provision that lets a tenant reduce rent or terminate if a named anchor closes or center occupancy falls below a set level. It means one vacancy can trigger others. An appraiser reads anchor and major tenant leases for these clauses and accounts for the exposure in the vacancy and credit loss analysis.

What does an appraiser need from the rent roll?

Every suite with tenant name, square footage, lease start and expiration, current base rent and escalations, recovery structure, renewal options, and any abatements still running. Behind the rent roll, the appraiser needs lease abstracts or full leases for anchors and major tenants, two years of operating statements, and the CAM reconciliations.

Retail Valuation From the Lease Up

Brokers, owners, and lenders across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples engage PahRoo Appraisal & Consultancy for retail assignments from single-tenant pads to anchored centers. Our commercial appraisal services page lists the property types we cover, and our article on office building value drivers shows the same lease-first method applied to a different asset class. To discuss a retail property, contact our team.

What Drives the Value of an Office Building

An office building appraisal comes down to one question: how reliably will this building produce income, and for how long? Everything the appraiser examines feeds that answer. So when owners ask why two similar-looking buildings carry very different values, the explanation almost always sits in the leases, the tenants, and the submarket rather than the architecture.

By the end of this article, you’ll know:

  • The five factors that carry the most weight in office value
  • How leases, rollover, and tenant credit shape the income analysis
  • Why Class A buildings and older stock are moving in opposite directions

What an Office Building Appraisal Weighs Most

Five factors do most of the work in an office valuation:

  • Occupancy and lease terms: how much space is leased, at what rents, and for how long
  • Tenant credit: the financial strength behind each signature on the rent roll
  • Location and submarket: the vacancy, rent, and demand picture on that block, not the metro average
  • Building class and condition: where the property sits in the flight to quality
  • Market cap rates: what buyers currently pay for a dollar of office income

Office buildings are valued mainly through the income approach, because buyers purchase them for their income streams. The appraiser tests each factor above and translates it into the numbers behind the value.

Income Is the Engine: Leases, Rollover, and NOI

The rent roll gets read line by line. Contract rents are compared against market rents. Expirations are mapped across the holding period, because a building with 40 percent of its leases rolling in two years carries more risk than one with staggered ten-year terms. Rent steps, expense reimbursements, tenant improvement obligations, and leasing commissions all shape the projection.

Those inputs flow into net operating income, and we covered how that number gets built in our guide to net operating income in commercial real estate. For office specifically, the vacancy assumption does heavy lifting. Actual occupancy, submarket vacancy, and realistic downtime between tenants all get weighed rather than assumed away.

Tenant Credit: The Rent Roll Behind the Rent Roll

A lease is only as good as the tenant paying it. Ten years of income from an investment-grade company is worth more than the same rent from a startup, so appraisers consider tenant quality when weighing the durability of income. Concentration matters too. A single-tenant building lives or dies with one renewal decision, while a diversified roster spreads that risk across many decisions.

This is why two buildings with identical NOI can appraise differently. The income may match today, but the probability of it continuing does not, and buyers price that difference.

Building Class, Condition, and the Flight to Quality

The office market is splitting by quality. According to the CBRE Q1 2026 U.S. office market report, overall vacancy stood at 18.6 percent while prime buildings ran at 12.7 percent, and asking rents grew at their fastest pace in six years. Tenants are concentrating in the best space and abandoning the rest.

For the appraisal, class is not a label but a set of measurable traits: systems, amenities, floor plates, energy performance, and the capital spending needed to stay competitive. An older Class B building may need substantial investment just to hold its tenancy, and that cost comes out of value. In some cases, highest and best use analysis even asks whether the building should remain an office at all.

Why Office Values Fell, and How an Appraisal Reads the Recovery

Office values dropped for two stacked reasons. Hybrid work cut demand for space, which pushed vacancy up and rents down in weaker buildings. Then higher interest rates pushed cap rates up, which cut the price of every dollar of income. National vacancy has now edged past its peak and demand has turned positive, but the recovery is uneven across markets and building classes.

That unevenness is exactly why office work demands submarket-level analysis. A metro average tells you little when one corridor is tightening and the next is emptying. Our commercial appraisal services build the value from the property’s actual leases and its actual submarket, so the conclusion reflects your building rather than the headlines.

What is your office building actually worth right now?

In a market moving this unevenly, last year’s number is stale. PahRoo appraises office property from the rent roll up, with submarket evidence a buyer or lender can verify.

Request a Commercial Appraisal Quote

Frequently Asked Questions

What drives the value of an office building?

Occupancy and lease terms, tenant credit, submarket conditions, building class and condition, and market cap rates. These determine how much income the building produces, how durable that income is, and what buyers will pay for it.

How are office buildings appraised?

Mainly through the income approach. The appraiser analyzes the rent roll, compares contract rents to market rents, applies vacancy and expense assumptions, and converts the resulting net operating income into value using market-derived rates, checked against comparable sales.

Why have office building values fallen?

Hybrid work reduced demand for space, which raised vacancy and weakened rents, while higher interest rates pushed cap rates up. Both forces cut value at once. The decline has been uneven, hitting older buildings much harder than prime space.

What is a Class A office building?

The highest-quality tier in a market: modern systems, strong locations, competitive amenities, and creditworthy tenants. Class B and C buildings are older or less competitive. Class is relative to the local market rather than a fixed national standard.

How does vacancy affect office value?

Vacant space produces no income but still incurs expenses, so vacancy reduces net operating income directly. Appraisers also weigh submarket vacancy, because it sets how long re-leasing will take and what rent the space can realistically achieve.

Office Valuation Built From the Rent Roll Up

PahRoo Appraisal & Consultancy appraises office and other commercial property across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, for owners, investors, and lenders. Start with our Chicago appraisal services page, or review our appraisal consulting FAQ for scope and timing questions.

Direct capitalization calculation in a commercial appraisal
The Income Approach: How Appraisers Value Income-Producing Property

When a lender questions a commercial value, the question almost always lands on the same section. The income approach appraisal analysis is where the reasoning is most exposed, because every assumption in it has a dollar attached.

By the end of this article, you’ll know:

  • How the income approach converts income into value
  • The difference between direct capitalization and discounted cash flow
  • The five assumptions worth checking before you rely on the number

What the Income Approach Appraisal Method Does

The income approach converts a property’s expected future income into a present value. It rests on a simple idea. Buyers of income-producing real estate are buying a stream of money over time, so the price they pay reflects how much that stream is worth today.

This is recognized methodology rather than one firm’s house style. The Appraisal Institute standards of professional practice set requirements for the development and reporting of an appraisal, and identify the organization’s Body of Knowledge as an authoritative source of recognized methods and techniques. The income approach sits squarely inside that body of work.

Two methods do the converting. Direct capitalization handles one year. Discounted cash flow handles many.

Direct Capitalization: One Year, One Rate

Direct capitalization takes a single year of stabilized net operating income and divides it by a market capitalization rate. A property producing $560,000 of stabilized NOI, capitalized at 7 percent, indicates a value of $8,000,000.

The method assumes the income is representative of what the property will produce going forward. That assumption holds well when a building is fully leased, the leases run at market rates, and no large rollover is coming. It holds poorly when half the leases expire next year at rents far above or below market.

Direct capitalization is faster, easier to support with sales evidence, and easier for a reviewer to test. When it fits, appraisers use it.

Discounted Cash Flow: Many Years, Two Rates

Discounted cash flow projects the property’s income year by year across a holding period, usually five or ten years, then discounts each year back to present value. At the end of the period, the analysis adds a reversion, which is the projected sale price at the end of the holding period, discounted back as well.

The reversion is estimated using a terminal capitalization rate applied to the income in the year after the holding period ends. Two rates therefore appear in the analysis: the discount rate, which reflects the return an investor requires over the whole period, and the terminal rate, which reflects what a future buyer would pay.

Every projected year carries assumptions about rent growth, expense growth, renewal probability, downtime between tenants, and leasing costs. That is the strength and the weakness of the method. It can model a complicated property accurately, and it can also produce almost any answer if the assumptions drift.

When Appraisers Choose One Over the Other

The property picks the method. Direct capitalization suits stabilized property with steady income and market leases. Discounted cash flow suits property where the income pattern changes in a way one year cannot represent.

That includes a building in lease-up, a property with heavy lease rollover in the near term, leases with step rents or free rent periods, and any asset where major capital spending is scheduled. It also includes properties with a single tenant whose lease expires inside the projection period, since the value swing between renewal and vacancy is large.

Appraisers often develop both, then reconcile. When the two methods land far apart, that gap itself is informative and the report should explain it.

Five Assumptions Worth Checking Before You Rely on the Number

If you are reviewing an income approach, test these five inputs against the market rather than against the appraiser’s confidence:

  • Market rent. Is it supported by rent comparables, or borrowed from the subject’s own leases?
  • Vacancy and collection loss. Does it reflect the submarket, or does it assume the building stays full forever?
  • Operating expenses. Are they reconstructed to market levels, including a management fee and reserves?
  • The capitalization or discount rate. Is it derived from confirmed comparable sales, or lifted from a national survey?
  • Growth and rollover assumptions in a discounted cash flow. Are rent growth and renewal probability reasonable given the actual submarket?

Any one of those can move a value by hundreds of thousands of dollars. A good report lets you check all five without calling the appraiser. If it does not, calling the appraiser is the right next step.

Need an Income Analysis That Survives Review?

PahRoo builds income approaches lenders and reviewers can test, with every rate, rent, and expense assumption tied to market evidence.

Start a Commercial Appraisal

Frequently Asked Questions

What is the income approach in appraisal?

It is the method that converts a property’s expected income into a present value. Appraisers use it for income-producing property because buyers of such property are purchasing a stream of income rather than the building alone.

What is direct capitalization?

Direct capitalization divides one year of stabilized net operating income by a market capitalization rate to indicate value. It suits stabilized properties with steady income and leases at market rates, and it is easier for a reviewer to test.

What is the difference between direct capitalization and DCF?

Direct capitalization uses a single year of income and one rate. Discounted cash flow projects income across a holding period, discounts each year to present value, and adds a discounted reversion using a terminal capitalization rate.

When is discounted cash flow used?

When one year of income cannot represent the property, such as a building in lease-up, a property with heavy near-term lease rollover, leases with step rents or free rent, or an asset with scheduled major capital spending.

What is a discount rate in a commercial appraisal?

It is the rate of return an investor would require over the entire holding period, used to convert projected future cash flows and the reversion into present value. It differs from the capitalization rate, which applies to a single year of income.

Ask How the Income Approach Was Built, Not Just What It Concluded

PahRoo Appraisal & Consultancy develops direct capitalization and discounted cash flow analyses for commercial property in Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, with assumptions documented so a reviewer can follow them. See our commercial appraisal services, browse the wider range of our real estate appraisal services, or call 773-388-0003.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712