Category: News

Request a quote

Our blog

Latest news
& events

Cityscape Overview With Office Buildings And Residential Homes Background
What 2026 Fed Rate Cuts Mean for CRE

Commercial real estate investors, owners, and lenders are paying close attention to interest rate expectations as 2026 comes into view. There’s growing talk about possible Federal Reserve rate cuts, but for CRE, the real issue isn’t simply whether rates go down. It’s whether those cuts will actually make financing meaningfully easier.

That distinction matters. As a recent analysis from Realtor.com points out, lower Fed rates don’t automatically translate into cheaper commercial loans. Even if the Fed eases policy in 2026, mortgage rates, especially on the commercial side, may stay higher than many borrowers expect.

For anyone buying, refinancing, or planning an exit, understanding how Fed decisions actually filter through capital markets can make the difference between a smart move and an expensive misstep.

The 2026 Fed Rate Cut Outlook

Right now, markets are betting on one or two rate cuts in 2026, largely based on expectations that inflation continues to cool and economic growth slows. Those expectations show up in futures markets and investor positioning, but they aren’t guarantees.

It’s also worth remembering that the Fed sets short-term rates. Most commercial real estate loans, especially fixed-rate debt, are priced off longer-term benchmarks. That gap between policy and pricing is where a lot of confusion comes from.

Why Fed Rate Cuts Don’t Automatically Lower CRE Loan Rates

One of the most common misunderstandings in commercial real estate is assuming that Fed cuts lead directly to cheaper loans. In practice, CRE borrowing costs are influenced by several other factors, including:

  • 10-year Treasury yields, which anchor many fixed-rate loans
  • Credit spreads, which widen or tighten based on perceived risk
  • Lender balance sheets and risk tolerance
  • Property-level fundamentals, like occupancy, cash flow, and lease rollover

Even if the Fed cuts rates, lenders may keep spreads wide if uncertainty remains, especially for properties that are transitional, underperforming, or tied to weaker sectors.

Commercial Real Estate Sectors Most Impacted

Office Properties

Office continues to face the most pressure. Higher vacancies, shorter leases, and refinancing risk mean that rate cuts alone aren’t likely to reset values. Lenders are expected to stay cautious, with tighter underwriting and lower loan-to-value ratios.

Multifamily

Multifamily may see more direct benefits from improving rate conditions, particularly for stabilized assets in supply-constrained markets. That said, new deliveries in some areas could limit how much relief lower rates actually provide.

Retail and Industrial

Retail and industrial properties with strong tenants and long-term leases are generally in the best position. For these assets, any improvement from rate cuts is more likely to show up gradually, rather than through a sudden drop in cap rates.

What This Means for CRE Appraisal in 2026

Rates matter, but they’re only part of the picture. In 2026, values will still hinge on fundamentals such as:

  • Stability of net operating income
  • Lease rollover exposure
  • Asset quality and location
  • Lender appetite and available capital

Lower benchmark rates may take some pressure off, but properties with weak fundamentals will continue to face valuation challenges.

Strategic Considerations for CRE Owners and Investors

Why this matters: understanding the gap between Fed policy and real-world lending can help you avoid poor timing decisions.

  • Don’t assume refinancing gets easier just because rates are “supposed” to fall
  • Start planning early for loan maturities in 2026–2027
  • Run conservative scenarios when underwriting or refinancing
  • Use credible, well-supported appraisals when talking to lenders

In this cycle, preparation tends to matter more than predictions.

The outlook for 2026 points to measured optimism, not a rate-driven turnaround. Even if the Fed begins cutting rates, commercial real estate financing will remain selective and highly asset-specific.

For CRE owners and investors, success will depend less on headlines and more on fundamentals, realistic valuations, and proactive planning.

If you’re thinking about refinancing, selling, or approaching a loan maturity, understanding your property’s current market value is critical, especially in a shifting rate environment.
Get clarity before conditions change.

Chicago Housing Smart Market Signals August 2025

Chicago housing market Aug 2025 update: buyers are gaining leverage as inventory rises and sales momentum cools across Cook, DuPage, Lake, and Will Counties. If you’re planning to buy, sell, or invest, this month’s numbers point to real opportunities.

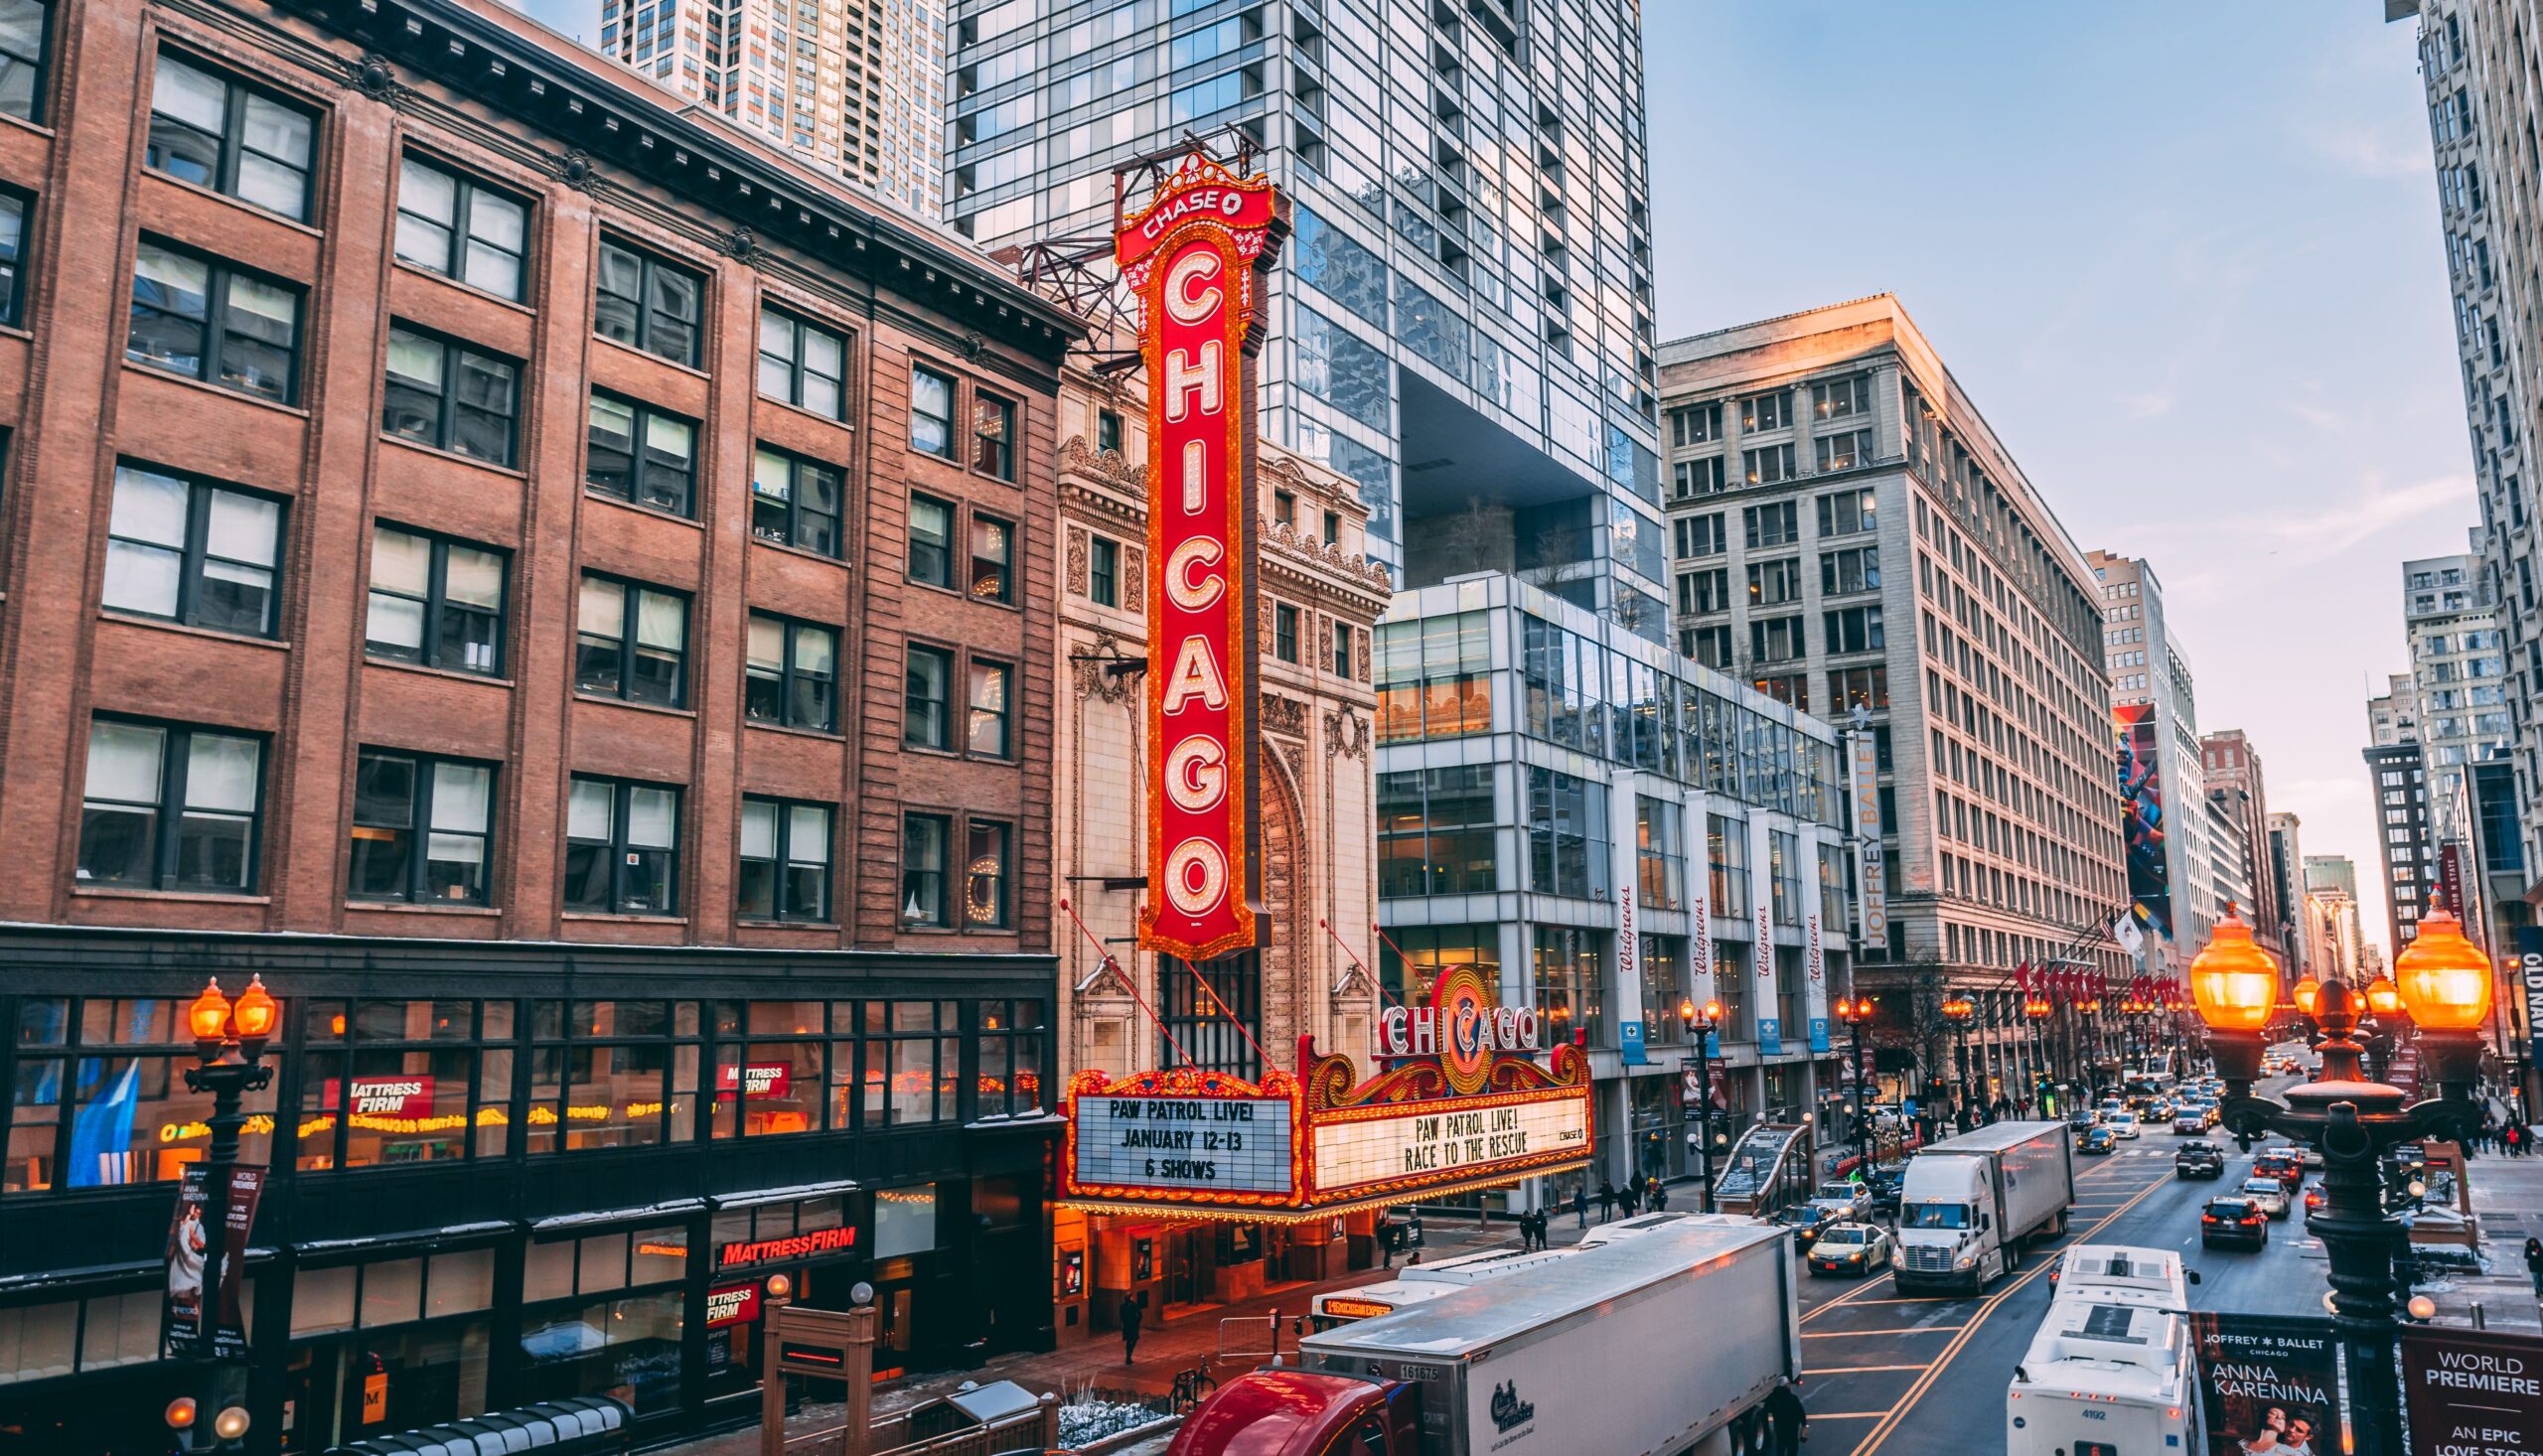
Chicago Theater sign in downtown Chicago with busy street traffic and historic buildings at sunset

Chicago Housing at a Glance for August 2025
  • Buyer advantage grows: Pending sales are down year over year across all four counties, easing competition.
  • County differences matter: DuPage remains the strongest on pricing, Cook offers the most affordability, Will shows the largest inventory build.
  • Condo stability in the city: Cook County condo inventory has tightened compared with last year, contrasting with suburban trends.
  • Rates keep pressure on budgets: The 30-year fixed hovers in the mid-6% range, moderating demand but opening room to negotiate.

County Snapshots
Cook County

Most affordable entry point. Median list price around the mid-$300Ks, with the largest share of total inventory in the metro. Condo inventory has declined year over year, making the attached market comparatively tighter for buyers.

DuPage County

Strongest pricing resilience. Median list price leads the region. Inventory has contracted versus last year, keeping competition relatively firm for well-presented homes.

Lake County

Balanced but steady. Pending activity shows smaller year-over-year declines than Cook or DuPage, signaling relatively stable demand in select submarkets.

Will County

Most selection for buyers. Active inventory is up sharply year over year while absorption cooled. Sellers should price to the market and prepare for longer days on market.

Mortgage Rates & Affordability

With the 30-year fixed around 6.58%, monthly payments remain elevated versus the recent past. For prepared buyers, this environment can translate to less bidding pressure and better terms.

What This Means for You

  • Buyers: Compare more homes, negotiate repairs/credits, and lock financing proactively.
  • Sellers: Price right from day one; consider strategic concessions instead of later price cuts.
  • Investors: Normalizing conditions after 2020–2024 create more rational entry points.

Why an Appraisal Matters Right Now

In a shifting market, precise value is your edge. A professional appraisal from PahRoo Appraisal & Consultancy, LLC gives you a data-driven view of true market value before you list, bid, refinance, or strategize.

Explore Residential Appraisal Services  |  Investor Consulting Solutions  |  Contact PahRoo

FAQs

Is Chicago a buyer’s market in August 2025?

Conditions tilt toward buyers as absorption rates trend lower and months of supply rise versus last year. Well-priced homes still move, but negotiation power has improved.

Which county is most affordable?

Cook County typically offers the lowest median list price among the four major counties, providing more accessible entry points for first-time buyers.

What should sellers do right now?

Lead with market-right pricing, optimize presentation, and consider targeted concessions (closing credits or repair budgets) to protect your timeline and net.

Need clarity before you act? Book an appraisal with PahRoo to move forward with confidence in the Chicago housing market Aug 2025.

U.S. Economy Now: Its Effect on YOUR Real Estate

How the 2025 U.S. Economy Impacts Real Estate Values

The U.S. economy is constantly evolving, and its changes directly affect real estate markets nationwide. Homeowners and investors need to stay informed to make smart property decisions. In this post, we explore key economic trends in 2025 and how they influence U.S. real estate values and investment opportunities.

You are wondering what all this tariff talk of the POTUS has to do with my property?

You might be wondering: what does all the tariff talk from the POTUS mean for my property? Recent developments suggest that global backlash could impact your finances. While many hope for improvements, international pressures are mounting. Current trends indicate that the U.S. dollar may depreciate by 15–20%, a sharp contrast to the previous environment of strong economic growth, low inflation, and favorable interest rates that attracted investors to U.S. assets.

The depreciation of the U.S. dollar has a nuanced impact on the U.S. real estate market, presenting both opportunities and challenges. One of the primary effects of a weaker dollar is that it increases the purchasing power of foreign investors, making U.S. real estate more attractive to them. This often leads to increased demand, particularly in prime locations and popular markets, which can drive up property prices.

How a Weaker Dollar Affects Real Estate

A weaker U.S. dollar has both opportunities and challenges for the real estate market:

  • Attracts foreign investors: A lower dollar increases purchasing power for foreign buyers, making U.S. real estate more appealing. Prime markets often see higher demand, which can drive property prices up.
  • Foreign capital influence: Many investment firms deploy a large portion of funds from overseas. A lower exchange rate encourages increased investment in U.S. properties.

On the other hand, a falling dollar may lead to higher interest rates as central banks try to stabilize the economy. Higher mortgage rates can reduce affordability for domestic buyers, slowing property value growth. Real estate projects financed with short-term debt are particularly sensitive to interest rate fluctuations. Risk management strategies, such as purchasing rate caps, can help protect investments.

Inflation and Construction Costs

Inflation often follows a weaker dollar, increasing construction and labor costs. This can raise the value of existing properties since new builds become more expensive. Multi-family housing, for example, has seen rents rise faster than construction costs, boosting asset values. However, local market fundamentals including employment, population growth, and industry health, ultimately determine real estate outcomes.

Global Investment Flows

Currency fluctuations also influence foreign investment:

  • Strong dollar: U.S. properties become expensive for foreign buyers, reducing demand.
  • Weak dollar: Enhances affordability for investors with stronger home currencies, increasing demand.

These dynamics affect property prices, investment returns, and rental income when converted back to investors’ home currencies.

Key Takeaways
  1. Dollar depreciation often attracts more foreign investment, potentially driving up prices in sought-after markets.
  2. Rising interest rates and mortgage costs may suppress domestic demand.
  3. The ultimate impact on real estate depends on currency movements, inflation trends, financing structures, and local economic conditions.

Since real estate is one of your largest assets, staying informed is crucial. Working with PahRoo Appraisal & Consultancy experts ensures you make strategic, informed decisions.

Understanding the 2025 U.S. economy is key to making smart real estate decisions. For insights into how zoning laws and property policies impact values, read our blog on The Hidden Power of Your HOA. For official market data, visit the Federal Reserve Economic Data (FRED).

We’re here when you need us.  For nearly 30 years, PahRoo Appraisal & Consultancy has been helping clients make confident decisions today that transform tomorrow and tomorrow’s tomorrow. Contact us today, and our team will guide you through the housing market with expert advice.

What Rising Housing Inventory Means for Sellers

Headlines say housing inventory is rising, and nationally that is true. For-sale supply has recovered across much of the South and West, and buyers there have options again. But a seller does not sell into the national market. You sell into your metro, your county, and your block. So before you pick an asking price, look at the local supply picture. A few specific numbers show where you actually stand.

By the end of this article, you’ll know:

  • How supply shifts bargaining power between sellers and buyers
  • The four numbers an appraiser checks before any listing conversation
  • Why Chicago runs against the national trend in 2026, and what that means for your price

How Housing Inventory Sets Your Bargaining Power

Supply decides who negotiates from strength. When few homes compete for many buyers, sellers set terms. When listings pile up, buyers slow down, compare, and ask for more. The 2026 market shows both conditions at once, depending on where you stand. The Realtor.com 2026 Spring Seller Survey found 83% of potential sellers expect their asking price or more. Yet 39% also expect to make concessions, up from 30% a year earlier.

Those two numbers together tell the real story. Sellers remain confident, but they can feel buyers regaining footing where supply has grown. The typical home now spends 57 days on market. A seller who prices past what local supply supports does not just wait longer. They often give the difference back later as price cuts and credits.

The Four Numbers an Appraiser Checks Before You List

You do not need a terminal full of data. Four figures, all available from any good agent or appraiser, describe your local supply picture.

Months of supply. How long current inventory would take to sell at the current sales pace. A common rule of thumb treats roughly six months as balanced. Well under that favors sellers; well over favors buyers.

Days on market. How fast comparable homes go under contract. Falling days signal demand outrunning supply. Rising days mean buyers have alternatives, and your price has to earn attention.

Sale-to-list ratio. What homes actually fetch against their asking prices. Treat this one with care, because the ratio only reflects homes that sold. Our June 2026 Chicago market report walks through how a strong ratio can mislead when overpriced listings simply sit unsold outside the statistic.

New listing flow. Whether fresh competition keeps arriving. Inventory can look tight today and loosen within a season if new listings outpace sales. The direction matters as much as the level.

Chicago Runs Against the National Trend

Here is where geography changes the answer. Realtor.com’s Market Clock analysis found only about a quarter of the 50 largest metros remain seller’s markets in 2026, concentrated in the Midwest and Northeast, while all eight buyer’s markets sit in the South or West. Chicago made the short list of peak seller markets, alongside Hartford and Indianapolis.

So while sellers elsewhere adjust to growing supply, Chicago-area sellers still work with scarce inventory and steady demand. Even here, though, the picture splits by county. Our June report found Cook County prices holding on scarce supply while the collar counties each tell a different story. Two sellers thirty miles apart can face opposite markets in the same month. That is exactly why the national headline, whichever direction it points, should never set your asking price.

A tight market also rewards attention, not complacency. Watch the new listing flow in your area through the spring. If competition arrives faster than homes sell, the advantage narrows, and the sellers who priced on evidence keep their edge while the optimists chase the market down.

Your Tax Assessment Is Not Your Market Value

One more number confuses sellers in this market: the assessed value on the property tax bill. When assessments climb, owners often read the increase as proof their home is worth more. Sometimes it is. But an assessment is a mass-produced estimate for taxation, set on a multi-year cycle, and the City of Chicago’s next citywide reassessment lands in 2027. It is not an offer, and buyers do not pay it.

The gap cuts both ways. A home can sell well above its assessed value in a tight market, or sit unsold below it when the assessment overshoots. If your assessment looks higher than what nearby sales support, that is not a pricing signal. It may instead be grounds for an appeal, which is a separate conversation an independent appraisal can also support.

Read the Market, Then Price the House

Put the sequence in the right order. First, learn what supply and demand look like on your block, not in the headlines. Then find out what your specific home is worth inside that picture. A pre-listing appraisal does both jobs at once. It weighs the local supply data, selects true comparable sales, and gives you a defensible number before the first buyer walks in. In a market where one county favors sellers and the next one does not, that number is the difference between pricing with evidence and pricing with hope.

Is your asking price built on supply data or hope?

A pre-listing appraisal reads your block’s inventory, demand, and comparable sales, then gives you one defensible number to list against.

Get Your Listing Number

Frequently Asked Questions

What does rising housing inventory mean for sellers?

More inventory means more competition and more buyer bargaining power. In 2026, 39% of potential sellers expect to make concessions, up from 30% a year earlier, largely because supply has recovered in parts of the country. Where inventory remains scarce, including much of the Midwest, sellers still hold the stronger position.

What is months of supply, and what number favors sellers?

Months of supply measures how long the current inventory of homes would take to sell at the current sales pace. A common rule of thumb treats about six months as a balanced market. Readings well below six months favor sellers, while readings well above favor buyers.

How is the Chicago market different from the national trend in 2026?

While supply has grown across much of the South and West, Realtor.com’s 2026 Market Clock analysis named Chicago among the strongest seller markets in the country, driven by tight Midwest inventory. Conditions still vary by county, so sellers should check supply data for their specific area before pricing.

Does a higher tax assessment mean my home is worth more?

Not necessarily. An assessment is a mass estimate produced for taxation on a multi-year cycle, not a market price. Homes regularly sell above or below their assessed values. If your assessment exceeds what comparable sales support, it may be grounds for a property tax appeal rather than a higher asking price.

Which numbers should I check before listing my home?

Four figures describe your local supply picture: months of supply, days on market, the sale-to-list ratio, and the flow of new listings. Together they show whether sellers or buyers hold the advantage in your area. A pre-listing appraisal then places your specific home’s value inside that picture.

An Appraisal That Reads Your Block, Not the Headlines

PahRoo Appraisal & Consultancy has valued Chicago-area homes for more than two decades, led by an appraiser holding both MAI and SRA designations. Whether you need a residential appraisal before listing or broader appraisal services for an estate, divorce, or tax matter, we put a defensible number behind the decision so the market’s noise stays outside it.


Property updates adding value in the Washington housing market 2025
Washington Chaos: A Gift for Homeowners & Investors

Chaos in Washington just gave homeowners and Real Estate investors a Gift.

Yes, political turmoil rattled the bond markets.  Headlines screamed “uncertainty,” yields plunged, and analysts clutched their pearls. But here’s the twist: what spooked Wall Street might just bless Main Street—especially if you’re looking to buy a home.

Let’s break it down.
When investors get nervous, they run for safety, and U.S. government bonds are their security blanket of choice. That demand pushes bond prices up and yields (aka long-term interest rates) down. And guess what mortgage rates are tied to? You got it: bond yields. So while the talking heads were arguing over government shutdowns, leadership shakeups, or fiscal brinkmanship, the 10-year Treasury yield quietly dropped—and mortgage rates followed suit.

Here’s what that means for you:

  • Lower Rates = More Buying Power: A 0.5% drop in mortgage rates could save you tens of thousands or hundreds of thousands over the life of a loan. Or, more immediately, it might turn that “just out of reach” house or investment property into something you can actually afford.
  • More Room for Negotiation: Sellers are already dealing with a slower market and rising days on market (a measure of market activity). Lower rates bring hesitant buyers off the sidelines—and that gives you leverage before competition fully ramps up.
  • A Window, Not a Door: These lower rates might not stick around forever. If inflation flares back up or markets calm down, expect rates to rise again. Timing matters especially in 2025.
  • Lower Rates = More Savings  A drop in mortgage rates also opens up your possibility to refinance now to lower your carrying cost of debt, and that lower cost of your mortgage can be used to reinvest in updating your property, investing in another property, or just saving up for your much-deserved vacation!

Look, political chaos isn’t fun. But sometimes, macro uncertainty creates micro opportunity. The key is knowing where to look—and how to act before the window closes.

In short: Wall Street panicked.

You might get a house OR an investment property out of it. Funny how economics works, huh? Is economic uncertainty impacting your property value?  We’re here to help you make confident decisions today that transform tomorrow!

Contact us today for personalized guidance on navigating the Washington housing market 2025. Don’t forget to follow us on Facebook, Instagram, and X for the latest real estate news and tips!

Spring Inventory Surge: What It Means for Buyers & Sellers in 2025


Spring Inventory Just Spiked—Here’s What That Really Means for Buyers and Sellers

No, the market isn’t crashing. However, something big is happening: inventory just surged by 17,000 homes in a single week—the sharpest jump in nearly three years.

For the first time in a long time, buyers have more options. Meanwhile, sellers face more competition than before. Whether you’re diving in or just watching from the sidelines, here’s what this shift means and how to play it smart.


Why Inventory Is Suddenly Climbing

This isn’t a fluke. It’s the result of a few key trends converging:

Rates are still high-ish – Mortgage rates dipped slightly; nevertheless, they remain high enough to give buyers pause. As a result, slower demand means homes are sitting longer.

Sellers are done waiting – Many are accepting that this is the new normal. Therefore, they’re listing now rather than holding out for 2021 prices.

Longer time on market = more active listings – With fewer bidding wars, homes are stacking up.


What Buyers Should Know

This shift is your chance to breathe. In fact, it finally gives buyers a little more control.

You’ve got options – More listings means more room to compare, negotiate, and not waive every contingency.

Slightly better leverage – Some sellers are open to concessions: price cuts, closing help, or repair credits.

However, don’t sleep on it – If rates drop again, competition could heat back up fast.


What Sellers Should Do Now
A shifting market isn’t bad. It just means you can’t rely on chaos to sell your home.

Price smart – Today’s buyer is savvy and spoiled for choice. Overprice it, and they’ll scroll right past⁷.

Stand out – Good staging, strong photos, and solid marketing are now your secret weapons.

Stay calm – Homes are still selling, it’s just not a bidding war on every block anymore.


Bottom Line
This spring isn’t a meltdown or a miracle. It’s a moment of balance and that’s a good thing.

The market is evolving. Strategy matters more than ever. Whether you’re buying, selling, or investing, understanding the why behind the numbers will always put you ahead.

Want help reading the signs in your local market?

Reach out—we’re here to help.


Sources:
Altos Research via HousingWire, April 2025: “Biggest inventory spike in 3 years” 

Freddie Mac Mortgage Market Survey, April 2025 

CoreLogic MarketPulse Report, Q1 2025 

Redfin Market Trends Report, April 2025 

National Association of Realtors (NAR), 2025 Buyer & Seller Survey 

Mortgage News Daily Rate Tracker, April 2025 

Realtor.com Seller Strategy Guide, 2025
Logistics cost pressure 2024: warehouse and supply chain operations
Trends in the Chicago Real Estate Market: Insights for 2024

In 2024, businesses across the U.S. are facing logistics cost pressures that affect every stage of transportation and delivery. Rising fuel prices, labor shortages, and global supply chain disruptions have combined to create a challenging environment. Companies must understand these dynamics to optimize their operations and maintain profitability. Accurate insight into these trends also helps property owners and investors in logistics-related real estate make informed decisions.

Factors Driving Logistics Cost Pressure 2024
  • Rising Fuel and Transportation Costs
    Fuel prices have surged in 2024, directly impacting the cost of shipping goods over long distances. Companies are forced to adjust pricing or absorb expenses, affecting profitability.
  • Labor and Staffing Challenges
    The logistics industry is experiencing shortages of qualified drivers and warehouse staff. Higher wages and overtime requirements increase overall operating costs.
  • Supply Chain Delays and Global Disruptions
    Global events, port congestion, and fluctuating demand contribute to unpredictable delivery times and higher costs, further pressuring logistics budgets.
Strategies Businesses Can Adopt
  • Optimize Delivery Routes and Warehouse Efficiency
    Using route planning software and automated warehouse systems can reduce time, fuel usage, and costs.
  • Leverage Technology for Cost Forecasting
    Real-time analytics, AI-driven forecasting, and inventory management tools help companies anticipate and manage expenses.
  • Negotiate Contracts with Carriers
    Long-term agreements and flexible terms with carriers can mitigate sudden cost spikes and improve stability.
Impact on the Broader Economy
  • Logistics cost pressures ripple through the entire economy:
  • Increased transportation expenses often lead to higher prices for goods and services.
  • Businesses may adjust pricing strategies or shift sourcing locations to manage costs.
  • Supply chain challenges can affect delivery speed, impacting consumer satisfaction and market competitiveness.

Understanding logistics cost pressure 2024 is crucial for businesses, investors, and property owners. While some sectors are recovering, strategic planning is necessary to mitigate challenges, optimize operations, and maintain profitability. Accurate insight into these trends provides a competitive advantage in the evolving logistics landscape.

Stay ahead in the evolving logistics market. Contact PahRoo Appraisal & Consultancy today to understand how current trends impact your logistics-related investments and property valuations.

NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712