Tag: Dallas real estate appraisals

Request a quote

Our blog

Latest news
& events

How Do Appraisers Compare Homes That Aren’t Alike?

When it comes to determining a home’s market value, appraisers often face the challenge of comparing properties that don’t look much alike. You might wonder: How can an older brick bungalow be compared to a newer two-story home down the street? The answer lies in a systematic process called adjustments, which ensures that differences between homes are accounted for fairly.

Real estate valuation illustration with a hand holding a small house in front of bigger houses

Why Appraisers Need Comparables

Appraisers typically use the sales comparison approach, which relies on analyzing recent sales of comparable homes (“comps”). The problem? Perfect matches rarely exist. Even in the same neighborhood, homes can differ in size, style, age, and condition.

That’s why appraisers make careful adjustments to bring the sales prices of those comps closer in line with the subject property.

Adjusting for Home Differences

Adjustments allow an appraiser to create an “apples-to-apples” comparison. For example, if the comparable home has a renovated kitchen and the subject property does not, the appraiser reduces the comp’s sale price to reflect that difference.

Similarly, if the subject property has a larger lot than the comparable home, the appraiser adds value to the comp’s price. The goal is to estimate what each comparable would have sold for if it were more like the subject property.

Key Factors That Influence Adjustments

Location

Homes in more desirable areas: closer to schools, parks, or transit often sell for more. Appraisers weigh neighborhood differences heavily.

Size and Layout

Square footage matters, but so does layout. An open-concept design may command more value than a segmented floor plan of the same size.

Age and Condition

Newer homes or recently updated properties generally sell for more. Older homes in need of repairs are adjusted downward in comparison.

Upgrades and Amenities

Extra features such as finished basements, fireplaces, or updated bathrooms impact value. Appraisers account for these when comparing homes.

Why Professional Expertise Matters

Appraising is both an art and a science. While market data provides structure, appraisers also rely on experience and professional judgment to balance differences. This expertise ensures a fair and credible opinion of value, whether you’re buying, selling, refinancing, or settling an estate.

For more on professional appraisal standards, visit the Appraisal Institute.

FAQ: How Do Appraisers Compare Homes That Aren’t Alike?

Q: How do appraisers compare homes that aren’t alike?
A: Appraisers adjust for differences like size, age, condition, and features when comparing properties. Even if homes aren’t identical, these adjustments help ensure a fair and accurate valuation based on market data and professional judgment.


Final Thoughts on Comparing Unalike Homes

Even when two houses don’t look alike, appraisers use adjustments to create a level comparison. By analyzing location, size, condition, and amenities, they ensure the valuation reflects the home’s true market worth.

If you’re in Chicago or Cook County and need an accurate appraisal, trust PahRoo Appraisal & Consultancy to deliver clear, reliable valuations.

Request an Appraisal

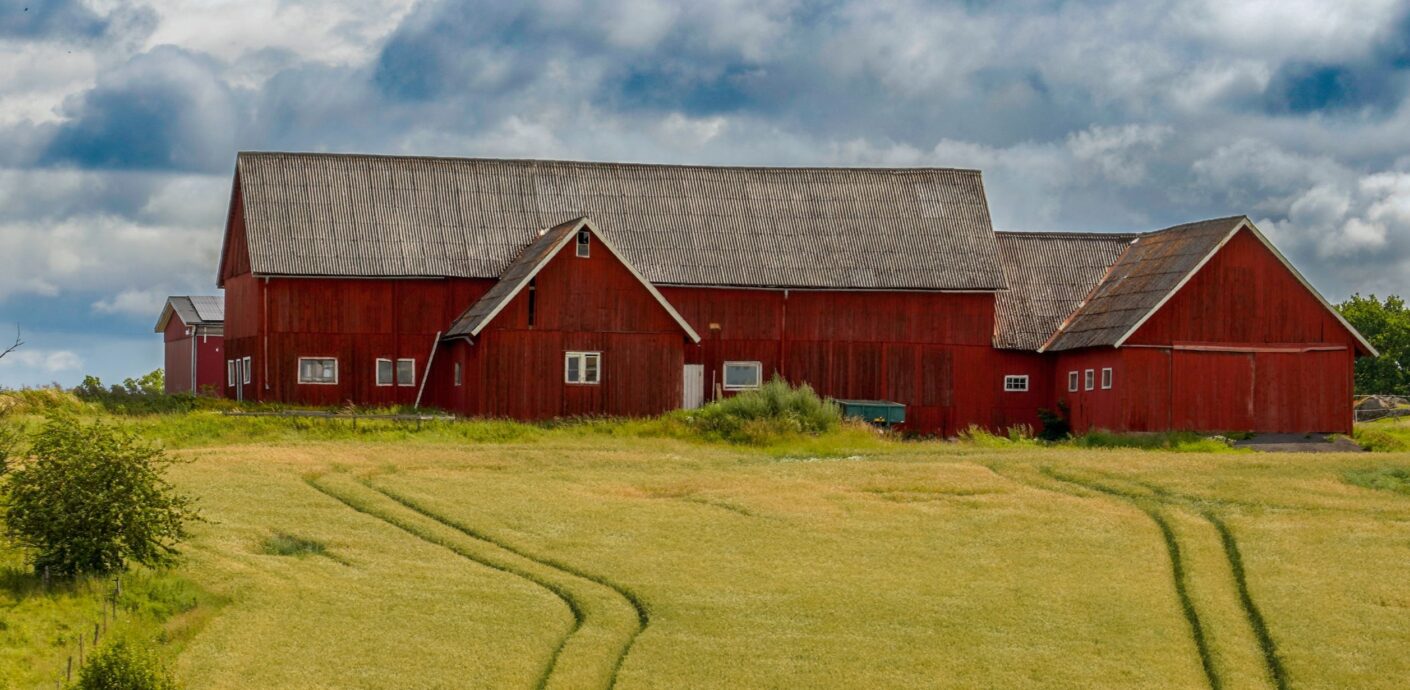
Outbuildings on a rural home that an appraiser must describe and analyze
Rural vs. Urban Appraisals: Why They’re Completely Different Beasts

Most talk about rural vs urban appraisals stops at the obvious point: the country has fewer sales. The harder part shows up on a house with ten acres, a pole barn and a horse shelter. That property raises questions a city condo never does. Which buildings count? How far can the appraiser reach for comps? And will a lender treat it as a home at all?

By the end of this article, you’ll know:

  • What Fannie Mae actually allows when rural comps are distant or old
  • How the outbuildings on a property can turn a value question into an eligibility question
  • What lenders and estate attorneys should check in a report on a home with acreage

Where Rural vs Urban Appraisals Actually Split

In a dense market the comps are close, recent and alike. Same block, same building type, sold this year. The analysis is mostly about small differences.

A home on acreage breaks that pattern. Fannie Mae’s Selling Guide says it plainly. Rural properties often have large lots, and rural locations can be relatively undeveloped. So there may be a shortage of recent, truly comparable sales nearby.

So the guide allows the appraiser to reach. If the best indicators of value sit a considerable distance away, those sales can be used when they produce credible results. The report has to explain why they were chosen. Every distance also gets stated in miles with a direction, measured in a straight line.

That explanation is the whole game. On a city appraisal, the comps mostly speak for themselves. On an acreage appraisal, the reasoning carries the value.

Older Sales, Farther Sales, and the Explanation That Comes With Them

The general rule is comparable sales closed within the last 12 months. But the guide carves out rural markets directly. Where sales activity is minimal, the appraiser may not find three truly comparable sales from the last year. Then older sales are acceptable, if the report explains why they were used.

Two other limits still hold. There must be at least three closed comparables. Sales from a competing market area are fine. But the appraiser cannot stretch the neighborhood boundary just to swallow the comps. The report has to say the sales come from a competing area and explain how that area compares.

When nothing truly comparable exists, the guide still allows the best available sales if the analysis is documented. What it does not allow is silence. An acreage report with distant or dated comps and no commentary draws a reviewer’s questions.

The Barn Question

This is where acreage appraisals differ most from anything in a city. Fannie Mae’s outbuildings guidance sorts them into three groups, and each one reads differently.

Minimal outbuildings, such as small barns or stables of relatively insignificant value, are acceptable. The comparable sales just have to show they are typical for residential properties in the area. An atypical minimal outbuilding is acceptable too, as long as the analysis gives it little or no contributory value.

Then there are significant outbuildings: silos, large barns, storage areas, facilities for farm-type animals. Here the guide changes the question. Their presence may indicate the property is agricultural in nature. Then the lender must determine whether it is residential, whether or not the appraiser assigns the buildings any value.

That last clause matters. A report that gives a large barn zero value has not settled the eligibility question. It has only settled the value question.

What a Lender Should Read Before the File Moves

If you are underwriting a home on acreage, four checks save a round of conditions later.

First, find the outbuildings in both places they belong. The guide expects them described in the Improvements section and in the Sales Comparison Approach section. Not in one and missing from the other.

Second, decide which of the three groups each building falls into. A pole barn for a riding mower and a machine shed for a working operation are different conversations. That holds even at the same square footage.

Third, read the comp commentary before the adjustment grid. Distance, age and competing-area sales all need an explanation. That explanation is where a weak report shows itself.

Finally, keep clarification and pressure separate. Asking the appraiser to describe an outbuilding more fully is fair. Asking for a different number is not, and a good appraiser will decline.

Estates With Acreage Run Into the Same Problems

Estate work adds a date to all of this. The IRS values a gross estate at fair market value as of the date of death. Not at what the decedent paid, and not at what the property was worth when acquired.

For a family property with land and outbuildings, that usually means a retrospective assignment in a thin market. The comp search reaches back to the date of death, not forward from today. It may also reach farther across the map than anyone expected.

The outbuildings need the same care they get in lending. What a barn cost to build and what it adds to market value are different numbers. Heirs often assume the first one. When siblings split a property or one buys out the others, that gap turns into the argument.

Tell the Appraiser About the Outbuildings Up Front

Most of the delays on acreage assignments start at the order. Tell the appraiser the acreage. List every outbuilding and what it is used for. Say whether anything on the property supports a business or animals. Mention whether the house runs on a well and septic, too.

None of that changes the value by itself. It changes the scope of the comp search and the outbuilding analysis. It also lets the appraiser flag an eligibility question before the report goes out, rather than after an underwriter finds it.

Appraising a Home With Land and Outbuildings?

Tell us the acreage, what sits on it, and who will read the report. We will scope the comp search and the outbuilding analysis before anyone sets foot on the property.

Start the Order

Frequently Asked Questions

How far can an appraiser go for comps on a rural property?

Fannie Mae sets no fixed mileage. If the best indicators of value are a considerable distance away, they can be used when they produce credible results. The report must explain why they were chosen and state each distance in miles with a direction.

Can a rural appraisal use sales older than 12 months?

Yes, when the market has minimal sales activity. Fannie Mae allows older comparable sales in rural areas as long as the appraiser explains why they are being used. At least three closed comparables are still required.

Does a barn add value to a house?

Sometimes. A barn adds what the market will pay for it, which is often far less than what it cost to build. Fannie Mae’s guidance also has the appraiser give an atypical minor outbuilding little or no contributory value.

Can a home with large outbuildings get a conventional mortgage?

It depends on the lender’s determination. Under Fannie Mae’s guidance, silos, large barns or animal facilities may indicate an agricultural property. Then the lender must decide whether it is residential in nature.

Does an estate with acreage need a different kind of appraisal?

It needs a value as of the date of death, which the IRS uses for estate property. With land and outbuildings, that usually means older and more distant comparable sales. It also means a careful look at what each building actually contributes.

Residential Appraisals Beyond the City Grid

PahRoo Appraisal & Consultancy works out of Lincolnwood, with operations in Dallas, Philadelphia, Phoenix and Naples. Michael Hobbs, MAI, SRA, signs every report. Our residential appraisal team handles homes on acreage as well as city properties, including the outbuildings that come with them. You can also read how a home appraisal runs from order to delivery.

Small investment property of the kind where real estate investment mistakes get expensive
Real Estate Investment Mistakes an Appraiser Keeps Seeing

Most lists of real estate investment mistakes are written by people who sell properties. This one comes from the other side of the closing table. Appraisers get called in when deals are underwritten, contested, refinanced, and unwound, so we see where investors actually lose money. The pattern is consistent. Almost every expensive mistake traces back to the same root: acting on a number nobody verified.

By the end of this article, you’ll know:

  • The six valuation mistakes that cost investors the most, and how each one starts
  • Why online estimates and listing prices fail hardest on investment property
  • Which deals justify an independent appraisal even when no lender requires one

The Real Estate Investment Mistakes That Start With a Bad Number

The first and most common of the real estate investment mistakes is treating price as value. A listing price is a seller’s ambition. An online estimate is an algorithm’s guess. It is built from public records that miss condition, layout, and everything behind the front door. Neither is an opinion of market value.

Investment properties break automated models even faster than owner-occupied homes do. Rents, expenses, and condition drive the math, and none of those live in public data. An investor who underwrites a deal on an algorithm’s number is building the whole return projection on sand. Standards-based valuation exists for exactly this reason. It is why appraisers work under USPAP rather than under whatever the listing says.

Underwriting Yesterday’s Market

The second mistake is running today’s deal on last year’s assumptions. Rents soften and cap rates move. A comparable sale from eighteen months ago may describe a market that no longer exists. We covered how this plays out for income property in our article on commercial appraisals in a shifting market. The short version applies to a two-flat as much as an office tower: value has a date on it.

Before you commit, ask what the market has done since each of your comparables closed. Then ask whether your rent and expense assumptions reflect current conditions or hopeful ones. If the deal only works with yesterday’s numbers, it does not work.

Missing What Drags Value Down

Investors are good at spotting upside and bad at pricing decay. Deferred maintenance, an obsolete layout, a flood zone designation, or environmental issues next door all pull value below what the surface suggests. These are exactly the items a drive-by look and a listing photo tour will miss.

So do the unglamorous work. Get the inspection, pull the flood maps, and walk every unit. When a defect turns up, price it as the market would, not as a contractor’s repair quote. Buyers discount problems by more than the cost to fix them.

Confusing Renovation Cost With Value

Here is the mistake that ruins flip math. Spending $80,000 on a renovation does not add $80,000 of value. Appraisers measure contributory value, meaning what the market pays for the improvement. That figure routinely lands below cost, especially for over-improvements that push a property past its neighborhood ceiling.

We walked through this discipline for green property features, and it governs every upgrade. Think granite in a C-class rental, a luxury bath in a starter-home block, or an addition that makes the biggest house on the street bigger. Budget renovations against what comparable renovated properties actually sell for, not against what the work costs.

Skipping the Appraisal Because No Lender Made You Get One

Cash purchases, off-market deals, seller financing, and partnership buy-ins share a dangerous feature. Nobody in the transaction is required to check the value. The lender’s appraisal, whatever its limits, at least forces one independent look. Remove it and the only value opinion in the room belongs to the person selling to you.

These are precisely the deals where an independent appraisal earns its fee. It is also the cheapest dispute insurance available. Partnership stakes, buyouts, and estate transfers priced without a documented value tend to resurface in litigation years later, when reconstructing the number costs far more.

Treating Taxes and Insurance as Fixed Costs

The last mistake hides in the expense column. Property taxes are not frozen at the seller’s bill. A sale and a reassessment can move them, and in high-tax markets like Cook County that swing can erase a thin margin. Insurance has its own trap. Replacement cost and market value are different numbers, and underinsuring a building to its purchase price can leave a gap when something burns.

The fix is professional, not heroic. Have your CPA model the tax picture, and ask an insurance professional to quote replacement cost properly. If the assessment comes in high after you buy, a tax appeal supported by an appraisal is a real option, not a lost cause.

Verify the Number Before You Wire the Money

Every mistake above has the same antidote: independent verification before commitment. Underwrite on current data. Price the defects and the improvements at market rather than at cost, and put a real appraisal behind any deal where no one else will check the value. The investors who last are rarely the boldest. They are the ones whose numbers were right.

Check the Number Before You Commit

PahRoo appraises residential and commercial investment property across Chicago, Dallas, Philadelphia, Phoenix, and Naples, so your deal math starts from a value you can defend.

Request an Investment Appraisal

Frequently Asked Questions

What is the biggest mistake new real estate investors make?

Acting on an unverified number. Whether it is a listing price, an online estimate, or a seller’s rent roll, new investors routinely underwrite deals on unchecked figures. Every downstream calculation inherits that error.

Is an online estimate good enough for an investment purchase?

No. Automated estimates miss condition, interior quality, actual rents, and expenses, which are the inputs that drive investment value. They are a starting point for curiosity, not a basis for wiring money.

Do I need an appraisal if I’m paying cash?

That is when you need one most. With no lender in the deal, no one is required to verify the value. The only opinion in the room belongs to the seller. An independent appraisal is the check the transaction otherwise lacks.

Will my renovation add its full cost to the property’s value?

Usually not. Appraisers measure contributory value, meaning what buyers actually pay for the improvement, which often runs below cost. Over-improvements beyond the neighborhood’s ceiling return the least.

Can property taxes change after I buy an investment property?

Yes. Reassessment can move the bill well above what the seller paid, which matters in high-tax markets. Model the tax picture with your CPA before closing. A high assessment can also be appealed with appraisal evidence.

Need an Independent Appraisal?

PahRoo Appraisal & Consultancy values investment property across Chicago, Dallas, Philadelphia, Phoenix, and Naples, from residential two-flats to commercial buildings. Led by Michael Hobbs, our MAI and SRA designated team gives investors the number before the market gives them the lesson.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712