Category: Real Estate

Request a quote

Our blog

Latest news
& events

Newly built commercial property valued through a cost approach commercial appraisal
The Sales Comparison and Cost Approaches in Commercial Appraisal

Two of the three approaches to value get less attention than they deserve. The income approach dominates most commercial reports, so brokers and lenders tend to skim the rest. That is a mistake on the wrong property. A cost approach commercial appraisal is often the only credible path to value on a new building or a special-use facility. And the sales comparison approach tells you whether a buyer’s likely price lines up with what the income says. So here is how each one works, when it leads, and what to check when you read one.

By the end of this article, you’ll know:

  • How the sales comparison approach is adapted for commercial property with thin data
  • What a cost approach actually adds up, and how depreciation is measured
  • When each approach should carry the weight, and how to check that it does

How the Sales Comparison Approach Works for Commercial Property

The sales comparison approach values a property by what similar properties sold for, adjusted for the differences. Residential appraisers usually have several nearby sales from the last few months to work with. Commercial appraisers rarely have that luxury. A submarket may produce four flex-industrial sales in two years, and none of them is a twin of the subject.

So the method bends to fit the data. The search area widens, sometimes to the whole metro. The time window stretches too. Then a market conditions adjustment has to account for price movement between the comparable’s sale and the effective date. The unit of comparison also changes with the property type: price per square foot for industrial and office, price per unit for apartments, price per net rentable square foot for self-storage, price per key for hotels.

Adjustments are where the work lives. Location, size, age and condition, construction quality, ceiling height, loading, parking ratio, and lease status all get weighed. Where possible, paired sales or market participants support each adjustment, not the appraiser’s instinct. A grid of round-number adjustments with nothing behind them is the first thing a reviewer questions. Our overview of the three approaches to value covers how they fit together. This piece goes deeper on the two that get skipped.

One more commercial wrinkle. A sale of a leased building reflects the leases, not just the bricks. A comparable with a credit tenant on a ten-year lease is not the same as a vacant building of the same size. So the appraiser has to know the terms of each sale. Confirming them with a broker or a principal is part of the job, not a courtesy.

What a Cost Approach Commercial Appraisal Adds Up

The cost approach asks a simple question. What would it cost to buy the land and build this property new today, less the value the existing building has lost? The formula runs: site value, plus replacement cost new, plus entrepreneurial incentive, minus accrued depreciation.

Site value comes from land sales, so the cost approach starts with its own small sales comparison analysis. Replacement cost new is the cost to build a modern equivalent with the same utility, not an exact copy. That distinction matters on older buildings. Reproducing a 1920s masonry warehouse with its original details would cost far more than replacing its function with a tilt-up box. Buyers pay for function. Cost figures come from published cost services, contractor bids, and recent local projects. They cover direct costs such as labor and materials, plus indirect costs such as architecture, permits, financing, and lease-up.

Entrepreneurial incentive is the profit a developer would need to take on the project. Leaving it out understates cost. Including it without market support overstates it. Either way, it should be visible in the report, not buried.

The Uniform Standards of Professional Appraisal Practice require a developed cost approach to address site value, cost new, and accrued depreciation. That last item is where most of the judgment sits.

How Depreciation Is Measured

Depreciation in an appraisal is not the tax schedule. It is the gap between what the building would cost new and what it contributes to value today. It comes in three forms.

Physical deterioration is wear. Roofs age, parking lots crack, mechanical systems reach the end of their lives. Some of it is curable, meaning the cost to fix is less than the value it adds back, and some is not. Functional obsolescence is a design problem. Think 14-foot clear height in a market that wants 32 feet, or too little power for modern loads. External obsolescence comes from outside the property line, such as rising submarket vacancy or a highway interchange that moved the traffic.

Appraisers measure depreciation several ways. The age-life method compares effective age to total economic life. Market extraction pulls depreciation out of actual sales. Subtract land value from the sale price, then compare what remains to cost new. Breakdown analysis prices each form of depreciation separately. On a new building the number is small and easy to support. On a 45-year-old building it can exceed half of cost new. The further the estimate has to reach, the less weight the approach deserves.

A Worked Example on an Industrial Building

Consider a 36,000 square foot warehouse, twelve years old, in a stable industrial submarket. The cost approach might run like this:

  • Site value from land sales: $900,000
  • Replacement cost new, including indirect costs and entrepreneurial incentive: $4,200,000
  • Less accrued depreciation at 30 percent: $1,260,000
  • Depreciated cost of improvements: $2,940,000
  • Indicated value by the cost approach: $3,840,000

Now the sales comparison approach. Four metro warehouse sales, adjusted for location, age, clear height, and market conditions, bracket $98 to $112 per square foot. The appraiser reconciles to $105 per square foot, which indicates $3,780,000.

The two approaches land within two percent of each other. That agreement is itself evidence. When the approaches disagree by 20 percent, something is wrong with an input, and the reconciliation should say which one.

When There Are No Comps

Some properties have almost no market. A fire station, a school, a church, or a purpose-built manufacturing plant may trade once in a generation, and often not as the same use. These are special-use properties. Income struggles because there is no rental market. Sales comparison struggles because there are no sales. Cost is usually the only approach with real evidence behind it.

New construction is the other clear case. A building completed last year has minimal depreciation, current cost data, and a land value that can be supported. Lenders financing construction lean on cost for exactly that reason. Still, they expect it to reconcile against the completed value from the other approaches.

Cost also plays a quieter role on ordinary income property. When the income approach lands well below what it would cost to build, new supply is not feasible at current rents. That gap tells a lender something about competitive risk. It tells a broker something about how long existing stock will hold its pricing. An appraiser who develops cost even when it does not lead is giving you that signal for free.

Where Each Approach Earns Its Weight

On a stabilized multi-tenant building, income leads and sales comparison supports it. On an owner-occupied building with an active market, sales comparison may lead. Owner-user buyers think in price per square foot, not cap rate. On a special-use facility or a building still in its first year, cost leads. Our piece on what drives office building value shows the income-led case in detail.

The weighting is a judgment the appraiser has to explain. A report that develops all three approaches and then averages them has not reconciled anything. A report that leans on one approach should say why its evidence is stronger. Read the reconciliation with that question in mind, and you will know quickly whether the report was built or assembled.

Ask Which Approach Carried the Weight, and Why

Before relying on a commercial value, find the reconciliation and check three things. First, was the leading approach the right one for this property type and its data? Second, do the sales adjustments and the depreciation estimate have market support the report actually shows? Third, do the approaches agree, and if not, is the gap explained? If any answer is no, the cover-page number rests on less than it appears to. So ask the appraiser. A good one will walk you through it.

Selling a Building With No Clean Comps?

PahRoo develops the sales comparison and cost approaches with the support shown, so brokers can price with confidence and lenders can see the evidence.

Scope a Commercial Appraisal

Frequently Asked Questions

When is the cost approach used in commercial appraisal?

It leads on new or nearly new buildings, where depreciation is small and costs are current, and on special-use properties such as schools, churches, and purpose-built plants that have few or no comparable sales. On ordinary income property it usually supports the conclusion and serves as a feasibility check against the income approach.

How does the sales comparison approach work for commercial property?

The appraiser locates sales of similar properties, confirms the terms of each sale, and adjusts for differences in location, size, age, condition, lease status, and market conditions. Because commercial sales are scarce, the search often covers a wider area and a longer time period, and the unit of comparison changes by property type.

Why is the cost approach used for special-use property?

Special-use properties rarely sell and rarely rent, so the sales comparison and income approaches have little evidence to work with. The cost approach can still be developed from land sales, current construction costs, and a supported estimate of depreciation, which makes it the most credible path to value for those properties.

How is depreciation measured in a commercial appraisal?

Appraisal depreciation is the gap between cost new and the building’s current contribution to value. It includes physical deterioration, functional obsolescence, and external obsolescence. Appraisers estimate it through the age-life method, market extraction from actual sales, or a breakdown of each form, and the estimate should be supported in the report.

Are there enough comps for commercial property?

Often not many. A submarket may produce only a handful of relevant sales over two years. Appraisers widen the geography, extend the time window, and adjust for market conditions to compensate. When comparable sales are too thin to support a conclusion, the report should say so and lean on the cost or income approach instead.

Sales, Cost, and Income Analysis From One Appraisal Team

PahRoo Appraisal & Consultancy develops all three approaches to value on commercial assignments across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, from single-tenant industrial to special-use facilities. Our commercial appraisal services page covers scope and property types, our guide to net operating income explains the income side, and you can contact our team or call 773-388-0003 to discuss a specific property.
Vintage home appraisal story about a 1901 Chicago brick house with a bedroom and no closet.
Vintage Home Appraisal: The Bedroom With No Closet

One of our residential appraisers recently stood in a Chicago bedroom built in 1901 and noticed something missing. There was no closet. On a modern checklist, that looks like a problem. In a vintage home appraisal, it tells a story about how people actually lived.

By the end of this article, you’ll know:

  • Why homes built before the 1920s often have bedrooms without closets
  • Whether a room needs a closet to count as a bedroom
  • How market support saved a three-bedroom count after a renovation removed a closet

What a Vintage Home Appraisal Sees That a Checklist Misses

Plenty of people believe a room without a closet cannot be a bedroom. It is one of the most persistent myths in residential real estate. In fact, Fannie Mae’s appraisal guidance contains no closet requirement. A bedroom needs adequate size, ceiling height, privacy, heat, and a window or door for emergency egress. The closet rule comes from habit, not from the standards appraisers follow.

Still, habit shapes markets. Buyers expect closets, agents list rooms based on them, and an appraiser who treats every house like new construction will mark a closet-free room down without a second thought. That is where experience earns its fee. Our residential appraisal work across Chicago’s older housing stock means we read a 1901 floor plan on its own terms, then test that reading against real market evidence.

Why Homes Built in 1901 Rarely Have Bedroom Closets

In 1901, families did not organize their lives around hanging rods. Most clothing lived in wardrobes and large cedar trunks, often one trunk per person, parked at the foot of the bed. Some homes went a step further and built a single oversized cedar closet for the whole household. Individual bedrooms stayed small and simple, sized for a bed and a trunk and little else.

Chicago’s early twentieth century housing boom produced tens of thousands of these homes. The Chicago History Museum documents how bungalows and workers’ cottages filled the city’s neighborhoods as the population surged. Organizations like the Chicago Bungalow Association now work to preserve these layouts as a signature of the era. So when you walk into a vintage bedroom and find no closet, you are not looking at a defect. You are looking at 1901.

The Bathroom Addition That Nearly Erased a Bedroom

Now the story. The subject property was a three-bedroom home, built in 1901, with one and a half bathrooms. In 2025, the owners added a second full bathroom. Smart move on paper, because bathrooms carry real value in older housing stock. But the new bathroom took its space from a bedroom closet, which was removed entirely.

Here is the trap. Judged purely by modern convention, the home now reads as two bedrooms plus an office. That single reclassification can shift the comparable pool, the marketing story, and the final value. A renovation meant to add value would have quietly subtracted a bedroom instead. The owners had no idea. Most owners never do, because nobody warns them that a closet can carry that much weight on a report.

How Market Support Kept the Third Bedroom on the Report

Our appraiser did not simply declare the room a bedroom and move on. Sympathy is not a valuation method. Instead, she built the case. The home’s 1901 construction date placed it firmly in Chicago’s vintage stock, where closet-free bedrooms are a documented, common layout. Comparable vintage homes in the market sell as three-bedroom houses with the same configuration, and buyers in this segment accept the trade.

That is market support: a conclusion backed by evidence of how actual buyers and sellers behave, not by personal opinion. With the era established and the comparables in hand, the report could credibly carry the home as a three-bedroom. The bedroom count survived, the new bathroom added its value, and the renovation did what the owners intended. The difference between those two outcomes was never the house. It was the appraiser’s knowledge of what 1901 means.

What Owners of Older Chicago Homes Should Do Before an Appraisal

First, learn your home’s era before you remodel it. A change that seems harmless, like absorbing a closet into a new bathroom, can alter how a room is classified. Second, keep records of what your home originally looked like, because floor plans and old listing photos help an appraiser reconstruct the vintage layout. Third, and most important, choose an appraiser who knows your housing stock. A checklist can count rooms. Only experience can explain them. If your home was built before the 1920s, ask directly how the appraiser handles vintage layouts. The answer will tell you a lot.

Own a Vintage Home? Get an Appraiser Who Can Read Its Era

A 1901 floor plan deserves more than a modern checklist. PahRoo’s appraisers know Chicago’s vintage housing stock and back every conclusion with market evidence.

Request Your Appraisal Quote

Frequently Asked Questions

Does a bedroom need a closet to count in an appraisal?

No. Fannie Mae guidelines and the International Residential Code do not require a closet. A bedroom needs adequate size, ceiling height, a heat source, privacy, and a window or door for emergency egress. The closet rule is a common myth.

Why do older homes have bedrooms without closets?

Before the 1920s, most families stored clothing in wardrobes and cedar trunks rather than built-in closets. Many vintage Chicago homes also used one large shared cedar closet instead of individual bedroom closets. The layout reflects how people lived at the time.

Can a renovation lower my home’s appraised value?

It can. A renovation that removes a feature buyers expect, such as a bedroom closet, may change how a room is classified. Before you remodel an older home, consider what the change does to room count and functional utility, not just the new feature you gain.

What does market support mean in an appraisal?

Market support means the appraiser backs a conclusion with evidence from actual sales. If comparable vintage homes with closet-free bedrooms sell as three-bedroom houses, the market treats those rooms as bedrooms. The appraiser can then classify the subject home the same way.

Should I add closets to my vintage home before an appraisal?

Not automatically. In many vintage markets, buyers accept period layouts, and forcing modern closets into small rooms can hurt function. Talk with an appraiser who knows your local vintage housing stock before spending money on changes.

Need an Independent Appraisal?

PahRoo Appraisal & Consultancy has appraised Chicago’s housing stock for decades, from 1901 workers’ cottages to new construction. Whether you need a residential appraisal, an independent valuation for divorce proceedings, or simply a straight answer about what your vintage home is worth, our team is ready. Learn more about PahRoo or contact us today.


Chicago condo market in mid-2026, cooling fastest in the suburbs.
Chicago Condo Market Mid-2026: Where It’s Cooling

The Chicago condo market is starting to cool, and it’s showing up first in the suburbs. That is the clearest signal in the latest data, for the week ending June 26, 2026. Buyers have pulled back across almost the whole metro, but the softening is sharpest in collar-county condos. Meanwhile, prices are mostly holding. So this looks like a market slowing down, not falling apart. We mapped the wider four-county metro picture a week ago; this update zeroes in on where the cooling is actually landing.

By the end of this article, you’ll know:
  • Why buyer demand has cooled across almost every Chicago submarket
  • Where condo buyers now have real negotiating room
  • Why a falling number of sales hasn’t dragged prices down yet

What the Chicago Condo Market Looks Like Right Now

Start with demand, since it moves first. Pending sales, the count of homes going under contract, fell from a year ago in seven of the eight county and segment groups we track. Condos are weaker than single-family homes in nearly every county. The steepest drops sit in suburban condos: DuPage condo pending sales are down about 28% on the year, Will down about 21%, and Cook down about 18%.

Why so broad? When one neighborhood softens, local reasons usually explain it. But when almost everything softens at once, the cause is shared. Here it is the cost of borrowing, and we’ll come back to that.

The Suburbs Are Where Condos Are Softening

The clearest stress sits in the collar counties. In DuPage and Will, condo inventory is piling up while demand falls. Will condo listings are up almost 42% on the year, and DuPage condo listings are up about 19%. At the same time, fewer buyers are signing contracts. That combination, more supply meeting less demand, is exactly what hands buyers leverage.

One clean way to see it is the pending-to-new-listings ratio. Above 1.0, buyers are absorbing new listings as fast as they arrive. Below it, listings stack up. Suburban condos sit well under the line, with Will around 0.77 and DuPage around 0.83. So inventory there is building, not clearing.

A fair caution before anyone over-reads the numbers: these suburban condo markets are small, so weekly percentages swing hard. Treat the direction as real and the exact figure as rough.

Condo segments by the numbers

County (condo) Inventory vs last year Pending sales vs last year What it signals
Cook -13.2% -18.1% Tightening, still liquid
DuPage +19.3% -27.8% Building inventory, buyer leverage
Will +41.9% -20.7% Fastest build, most buyer room
Lake -0.4% +2.2% Thin sample, mixed read

Cook County Is Still Tight

Cook is the counterweight. Single-family inventory there is down about 16% on the year, and prices are up around 4%. So sellers still hold the cards. Cook condos are firmer than the suburbs too, though the headline price gain there comes with a catch, which is next.

Why a Sale “Above List” Can Fool You

Cook condo sale prices look up about 11% on the year. That sounds hot. It is not, and this is where appraisal experience earns its keep.

With fewer condos selling, the mix of what sells swings the median. When the pricier units are the ones clearing and the cheaper ones sit, the median jumps without any single home gaining a dollar of value. The sold-to-list ratio of about 1.03 confirms it: the higher end is doing the clearing. So read that 11% as a change in what sold, not as proof that every Cook condo is worth more.

The same logic runs the other way. When a county’s sold-to-list ratio sits near 0.80, as Lake single-family does, it does not mean homes are selling 20% below their own asking price. It means the cheaper homes are the ones moving. Misread either signal and you misprice the collateral.

Prices Are Holding, Volume Is Not

Across the metro, sale prices are flat to higher than a year ago in six of eight segments. Will single-family leads at about +9%. So even as sales slow, the prices buyers actually pay have held. That is the signature of a market cooling, not crashing.

This kind of market usually resolves one of two ways. Either demand returns, which needs mortgage rates to fall, or sellers start to concede. The early signs of concession are already showing where inventory is building: listings sitting longer in Lake, and a rising share of price cuts in DuPage condos and Will single-family.

Why the Fed’s Cuts Aren’t Helping Buyers

The reason demand is soft almost everywhere comes back to financing. The Federal Reserve has cut its policy rate over the past year, down to about 3.63%. But the 30-year fixed mortgage rate has barely moved, sitting near 6.49%. Freddie Mac tracks that rate weekly, and the gap between the two is about 286 basis points. That is far wider than the 150 to 200 that is normal.

In plain terms, the rate relief that lower Fed policy would normally pass to buyers is not reaching them. So until that gap narrows, cheaper Fed policy will not mean a cheaper mortgage, and demand is likely to stay soft.

What It Means If You’re Buying or Selling

If you’re buying a condo in DuPage or Will, this is the most negotiating room the metro has offered in a while. Building inventory and slower demand both work in your favor. Just underwrite each unit on its own, because these small submarkets vary a lot from one building to the next.

If you’re buying single-family in Cook, expect to compete. Inventory is tight and pricing is firm, so move quickly on a well-priced listing.

If you’re selling in the suburbs, price ahead of the market, not behind it. With inventory building, an aspirational price tends to sit and then get cut. The data already shows that cut happening for a rising share of listings.

If you’re selling in Cook, price to the market and expect reasonable absorption. Buyers are still there for well-priced homes.

Know Your Segment, Not Just the Market

There is no single Chicago condo market right now, and no single housing market either. Cook single-family is tight. Suburban condos are softening. Prices are holding even as sales slow. Which of those describes your home depends on the county, the segment, and even the building.

So when you need to know what a specific property is worth in a market this split, a citywide headline will not get you there. The address will.

A cooling market makes the right number harder to read.

Composition effects and thin suburban data can make a property look stronger or weaker than it is. For a defensible value on your specific home, in your county, talk to PahRoo.

Request an Appraisal

Frequently Asked Questions

Is the Chicago condo market crashing?
No. It is cooling, not crashing. Buyer demand has fallen across most of the metro, but sale prices are mostly holding or still rising from a year ago. A market that slows on volume while prices hold is softening, not collapsing.
Where are Chicago condo prices softening the most?
The suburbs. DuPage and Will condos are building inventory while demand falls, which is the setup that eventually pressures prices. Lake condo prices are down on the year too, but that reading rests on a very small sample, so treat it with caution.
Is now a good time to buy a condo in the Chicago suburbs?
Buyers there have more negotiating room than they have had in a while, thanks to building inventory and slower demand. Every building is different in these small submarkets, though, so evaluate the specific unit rather than the county average. This is general market information, not personal advice.
Why are home prices holding if sales are falling?
Two reasons. Sellers are anchored and slow to cut, and the mix of what sells can lift the median when pricier homes clear while cheaper ones sit. Markets like this usually resolve through longer marketing times before they resolve through price.
Why haven’t mortgage rates dropped along with the Fed’s cuts?
Mortgage rates track long-term bond yields and lender risk pricing, not the Fed’s policy rate directly. That gap is unusually wide right now, near 286 basis points, so most of the Fed’s easing is not reaching the mortgage rate a buyer actually pays.

Need a Read on Your Specific Property?

Market reports describe the forest. An appraisal measures your tree. When you need to know what one property is worth, in one county and one building, an independent appraisal gives you a credible, defensible answer.

PahRoo Appraisal & Consultancy, LLC helps homeowners, attorneys, accountants, bankers, and real estate professionals make confident decisions across the Chicago area. Whether you’re weighing a Cook County tax appeal, settling an estate, removing PMI, or navigating a divorce, our team is ready to help.

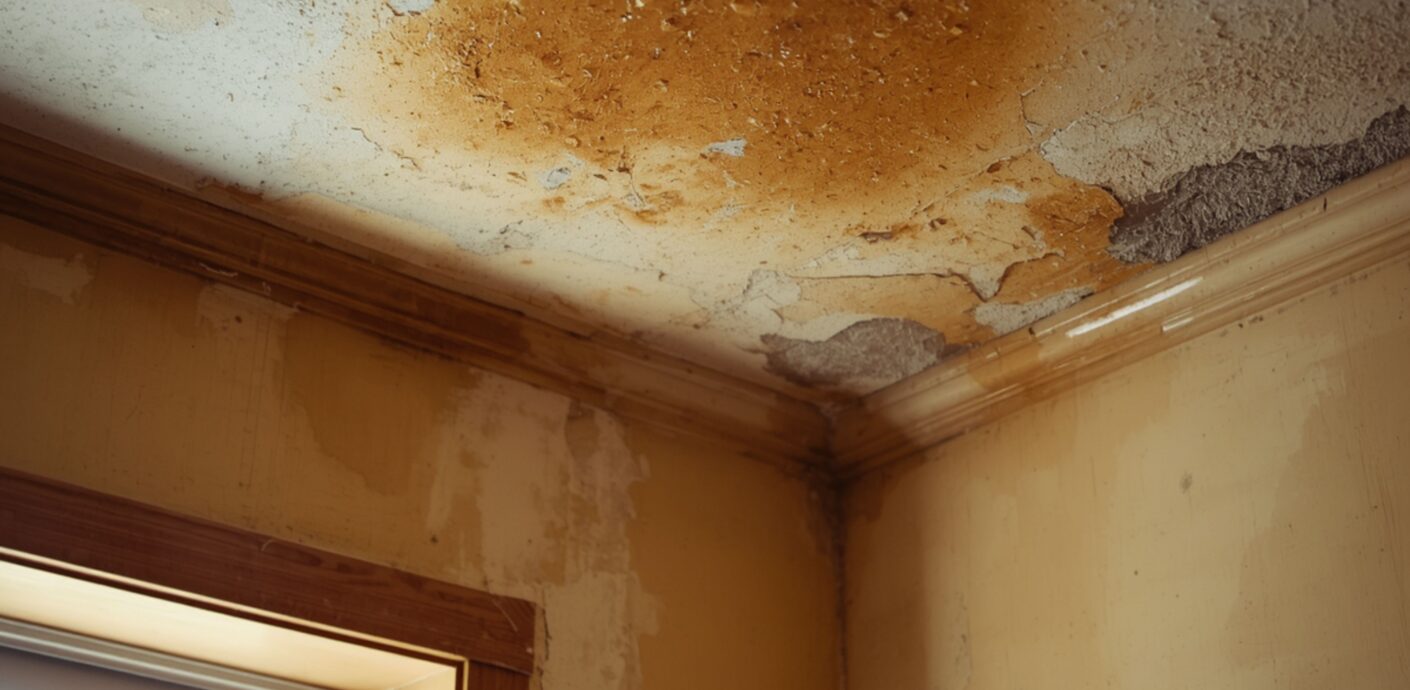
Water damage stains on a ceiling flagged during a home appraisal
Water Damage & Home Value: What Appraisers Flag

Water damage has a way of derailing a sale right when things feel like they are going smoothly. A faint ceiling stain might not worry you at all. An appraiser sees it differently, because that stain often hints at a bigger story. Knowing how water damage and home value connect, and what an appraiser flags before closing, puts you a step ahead. You get to handle problems on your own terms, not at the last minute.

By the end of this article, you’ll know:

  • The water-related conditions an appraiser looks for and writes up
  • Why a lender can stall your closing until water problems get fixed
  • What to repair and document before the appraisal happens
How Water Damage Affects Home Value

Most homeowners assume the hit to value equals the repair bill. It rarely works that cleanly. What worries a buyer, a lender, and an appraiser is what the water might have done out of sight. Water travels. A roof leak can rot the sheathing above a ceiling long before any stain shows up. Down in the basement, dampness might point to a grading or foundation issue. And a slow drip under a sink? That can feed mold behind the drywall for months before anyone notices.

That uncertainty is what moves the numbers. A home with visible water damage tends to draw lower offers, repair demands, or a longer stretch on the market. An appraiser’s job, after all, is to capture how the market reacts to what’s in front of it. So we note the visible conditions and weigh how they affect value and saleability.

What an Appraiser Will Notice

We are not home inspectors, and we do not go cutting into walls. But a trained appraiser spots the visible signs of a water problem fast during a standard residential appraisal. The usual flags:

  • Water stains on ceilings and walls
  • Standing water in a basement, crawlspace, or against the foundation
  • A musty smell that says moisture is still hanging around
  • Warped or swollen drywall, baseboards, and flooring
  • Roof leaks, or shingles that have clearly seen better days
  • Grading that sends rainwater toward the house instead of away from it

A lot of this matters because of what tends to follow water: mold. The EPA points out that mold needs ongoing moisture to grow. So a damp crawlspace, or a stain nobody can explain, earns more scrutiny than its size might suggest.

How Water Damage Can Hold Up Your Closing

Water damage can hold up the calendar, too. Lenders, especially on government-backed loans, hold a property to minimum condition standards.. Active water intrusion is one of the more common reasons an appraisal comes back “subject to repair.”

Once that happens, the lender usually wants it fixed and re-checked before the deal can close. Even a small repair can push your closing date back a week or two. Worse, when it only turns up at the appraisal, that lost time becomes the real cost for anyone working to a firm contract date.

Old Damage Reads Differently From Active Damage

Not every water stain carries the same weight. The question an appraiser really cares about is whether the source got fixed.

Picture a leak you repaired last spring. You replaced the ruined drywall and kept the receipts. In that case the worry mostly evaporates, because you can prove the problem is behind you. Now picture a fresh stain, a corner that’s still damp, and no paperwork. An appraiser has to treat that as a live issue, and so will the buyer.

What to Do Before the Appraiser Shows Up

A few moves keep a water issue from running your whole sale:

      1. Fix the source, first and always. Scrub a stain without stopping the water and it comes right back, usually at the worst possible moment.
      2. Keep the paperwork. Invoices, contractor notes, inspection reports. Good documentation answers the appraiser’s question before anyone asks it.
      3. Repair what shows. Swap out stained drywall, ceiling tiles, and warped trim, so nobody is writing up damage you have already handled.
      4. Speak up early. If the house has had a real water event, tell your agent and your appraiser up front. Then everyone plans around the facts instead of a surprise.
Why It Pays to Get Ahead of It

Water damage does not have to wreck your value or your timeline. Most of the harm to a sale comes from the unknowns, like what’s behind the wall and whether it’s still wet. Clear those up and the whole conversation shifts in your favor.

So track down the source, fix it, write it all down, and patch the visible damage before you list. Do that, and a water stain stays a footnote in your sale rather than the headline at your closing.

Worried water could cost you at the closing table?

Find out where your home really stands before a lender or a buyer raises the question. PahRoo delivers independent, defensible appraisals that give you answers, not guesswork.

Request Your Appraisal

Frequently Asked Questions

Does water damage lower a home’s appraised value?

It can, though not on its own. The effect depends on how bad it is, whether you’ve fixed the source, and how nervous it makes buyers. Often the real drag on value is what the damage hints at, rather than the damage you can see.

What does an appraiser look for when checking for water damage?

Visible clues, mostly: stains, standing water, musty smells, warped materials, signs of a roof leak, and poor drainage. An appraiser reports what’s in plain sight and won’t go digging behind walls or running lab tests.

Will water damage stop a home loan from closing?

It can slow things down. A lender may insist that active water intrusion gets corrected and re-inspected first, particularly on government-backed loans with condition standards to meet.

Do I need to fix water damage before selling?

Usually yes, especially when it’s visible or a buyer needs financing. Sorting it out before you list keeps the negotiation calmer and lowers the odds of a delayed closing.

Is old, repaired water damage still a problem for an appraisal?

Much less of one, as long as you fixed the source and have the records to show it. Repaired and documented damage sits in a very different category from something fresh or unexplained.

Need an Independent Appraisal?

Sometimes water damage, repairs, or condition questions cloud what a home is really worth. In those moments, an independent appraisal gives you a credible, well-supported answer before you negotiate or finance.

PahRoo Appraisal & Consultancy, LLC helps homeowners, attorneys, accountants, bankers, and real estate professionals make confident decisions. Whether you’re preparing to sell, settling an estate, removing PMI, navigating a divorce, or weighing how a property’s condition affects value, our team is ready to help.


The three types of home appraisals: full, exterior-only, and desktop
The 3 Types of Home Appraisals: Full, Exterior, Desktop

Not every home appraisal involves an appraiser walking through your living room. Some are done from the curb. Others happen entirely from a desk, with nobody visiting at all. So if you’re buying, refinancing, or settling a legal matter, knowing the types of home appraisals, and which one applies to you, tells you a lot about what you’re paying for and how much weight the result can carry.

By the end of this article, you’ll know:
  • What separates a full, exterior-only, and desktop appraisal
  • When a lender is likely to order each one
  • Why the familiar form numbers are about to disappear in 2026
What the Three Types of Home Appraisals Actually Mean

The difference comes down to one question: how much of the property does the appraiser actually see? That scope drives everything else, including cost, turnaround, and how confident anyone can be in the final number. Three scopes cover most situations, so let’s take them in order, from the most thorough to the lightest.

The Full Appraisal: Inside and Out

This is the one most people picture. First, the appraiser visits the property, inspects the exterior, and walks the interior room by room. We measure, photograph, note condition and quality, and flag anything that affects value. On the legacy forms, this is the 1004 for a single-family home.

A full appraisal carries the most weight, because the appraiser has seen the property firsthand. So for higher-stakes work, like an estate settlement, a divorce, or a property tax appeal, this is usually the scope you want. There is no data gap for anyone to poke at later.

The Exterior-Only Appraisal: A Look From the Curb

An exterior-only appraisal, sometimes called a drive-by, is what it sounds like. The appraiser views and photographs the outside of the home but does not go inside. For the interior, we rely on other sources, such as prior listings, public records, and whatever reliable data exists. On the legacy forms, this is the 2055.

It is faster and cheaper than a full appraisal. Still, there’s a trade-off. Without eyes on the interior, the appraiser cannot confirm condition, updates, or problems behind the front door. So lenders tend to reserve it for lower-risk situations, not for a purchase where the inside is a mystery.

The Desktop Appraisal: No Visit at All

A desktop appraisal goes one step further. The appraiser never visits the property. Instead, the whole analysis runs on data: MLS records, public records, and a floor plan that shows the interior walls. A licensed or certified appraiser still develops the opinion of value and signs the report, so it is a real appraisal, not an automated computer estimate.

Fannie Mae made desktop appraisals a permanent option back in March 2022, mainly for certain one-unit purchase loans. Their guidelines require a floor plan, not just an exterior sketch, so the appraiser can judge how the home actually functions. One rule is worth knowing: if a desktop appraiser ends up visiting and inspecting the property, it stops being a desktop and becomes a full appraisal. The scope defines the product, not the intention.

The three side by side
Scope Interior seen? Exterior seen? Legacy form Typical use
Full Yes, in person Yes, in person 1004 Purchases, high-stakes valuations
Exterior-only No (from data) Yes, in person 2055 Lower-risk refinances
Desktop No (data + floor plan) No (from data) 1004 Desktop Certain low-risk purchase and refi loans

One more option sits alongside these: the hybrid, where a trained third party collects the property data and the appraiser does the analysis from it. Still, the principle is the same. The less the appraiser sees in person, the more the result leans on someone else’s data.

Which One Will You Get?

For most home purchases, expect a full appraisal. It is the standard, and it gives the lender the most complete picture. By contrast, exterior-only and desktop appraisals show up more often in refinances and lower-risk loans, where the lender’s automated system signals that a lighter scope is acceptable.

Usually you don’t choose. The lender’s system decides what’s eligible. But you can ask which scope is being used, and it pays to ask. If you’re ordering an appraisal yourself, outside a loan, for a divorce, an estate, or a Cook County tax appeal, you can request a full interior appraisal. For those purposes, you generally should. After all, a value backed by an actual walkthrough is far harder to challenge.

What’s Changing in 2026

One big shift is landing in 2026, and it reshapes everything above. For example, the form numbers in this article, the 1004, the 2055, the 1004 Desktop, are being retired. Fannie Mae and Freddie Mac are replacing them with a single, dynamic report called the Uniform Residential Appraisal Report, or URAR, built on a data standard known as UAD 3.6.

Instead of a separate form for each scope, one report now flexes to fit the assignment, whether that’s a full interior inspection, an exterior-only, or a desktop. The timeline is set. In fact, lenders have been able to use the new format since early 2026. By November 2, 2026, it becomes mandatory, so every appraisal on a loan sold to Fannie Mae or Freddie Mac must use UAD 3.6. The old format then retires fully in May 2027. Fannie Mae’s UAD page tracks the details as they firm up.

So the labels are changing, but the underlying choice is not. Full, exterior-only, and desktop still describe how much the appraiser sees. That question outlives any form number.

The Form Changes, the Question Doesn’t

Strip away the form numbers and every appraisal answers the same thing: how well does the appraiser actually know this property? For instance, a full interior appraisal answers it with a walkthrough. An exterior-only answers it from the curb. A desktop answers it from data and a floor plan. Each has its place, and each carries a different level of certainty.

So when an appraisal lands on your desk, look past the format and ask what the appraiser was allowed to see. For anything that has to hold up, in court, in a negotiation, or in front of a lender, that scope is the whole ballgame.

Not sure which kind of appraisal your situation needs?

The right scope depends on what’s at stake. For an estate, a divorce, a tax appeal, or a lending decision, talk to PahRoo about the appraisal that will actually hold up.

Request an Appraisal

Frequently Asked Questions

What is the difference between a desktop and a full appraisal?
A full appraisal includes a physical inspection, inside and out. A desktop appraisal has no inspection at all; the appraiser works from data and a floor plan. Both are done by a licensed appraiser, but the full version rests on firsthand observation.
Does a desktop appraiser ever visit the property?
No. If the appraiser visits and inspects the home, it stops being a desktop appraisal and becomes a full one. The whole point of a desktop is that the analysis happens from data sources rather than a site visit.
Is an exterior-only appraisal less reliable than a full appraisal?
It carries less certainty about the interior. The appraiser sees the outside but relies on data for what’s behind the door. For lower-risk situations that’s often fine, but where interior condition matters, a full appraisal is stronger.
Which type of appraisal will my lender order?
Usually the lender’s automated system decides, based on the loan’s risk. Most purchases get a full appraisal. Lighter scopes like desktop or exterior-only show up more in refinances and lower-risk loans. You can always ask which one is being used.
Are appraisal forms like the 1004 going away?
Yes. By November 2026, Fannie Mae and Freddie Mac are replacing the legacy forms with one dynamic report called the URAR. The form numbers retire, but the scope choices, full, exterior-only, and desktop, carry over into the new report.

Need an Appraisal You Can Stand Behind?

As the industry shifts toward lighter, data-only products, the value of an appraiser who has actually seen the property only grows. So at PahRoo, the appraiser who develops the analysis is the one who signs the report. That accountability is the whole point.

PahRoo Appraisal & Consultancy, LLC helps homeowners, attorneys, accountants, bankers, and real estate professionals make confident decisions across the Chicago area. Whether you’re weighing a Cook County tax appeal, settling an estate, removing PMI, or navigating a divorce, our team is ready to help.

Family lawyer reviewing divorce property documents in Illinois
Disputed Property Value in Illinois Divorce: 3 Documents


The two numbers are $640,000 and $515,000, and each spouse is sure of theirs. Disputed property value in an Illinois divorce usually starts this way. One side quotes a listing site, the other a neighbor’s sale. Before anyone pays for an expert, three records already exist. They will tell you which number is closer, and whether either one is worth defending.

By the end of this article, you’ll know:

  • Which three records to request, where each one lives in Cook County, and what each can and cannot prove
  • The tells inside each record that point to a soft number on the other side
  • When the file needs an independent appraisal, and what a broker should hand over in the meantime

Why Disputed Property Value Gets Settled on Paper First

Illinois divides marital property in just proportions, not an automatic half. That comes from 750 ILCS 5/503, and the court applies it asset by asset. The house is often the largest line on the marital balance sheet, and the court has to land on a value before it can divide anything.

When spouses ask the judge to decide property, each one completes a financial affidavit with supporting documents, as Illinois Legal Aid Online explains. The value on that affidavit has to come from somewhere. Your job, early, is to find out where.

Three records answer that question at almost no cost. Each was created for a different purpose, so none is a value opinion you can take to trial. But together they show you the shape of the dispute. And they do it before you spend a dollar on an independent divorce appraisal.

Record One: The Assessor’s Property Record

Start with the Cook County Assessor. The office values about 1.8 million parcels, and it says plainly that it does not value them one at a time. It uses mass appraisal, a regression model that relates your client’s house to the sales around it. One-third of the county gets reassessed each year on a three-year cycle. The Board of Review then finalizes values after appeals.

Pull the property detail page by PIN. It shows the estimated market value, the assessed value, the property class, and the year of the next reassessment. It also shows an exemption history and a characteristics table: square footage, baths, basement, garage, age. Read the market value line, not the assessed line. For most homes the assessed figure is a fraction of the market estimate. A spouse who quotes it as the value misread the page.

A value reduced at the Board of Review means someone argued, in writing, that the house is worth less. If that same spouse now claims it is worth more, you have the exhibit. A table showing three baths and a full basement when the house has two and a crawl space means the record is wrong. An unpermitted addition or a finished lower level can push the gap the other way. Two homeowner exemptions across two properties is a separate problem your client should hear about now.

Consider a hypothetical Evanston bungalow. The Assessor’s estimated market value reads $480,000. One spouse claims $640,000 and the other claims $515,000. The record proves neither number, but it puts the burden where it belongs. The $640,000 figure sits $160,000 above a model built on nearby sales, so that spouse owes you a report.

Record Two: Any Prior Appraisal on the Property

If either spouse bought, refinanced, or opened a home equity line during the marriage, a lender appraisal exists. Ask for it in discovery, and ask the lender if the spouse cannot find it. It answers a lender’s question as of a lender’s date, so the value itself is stale. The rest of the report is not.

A prior appraisal gives you a measured square footage, a sketch, and interior photos. It also gives a condition rating, the updates the owner claimed at the time, and the comparable sales an independent appraiser chose back then. If one spouse says the kitchen was gutted in 2019, the 2021 refinance photos settle it. Under USPAP, the standard every licensed appraiser works to, the report must state its effective date and intended use. Hold it to that date. Then it is a record of what the house was, not an argument about what it is worth today. Our piece on the date of value in a divorce appraisal explains why that distinction moves settlements.

Three things deserve a second look. A value that lands exactly at the number the loan needed. A property described differently than it stands today, which can mean work done since, or work never done. And a report dated after a deed changed hands, because a quitclaim transfer mid-case changes which date the court cares about. When I get a prior appraisal in a new assignment, I do not adopt its value. I use it to check what changed and to confirm the square footage.

Record Three: Broker Price Opinions and Market Analyses

A broker price opinion, or the comparative market analysis most sellers see, is an agent’s estimate of what a home could list or sell for. In a divorce file they show which comparables each side leans on and whether a range is a listing range or a value. A pricing tool built to win a listing will not survive an opposing expert, which is why a divorce home appraisal and a price opinion land so differently in front of a judge.

If you are the broker being asked for that CMA, here is what makes yours useful instead of a liability. Date it. State on the first page that it is a pricing analysis and not an appraisal. List every comparable with its closed date, closed price, and any seller concessions you know about. Say whether you walked the interior or worked from photos. Then keep your file. In a contested case you may get a subpoena for it, and a range you stretched for one spouse is a bad afternoon under oath. A CMA that shows its work gets read alongside the appraisal. One that does not gets read against you.

For counsel, the practical move is to request both sides’ opinions at once and lay the comparables next to each other. If both agents used the same four sales and landed $90,000 apart, the difference is in the adjustments. That is an appraisal question. If they used different sales, someone is shopping for comps.

When the Paper Runs Out and the File Needs an Appraisal

The three records frame the dispute. They rarely end it. Order an independent appraisal when the gap survives the paper. Order one when the equity is large enough that a five percent error costs real money, or when a buyout or refinance depends on the number. The same goes for an unusual property, a rental unit, or a case likely to reach a hearing. A retrospective date, such as the date of marriage for a premarital equity claim, is its own reason. None of the records will give you one.

Online estimates do not fill the gap. In April 2026 the Appraisal Standards Board adopted Advisory Opinion 41 on automated valuation models, regression software, and generative AI in appraisal work. An appraiser who uses those tools still owns the result and has to support it. A spouse citing a website estimate has none of that behind the number.

Cook County adds a local wrinkle. A block in Oak Park, a two-flat in Hyde Park, and a bungalow in Norwood Park each sit in a market that moves on its own schedule. A report built for Cook County reads those markets and supports each adjustment. Our article on what makes an appraisal defensible on the witness stand goes through that test in detail.

Pull the Records Before the First Settlement Conference

The sequence is simple. Pull the Assessor’s property record on day one; it costs nothing and needs only a PIN. Put prior appraisals and any broker opinions in your first document request. Ask the lender directly if the spouse comes up empty. Lay the three records side by side and see where the gap lives: the square footage, the condition, the comparables, or the date. Then decide whether an appraisal is needed, and if so, agree the effective date with opposing counsel before either side orders one.

Two Numbers on the Table and No Way to Choose?

PahRoo prepares independent divorce appraisals for contested marital property across Cook County and the Chicago area, built to be disclosed, deposed, and defended.

Order an Independent Appraisal

Frequently Asked Questions

What documents should a family lawyer request when property value is disputed?

Request the county assessor’s property record, any prior purchase, refinance, or home equity appraisal, and any broker price opinion or comparative market analysis either spouse relied on. Together they show where the two numbers came from and whether an independent appraisal is needed.

Can a Cook County assessment be used as market value in a divorce?

Not as a value opinion. The Cook County Assessor values property by mass appraisal for tax purposes and does not inspect the individual home. The estimated market value is useful background, and the characteristics table and appeal history can expose errors, but it should not replace an appraisal when value is contested.

Is a broker price opinion the same as an appraisal?

No. A broker price opinion or comparative market analysis is a pricing tool prepared by a real estate agent, usually to set a listing price. An appraisal is an independent opinion of value developed under USPAP by a licensed or certified appraiser, with a stated effective date, intended use, and supported adjustments.

Can a prior refinance appraisal set the value in a divorce?

Rarely. The value in a refinance appraisal applies to the lender’s effective date, which is usually well before the divorce. The report is still valuable for its measured square footage, sketch, photos, condition notes, and comparable sales, which document what the house was on that date.

When should a divorce attorney order an independent appraisal?

When the gap between the spouses survives the three records, when the equity is large, when a buyout or refinance depends on the number, when the property is unusual or includes a rental unit, when a past effective date is needed, or when the case is likely to reach a hearing.

Appraisal Support for Contested Marital Property in Cook County

The records above are where PahRoo starts too. Since 1999 the firm has prepared divorce, estate, and litigation appraisals across Cook County and the wider Chicago area, along with Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, signs every report and is available for deposition and testimony. See our residential appraisal services, or contact us with the PIN and the records you already have.

Chicago Housing Market 2026 showing home prices and inventory trends
Chicago Housing Market 2026: Prices Hold Firm as Demand Softens

The Chicago housing market 2026 data continues to send mixed signals. Home prices remain resilient, inventory remains historically tight, and sellers still hold a significant advantage. Yet beneath the surface, a different story is emerging: annual buyer demand is beginning to weaken.

The latest Chicago Metropolitan Statistical Area (MSA) housing data reveals a market that remains supply-constrained but increasingly affordability-constrained as well. While weekly activity improved during Week 24, year-over-year demand metrics suggest that elevated borrowing costs continue to limit transaction volume.

For real estate professionals, lenders, attorneys, and investors, understanding this divergence is essential when evaluating market conditions through the second half of the year.

By the end of this article, you’ll know:

  • Where single-family and condo prices stood in Week 24, and why they kept rising while sales slowed
  • How 1.3 months of supply compares with a balanced market
  • Why lower Fed rates have not translated into lower monthly payments, and what that means for lenders, attorneys, and investors

Home Prices Continue to Rise Despite Demand Headwinds

One of the most notable findings from the latest market data is that prices continue to increase even as buyer activity softens. So the two signals are pulling in opposite directions.

Single-family homes recorded a median absorbed price of approximately $407,750, representing a 4.8% increase from the same period last year. Condominiums and townhomes experienced even stronger price growth, with median absorbed prices reaching nearly $324,000, an 8.0% year-over-year increase.

This pricing strength reflects one of the defining characteristics of today’s Chicago market. Simply put, there are not enough homes available for sale.

Limited inventory continues to support values, allowing sellers to maintain pricing discipline despite slower transaction activity.

Inventory Remains Historically Low

Supply remains the foundation supporting today’s market, and the same story holds in both segments.

Active single-family inventory is down more than 9% compared to last year, while condominium inventory has declined nearly 8%.

Perhaps more important, though, is the months-of-supply metric. Both property segments are operating at approximately 1.3 months of inventory. In comparison, a balanced housing market typically contains five to six months of supply.

So buyers continue to compete for available properties, helping support prices even as affordability challenges reduce the number of active purchasers.

If you are advising clients on lending, estate planning, litigation, or tax matters, a real estate appraisal provides independent market analysis that helps reduce risk and support informed decisions.

Why Buyer Demand Is Beginning to Slow

Prices remain firm, but demand has weakened on an annual basis.

Single-family pending sales are now 4.4% below year-ago levels, while condominium pending sales have fallen 6.7%.

This marks a significant reversal from the stronger demand environment observed earlier this spring, and the primary driver appears to be affordability.

Many consumers expected lower Federal Reserve rates to create meaningful mortgage relief. However, mortgage rates have not declined as much as anticipated. According to data published through the Federal Reserve’s FRED database, mortgage financing costs remain elevated relative to recent monetary policy changes. The spread between mortgage rates and the Federal Funds Rate has widened substantially, limiting the impact of monetary easing on homebuyers.

So financing costs remain elevated despite recent Federal Reserve actions.

What Chicago Housing Market 2026 Trends Mean for Real Estate Appraisals

Understanding the difference between market headlines and actual property value can help you avoid costly assumptions when making lending, legal, or investment decisions. Appraisers analyze local supply, demand, inventory levels, financing conditions, and comparable sales to develop credible opinions of value. As the Chicago housing market 2026 continues to show rising prices alongside weakening demand, professional appraisal analysis becomes increasingly important for lending, estate planning, divorce appraisal, tax appeal, and litigation-related decisions. Our Chicago appraisal team works from the same weekly data.

Monthly Payments Are Higher Than Last Year

One of the most important affordability indicators is not the mortgage rate itself, it is the monthly payment buyers must make. Recent housing research from the National Association of Realtors continues to highlight affordability as one of the primary constraints affecting buyer activity nationwide.

Mortgage rates are slightly lower than a year ago, but rising home prices have offset much of the benefit.

For a typical Chicago-area single-family home purchase, monthly principal and interest payments are now estimated to be slightly higher than last year. Condominium buyers have experienced an even larger increase due to stronger price appreciation in that segment.

Simply put, many buyers are paying more each month today than they would have paid a year ago.

This affordability pressure helps explain why annual demand metrics continue to soften even while prices remain strong.

Sellers Still Hold the Advantage

Current market conditions continue to favor sellers. Several indicators support this reading:

  • Inventory remains extremely limited.
  • Months of supply remain well below balanced-market levels.
  • Price reductions have declined year over year.
  • Homes continue to sell close to asking prices.

Still, the market is beginning to show subtle signs of adjustment.

New listings entering the market during Week 24 were priced slightly below the existing inventory pool. This suggests some sellers may be recalibrating expectations to align more closely with current buyer affordability constraints.

This does not signal broad price weakness, but it is an important trend worth monitoring during the summer selling season.

What This Means for Buyers, Sellers, and Investors

For Buyers. Affordability remains challenging, but opportunities may emerge as new listings enter the market at more competitive price points. Buyers should pay close attention to properties that have accumulated additional days on market.

For Sellers. Low inventory continues to provide an edge, but realistic pricing is becoming increasingly important. Homes priced in line with current market conditions are likely to outperform those anchored to aggressive expectations, so pricing discipline matters more than it did in spring.

For Investors. The combination of firm pricing, constrained inventory, and slowing transaction volume favors a disciplined approach. So future appreciation assumptions should stay conservative while mortgage financing conditions remain restrictive.

For Lenders and Financial Professionals. The disconnect between Federal Reserve policy and mortgage financing costs remains a key risk factor. Future demand will depend heavily on whether mortgage rate spreads begin to normalize.

The Outlook for the Chicago Housing Market

The Chicago housing market is not weakening in the traditional sense, at least not yet. Prices remain firm, inventory remains scarce, and sellers still hold negotiating strength.

Even so, annual demand has clearly softened.

The market is transitioning from a supply-driven recovery toward an affordability-driven constraint. Unless mortgage financing conditions improve materially, transaction volume may continue to face pressure even while prices remain supported.

For now, the most likely scenario is a market characterized by limited inventory, stable-to-rising prices, and slower sales activity, a combination that creates both opportunities and challenges for real estate decision-makers throughout the Chicago metropolitan area.

Is Your Collateral Priced for Week 24 or for Today?

Headlines describe the metro. An appraisal describes the property. PahRoo delivers independent valuations for lending, estate, divorce, tax appeal, and litigation work across the Chicago area, signed by Michael Hobbs, MAI, SRA.

Request an Appraisal

Frequently Asked Questions

How does the Chicago housing market affect real estate appraisals?

Real estate appraisers analyze local market conditions, inventory levels, buyer demand, financing trends, and comparable sales to develop credible opinions of value. Rising prices and changing demand patterns can influence an appraiser’s findings depending on the specific property and market area.

Should attorneys, accountants, and lenders rely on market headlines when determining property value?

No. Market headlines provide useful context, but property value is determined through detailed analysis of comparable sales, market conditions, and property-specific characteristics. A professional real estate appraisal provides a more reliable basis for financial, legal, and lending decisions.

Why are home sales slowing if prices are still rising?

Affordability is the primary factor. Although mortgage rates have eased slightly, higher home prices have increased monthly payments for many buyers, reducing overall purchasing activity.

What does 1.3 months of supply mean?

Months of supply is how long the current inventory would take to sell at the current sales pace. At 1.3 months, both single-family and condo segments were far below the five to six months typically associated with a balanced market.

Is this Week 24 data still current?

No. This report reflects Chicago MSA data for Week 24 of 2026 (mid-June). PahRoo publishes updated market reads regularly; treat this post as a dated snapshot, not a current reading.

Appraisal Support Built on Weekly Chicago Data

PahRoo tracks the Chicago MSA every week so our appraisal reports reflect the market as it stands on the effective date, not as it stood in a headline. Whether you are evaluating collateral risk, supporting litigation, planning an estate, or working through a complex transaction, our Chicago appraisers provide the independent analysis behind confident decisions, from our Lincolnwood office.

Real estate appraisal supporting family wealth transfer and estate planning decisions
Superadequacy in Estate Planning, When Cost Is Not Value

The kitchen cost $180,000. The market paid for about a third of it. That gap has a name in appraisal practice: superadequacy. It is the over-improvement, the feature built to a level the neighborhood does not support. In estate planning it shows up constantly, because families improve homes for themselves over thirty years. Then they value them by what was spent. The estate tax regulations, the trust documents, and the siblings at the table all need a different number.

By the end of this article, you’ll know:

  • What superadequacy actually means, and why long-held family homes are full of it
  • Why contractor invoices, insurance replacement cost, and the tax assessment are not fair market value, and which regulation says so
  • How an appraiser treats an over-improved property, and what executors should gather before the inspection

What Superadequacy Means, and Why Estate Files Are Full of It

The Dictionary of Real Estate Appraisal defines superadequacy as an excess in the capacity or quality of a structure or component, judged by market standards. So it is a form of functional obsolescence, not a bonus. The classic examples are the twelve-car garage in a market of three-car garages, or a 5,000 square foot house on a block of mid-century ranches.

The principle behind it is contribution. An improvement is worth what it adds to the value of the whole property, not what it cost to build. But that is not how families remember it. A $180,000 kitchen in a neighborhood where houses sell between $450,000 and $550,000 does not add $180,000. Buyers at that price point will not pay for it. So the market discounts it.

Estate files attract this problem for a simple reason. People who live in one house for decades improve it for their own use. The addition for the grandchildren, the elevator, the commercial-grade range, the finished basement with a second kitchen. None of it was built with a resale buyer in mind. Then the owner dies, and the family remembers every invoice.

Cost Is Not Value, and the Estate Tax Regulations Say So

For federal estate tax, property is included at fair market value on the date of death (or the alternate valuation date if the executor elects it). The regulation at 26 CFR 20.2031-1(b) defines that as the price a willing buyer would pay a willing seller, neither under compulsion, both reasonably informed. It adds that value is not a forced-sale price. It also says property may not be returned at its local tax-assessed value unless that figure happens to equal fair market value.

Read that against the records most estates hand over. Contractor invoices measure cost. The homeowner’s insurance policy carries replacement cost. That is what it would take to rebuild, not what a buyer would pay. The Cook County assessment is a mass-appraisal estimate the regulation specifically declines to accept on its own. None of these is the number the return asks for.

The same willing-buyer standard governs lifetime gifts. So when a parent deeds the over-improved lake house to one child, the gift value is what the market would pay for it, superadequacy and all. Whether that produces a reportable gift, and how basis carries, are questions for the CPA and the attorney. The appraiser’s job is to get the value right so those questions have a sound starting point.

Where the Over-Improvement Bites

Beneficiary equalization is where it hurts first. Suppose a will leaves the house to one sibling and cash to the other two. The intent is that everyone receives roughly equal value. If the estate carries the house at cost, the sibling taking the house is shortchanged. They receive an asset the market would not buy at that number. If the estate carries it at an old assessment, the reverse happens. Either way, someone has a grievance, and the executor is holding the pen.

Trust funding has the same exposure. A trust funded with real estate at an inflated number looks better on paper than it performs when the trustee eventually sells. Charitable planning is stricter still. A donation of real estate needs a qualified appraisal, and the appraiser must sign the form.

Then there is the return itself. An estate that reports a high value on an over-improved property is paying tax on value the market does not recognize. But the opposite error is worse. One that reports the assessment is inviting a question the regulation already answered. A supported appraisal, prepared for the estate and tied to the date of death, closes both doors. Our estate appraisal work is built for exactly that use.

How an Appraiser Handles a Superadequate Property

Two approaches do most of the work. In the cost approach, the appraiser estimates what it would cost to reproduce the improvements today. Then depreciation comes off, including a specific deduction for the superadequacy. The report shows the over-improvement, names it, and explains why it does not carry its cost into value.

In the sales comparison approach, the appraiser looks for what buyers actually paid for similar houses in the same market. If comparable sales with high-end kitchens sold for only modestly more than sales without them, then that difference is the adjustment, not the invoice. Often the honest answer is that the feature earns a small premium or none at all.

Chicago makes this vivid. A house in Lincolnwood or Skokie with a $400,000 renovation competes with other Lincolnwood and Skokie houses, not with Winnetka. The Cook County Assessor values residential property by statistical model at 10% of estimated market value, working from recorded characteristics. A renovation the model never saw does not move the assessment, and even when it does, the assessment is still not the estate’s number.

The report should say all of this in plain language. Counsel should be able to hand it to a skeptical beneficiary or an examiner, and the reasoning should hold without a phone call.

What Executors and Heirs Should Gather Before the Appraisal

If you are the executor or the child who ended up with the keys, three things help the appraiser and protect you. First, collect the improvement history: permits, invoices, and dates for anything major in the last fifteen years. But do not add them up and call the total value. Hand them over as a record of what was done and when.

Second, pull the current insurance declarations page and the most recent Cook County assessment notice. Both are useful context. Neither is the value, so do not average them with the invoices to get one. The appraiser reconciles the evidence; that is the service you are paying for.

Third, confirm the effective date with the attorney before ordering. Date of death, the alternate valuation date, or a gift date each produce a different report, so the date comes first. An appraisal to the wrong date is a document you pay for twice.

The Number That Keeps Siblings Speaking

Consider a hypothetical: a Wilmette house held for 34 years, with a two-story addition, a home elevator, and a kitchen the owner loved. The invoices total $610,000 over the years. The insurance replacement cost is higher still. The Assessor’s model, working from an older record, implies something lower than either. But none of those is what a buyer would pay in the current Wilmette market for that house with those features.

Order the appraisal early. Tie it to the date the attorney specifies, with the intended use stated as estate administration or gifting. Ask the appraiser to address the over-improvements directly rather than bury them in an adjustment grid. Then give the report to the CPA before the return is drafted, not after. The value question is the one that goes to the market. The tax and legal questions stay with the professionals who own them.

Is the Family Home Worth What Was Spent on It?

PahRoo prepares estate, trust, and gift appraisals across Chicago and the North Shore, tied to the date your matter requires and written to explain an over-improved property to a beneficiary or an examiner. Michael Hobbs, MAI, SRA, signs every report.

Request an Estate Appraisal

Frequently Asked Questions

What is superadequacy in an appraisal?

Superadequacy is an excess in the capacity or quality of a structure or component relative to what the market expects, as defined in the Dictionary of Real Estate Appraisal. It is a type of functional obsolescence. The improvement cost more than it contributes to market value.

Does an estate have to value the house at what the family spent on it?

No. For federal estate tax, 26 CFR 20.2031-1(b) requires fair market value on the applicable date: the price between a willing buyer and willing seller. Construction cost, insurance replacement cost, and the tax assessment are not that number.

Can the Cook County assessment be used on the estate tax return?

Only if it happens to equal fair market value on the valuation date. The regulation says property may not be returned at its local tax-assessed value otherwise. In Cook County the assessment is a mass-appraisal estimate, so an estate-purpose appraisal is the supported route.

How does an appraiser account for an over-improvement?

In the cost approach, by deducting functional depreciation for the superadequacy. In the sales comparison approach, by adjusting only for what comparable buyers actually paid for the feature, which is often much less than it cost. The report should explain both.

What should an executor give the appraiser?

The improvement history with permits, invoices, and dates; the insurance declarations page; the latest assessment notice; and the effective date confirmed by the attorney. Provide them as records, not as a value estimate.

Estate and Trust Appraisals From the North Side and the North Shore

From our Lincolnwood office, PahRoo appraises family homes, two-flats, and small commercial holdings for estate attorneys and CPAs throughout Chicago and Cook County. Our residential appraisals are written for estate administration, gifting, and trust funding, with the effective date and the treatment of any over-improvement stated plainly. When the estate includes income property, our commercial appraisal team handles it from the same office.

etrospective market value appraisal analysis for tax attorneys
Retrospective vs Current Market Value for Tax Cases

A partner calls and asks for an appraisal. The first question back is never about the property. It is about the date. Retrospective vs current market value is not a preference either side gets to express. The filing, the statute or the court fixes the date, and everything else follows from it.

By the end of this article, you’ll know:

  • Why a Cook County property tax appeal is a retrospective assignment, not a current one
  • What the Assessor’s Rule 14 actually requires an appraisal to contain
  • What the IRS uses for estate property, and why a sub-threshold estate may still need the work

Retrospective vs Current Market Value, the Short Version

Both are opinions of market value. But the effective date is different, and that difference drives everything else.

A current appraisal answers what the property is worth now, using what the market is doing now. A retrospective appraisal answers what it was worth on a fixed date in the past.

So for the second one, the appraiser rebuilds the market as of that date. Sales that had already closed. Rents in place then. Condition and use as they stood, along with the information a buyer could reasonably have had at the time.

One thing worth saying plainly to clients: a retrospective value is not a current value adjusted backwards. It is a separate analysis on a separate data set, and it usually takes longer than the current-date version of the same assignment.

In Cook County, a Tax Appeal Appraisal Is Always Retrospective

Illinois assessments attach to a lien date of January 1. The Official Appeal Rules of the Cook County Assessor use that phrase throughout, and every evidence rule in them counts forward or backward from it.

Think about where that puts you. When your township opens, January 1 is already months behind. By the time a file reaches the Board of Review, longer. At PTAB, longer still.

So an appraisal dated today answers a question nobody in the process asked. The effective date belongs on January 1 of the appeal year, and the report has to say so on its face.

The rules also put an outer limit on staleness. Under Rule 14, an appraisal offered in support of an appeal should be dated within the triennial period for that property, or at least no more than two years before the lien date of the appeal year.

What Rule 14 Asks the Report to Contain

This is the part worth reading before you commission anything, because it shapes the engagement. Rule 14 says an appraisal has to pertain to the property’s highest and best use, comply with USPAP and Illinois law, and be credible under USPAP.

Then the specifics. An original color photograph of the front of the subject, date stamped, plus photographs of every comparable used in the analyses. The PIN for the subject, and the PIN for every property used. Sales and market data that are available, reasonable and truly comparable, with no cherry picking. Where the income approach appears, cap rates drawn from relevant current market data.

And then the one that catches firms out. Filers must provide all appraisal reports and other valuation reports on the subject prepared within two years before the lien date, including reports prepared for financing or management purposes. The bank’s appraisal from fourteen months ago goes in the file whether it helps the argument or not. Better to know that before the engagement than after.

Two consequences round it out. An appraisal believed to be in gross violation of USPAP may go to the IDFPR, and it will not count as credible evidence. And the Assessor does not re-review its own appeal decisions, so the next stop is the Board of Review.

Date of Death Fixes the Estate Side

The federal rule is simpler to state, but it lands in the same place. The IRS treats the gross estate as an accounting of what the decedent owned at the date of death, valued at fair market value. Not what was paid for it. Not what it was worth when it was acquired.

For 2026 the filing threshold sits at $15,000,000. So a lot of people assume that nothing below it needs an appraisal.

Look at portability before you accept that. Passing a deceased spouse’s unused exemption to the survivor requires a timely filed estate tax return. So estates well under the threshold file anyway, and a filed return still needs values that hold up. Whether a given estate should file is counsel’s call, not ours, but the valuation work follows the decision either way.

These assignments are also retrospective almost by default. The engagement arrives after probate opens, sometimes years after, and litigation over an estate can push the effective date back further still.

When a Current Value Is the Right Instrument

Plenty of matters do call for today. Financing and collateral review. A sale or a partner buyout priced at present terms. Damages measured as of now, too, and settlement posture heading into mediation.

The test is the same one every time. What date does the governing rule, filing or order attach to? Once you answer that, the assignment writes itself.

One practical note for matters that need both. A single engagement can carry two effective dates, and it often should. Say so at the outset rather than halfway through, because the scope of work drives the research, the timeline and the fee.

Fix the Date Before You Order the Report

Three questions settle almost every one of these calls, so they are worth asking first. What date does the governing rule attach to. What does the body reading the report require it to contain. And what other valuations already exist on this property.

The third one catches people. A report your client never commissioned can still land in the record, and in Cook County the rules say it has to. Knowing that on day one changes how the file gets built.

Working a File With the Date Already Fixed?

Send us the matter, the date, and the body that will read the report. We will tell you what the assignment actually is before anyone commits to a scope.

Request an Appraisal

Frequently Asked Questions

What is a retrospective appraisal?

It is an opinion of market value as of a specific past date, rather than as of today. The appraiser reconstructs the market as it stood then, using sales that had closed, rents in place, and the property’s condition and use at the time, rather than current conditions.

Can an appraiser adjust today’s value back to an earlier date?

No, and a report that appears to do so tends to draw scrutiny instead. A retrospective assignment is a separate analysis built on data from the effective date, not a current value indexed backwards.

What effective date does a Cook County property tax appeal use?

The lien date, which is January 1 of the appeal year. The Assessor’s appeal rules count from that date throughout, and Rule 14 asks that an appraisal be dated within the triennial period for the property, or at least no more than two years before it.

Does an estate under the filing threshold still need a date-of-death appraisal?

Often, yes, if portability is in play. Portability of a deceased spouse’s unused exemption requires a timely filed estate tax return, and a filed return needs values that hold up. Whether to file is a question for the estate’s attorney.

Can one appraisal cover two effective dates?

One engagement can, and for matters that need both a historical and a present value it usually should. Flag it at the outset, because two dates mean two sets of research and a different scope of work.

Appraisal Work Built for an Attorney’s File

PahRoo works out of Lincolnwood and covers Chicago and Cook County, along with Dallas, Philadelphia, Phoenix and Naples. Michael Hobbs, MAI, SRA, signs every report, and he is also available for testimony. Our commercial appraisal practice handles retrospective and current assignments for appeals, estates and litigation. There is more on the shifting politics of Chicago commercial tax appeals, and on what our Chicago coverage includes.

NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712