Tag: Chicago commercial property appraisal

Request a quote

Our blog

Latest news
& events

Partially leased retail strip center being appraised for a commercial refinance
What to Expect From a Commercial Refinance Appraisal

Thinking about refinancing a building you own? Before a lender sets the new loan amount, it needs a supported opinion of what the property is worth today. That is the job of the commercial refinance appraisal, and it shapes how much you can borrow, how much cash you can take out, and sometimes whether the deal works at all.

By the end of this article, you’ll know:

  • How the appraised value sets the size of a refinance loan
  • Who orders the appraisal, and when a new one may not be needed
  • What owners and lenders can do to keep the process moving

How a Commercial Refinance Appraisal Sets Your Loan Amount

Lenders look at two things in a refinance. First, can the property’s income cover the payment? Second, is the building worth enough to secure the loan? According to the Interagency Appraisal and Evaluation Guidelines, the ability to repay comes first. Still, a bank must also consider the value of the real estate behind the loan.

That value usually caps the loan through a loan-to-value limit in the lender’s policy. Consider a hypothetical. A lender caps the loan at 70 percent of value, and your building appraises at $3,000,000. The most it would lend is $2,100,000. If you still owe $2,300,000, you would need to bring $200,000 to closing or find another lender.

So a few percent in value can move real money. That’s why it helps to understand what goes into the number before the appraiser shows up.

Your Lender Orders the Appraisal, Not You

This part surprises a lot of owners. The bank picks and engages the appraiser, and federal guidance says it can’t use a report the borrower ordered. Our article on commercial appraisals for lending covers those independence rules in detail.

For a refinance, the practical point is simple. An appraisal you order yourself can help you decide whether refinancing makes sense before you talk to lenders. It just won’t stand in for the appraisal the bank orders for the loan.

When a Refinance May Not Need a New Appraisal

Some refinances skip the full appraisal. Under the OCC’s appraisal rule at 12 CFR 34.43, an existing loan at the same bank can be refinanced without one in either of two cases. In the first, no new money goes out beyond reasonable closing costs. In the second, nothing obvious and material has changed in the market or the property that threatens the bank’s collateral.

The same rule exempts commercial real estate deals of $500,000 or less. In both cases, though, the bank still needs an evaluation, which is a simpler written estimate of market value. A bank can also order a full appraisal anyway, and the guidelines point that way for higher risk loans.

Two more points matter here. Moving the loan to a new lender takes it outside the existing loan exemption, since that exemption only covers credit already at the lending bank. And a cash-out refinance adds new money, so it qualifies only if the market and the property haven’t materially changed. The FDIC and the Federal Reserve have parallel rules for the banks they supervise, and credit unions follow the NCUA’s version.

What Moves the Value of a Leased Building

For most income property, the appraiser leans hard on the income. Our guide to the income approach shows how rent turns into value. Our explainers on net operating income and cap rates cover the two numbers that drive it.

Leases count too. The federal guidelines require lending appraisals to analyze deductions and discounts for partially leased buildings and non-market lease terms. So a half-empty building, or a big tenant paying well under market rent, will show up in the number.

Time plays a part as well. The guidelines list factors that can make an older appraisal stale, including the passage of time, changes in financing terms, lack of maintenance, and shifts in cap rates and lease terms. In other words, what your building was worth at purchase may not be what a refinance lender sees today.

Who occupies the building matters too. If your own company fills the space, our piece on owner-occupied and investment property appraisals explains why the two get valued differently.

How Owners Can Prepare for the Appraisal

You can’t pick the appraiser, but you can make the work go smoother. Have a current rent roll, every lease with its amendments, recent operating statements, and a list of capital improvements ready before the inspection. Our lending article above has a fuller checklist.

A refinance adds one more step. Find your last appraisal and write down what has changed since. A new roof, a lease renewal at a higher rent, or a tenant who moved out are exactly the facts that decide whether the old value still holds. So hand them to your lender early, before anyone has to ask.

One thing to leave out is a target value. The guidelines tell lenders not to give an appraiser a predetermined value, a loan amount, or a target loan-to-value ratio. For what happens next, see what goes into a commercial appraisal report and how long a commercial appraisal takes.

For Lenders, Set Up the Refinance Assignment Right

Bankers already know the ordering rules, and our lending article covers them. A refinance adds two decisions of its own.

First, decide whether the existing appraisal still holds. The guidelines let a bank use an existing appraisal for a later transaction. However, the credit file should show the facts and analysis behind that call, weighed against the staleness factors listed above. So document the check, even on a renewal with no new money that is exempt from a new appraisal.

Second, match the value premise to the new loan. If cash-out proceeds fund a renovation or a lease-up, the guidelines say a bank would generally ask for the as-is value. As applicable, it would also ask for a prospective value upon completion or stabilization.

If the building sits outside Cook County, our Dallas, Philadelphia, Phoenix, and Naples teams take commercial assignments in those markets. In Cook County, our Chicago appraisal team handles the work.

Planning a Refinance on a Building You Own?

Your lender orders the appraisal behind the loan. If you want a supported value first, to plan or before you talk to lenders, PahRoo can prepare one. Bankers can engage us for refinance assignments too.

Request a Commercial Appraisal Quote

Frequently Asked Questions

What is a commercial refinance appraisal?

It is an appraisal a lender uses to decide how much it will lend on a new loan secured by income-producing or business property. The appraised value usually caps the loan through the lender’s loan-to-value limit.

Can my bank reuse the appraisal from when I bought the building?

Sometimes. A bank can rely on an existing appraisal for a later loan if it documents why the value still holds. The passage of time, lease changes, or a shift in cap rates can make an older value stale.

Does every commercial refinance need a new appraisal?

No. For an existing loan at the same bank, federal rules may allow an evaluation instead when no new money goes out or when the market and property haven’t materially changed. The bank decides which it needs.

What should I have ready for a commercial refinance appraisal?

A current rent roll, every lease and amendment, recent operating statements, and a list of capital improvements. Plan for access to the whole building, including vacant space.

Does a cash-out refinance need a new appraisal?

Not always. At the same bank, a cash-out refinance can skip a new appraisal only if nothing obvious and material has changed in the market or the property. Otherwise it generally needs one, or an evaluation for smaller loans.

Refinance Appraisals That Hold Up in Credit Review

When a lender needs a value it can underwrite, PahRoo Appraisal & Consultancy prepares commercial appraisals for banks, investors, and owners in Chicago and Cook County, Dallas, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, signs our Illinois reports. See our commercial appraisal services for the property types we cover.
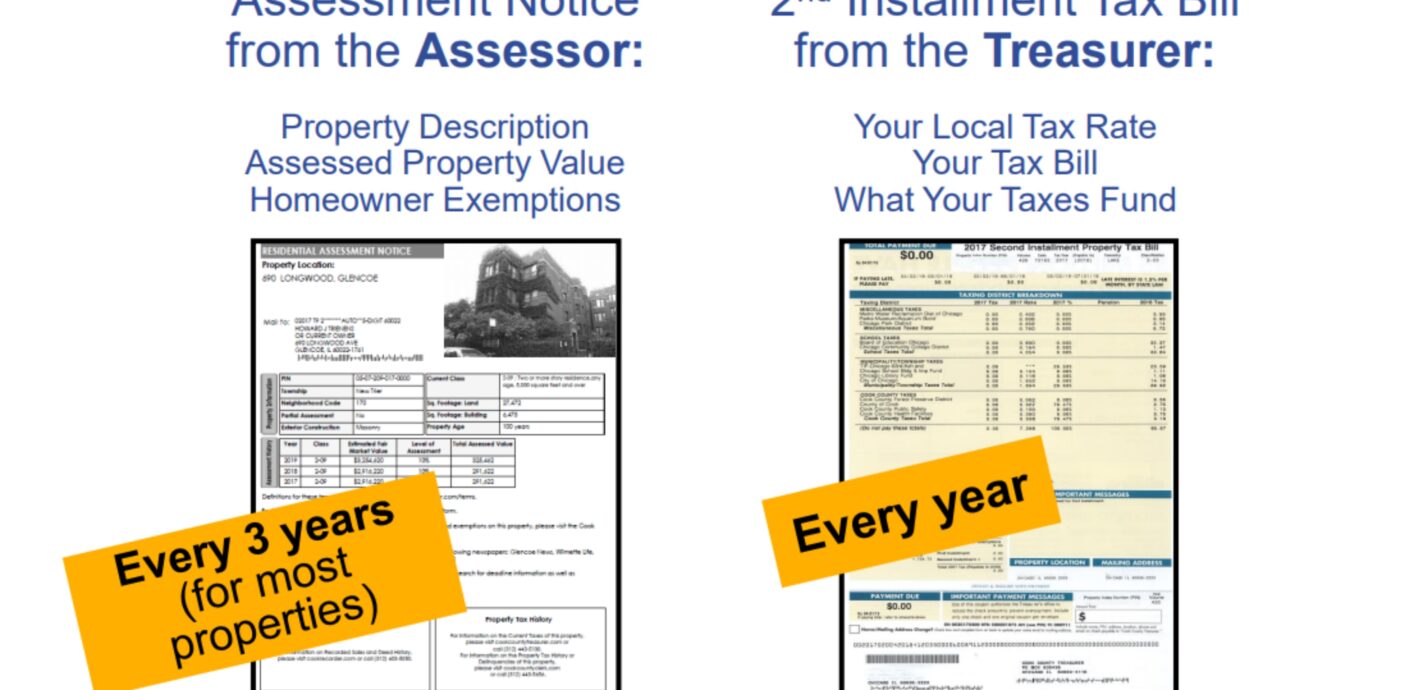
2026 Cook County reassessment notice used for property tax appeal appraisal
Commercial Refinancing Cliff 2026, What the Data Says

The commercial refinancing cliff turned out to be a slope. That is not the same as flat ground. Mortgage Bankers Association data puts $875 billion of commercial and multifamily debt maturing in 2026, down from $957 billion in 2025. Another $652 billion sits behind it in 2027. The peak has passed. What remains is a long stretch of loans written at rates that no longer exist, many already extended once. Every one of them arrives at a credit committee that will ask what the property is worth today.

By the end of this article, you’ll know:

  • What MBA’s 2026 maturity survey actually shows, by property type and by lender type
  • Where the equity gap comes from when a loan matures into a higher-rate, tighter-underwriting market
  • Why an appraisal ordered months ahead of maturity changes the conversation for both the lender and the borrower

What the Commercial Refinancing Cliff Looks Like in the Data

The Mortgage Bankers Association released its 2025 Commercial Real Estate Survey of Loan Maturity Volumes in February. Seventeen percent of the $5.0 trillion in outstanding commercial mortgages, or $875 billion, matures in 2026. That is a 9 percent decrease from 2025. MBA’s chief economist called 2025 a transition year. Lenders stopped simply extending loan terms, and the wall of scheduled maturities began to shrink.

The distribution matters more than the headline. Among property types, 30 percent of hotel loans come due this year. Industrial follows at 23 percent, then office at 17, health care at 15, and multifamily at 13. Among lender types, depositories carry $396 billion of the 2026 maturities. CMBS, CLO, and other securitized loans carry $200 billion. Credit companies and warehouse lenders carry $163 billion. Life insurers hold $76 billion. Agency and FHA multifamily paper, by contrast, has only $39 billion coming due.

So the refinancing question in 2026 is not spread evenly. It sits with banks and non-bank lenders, and with the property types that borrowed hardest in the low-rate years. MBA also notes that the figures are unpaid balances as of December 31, 2025. So the amounts at maturity will be somewhat lower. The direction is still the same.

Why a Maturing Loan Becomes an Equity Gap

A loan written in 2019 or 2021 was sized against a value, a rate, and an income stream. All three looked different from today. When it matures, the lender does not care what the property was worth then. The new loan is sized against current value, current net operating income, and current rates.

Three things compress at once. Higher rates mean the same NOI supports less debt, because coverage has to hold. Tighter underwriting means lower loan-to-value limits and more conservative vacancy and expense assumptions. And where value has fallen, the loan-to-value math starts from a smaller number. The gap between what the new loan will support and what the old loan still owes is the equity gap. Someone has to fill it: the borrower with cash, a partner with capital, or the lender with a restructure.

The loans that were extended in 2024 and 2025 are the ones most exposed now. An extension bought time; it did not change the rate the property has to refinance into. MBA expects the Federal Reserve to be near the end of its rate-cutting cycle. So the relief many borrowers were waiting for is largely already priced in. Our commercial appraisal work in 2026 has increasingly been on exactly these files.

What Credit Committees Are Asking For

The underwriting questions have not changed much. What has changed is how little tolerance there is for assumptions. Committees want sustainable NOI, not the peak year. They want vacancy assumptions that reflect the submarket, verified lease terms and rollover exposure, and normalized expenses that account for insurance and tax increases. Then an exit cap rate that would survive a skeptic.

A lender who orders the appraisal early gets those answers before the file is in front of the committee. A borrower who orders it early gets them before the lender does. That is the better position to negotiate from. Either way, the report replaces the argument. Instead of debating whether the 2021 value still holds, both sides work from a current opinion with the comparables and income analysis laid out.

This is also where property tax belongs in the conversation. A Cook County commercial assessment that runs above market value inflates the expense line. That drags NOI and shrinks the loan the property can support. An appraisal prepared for the refinance often becomes the evidence for an appeal, so the two efforts pay for each other.

Not Every Property Type Faces the Same Cliff

The maturity shares tell you where the pressure concentrates. Hotels carry the largest share of 2026 maturities by property type. Hotel income is also the most sensitive to travel demand and operating cost. Industrial has the second largest share. After years of strong rent growth, underwriting has become more careful about whether that growth continues in a given corridor.

Office is the type everyone expects to see on this list, and 17 percent of office loans do mature this year. The variation between buildings is wide. A leased suburban building and a half-empty tower downtown are both office. They will not appraise or refinance the same way. Multifamily has the smallest share maturing among the major types. Much of that is agency paper with ready refinancing options.

The lesson for a lender or an owner is that the headline number tells you very little about your loan. The property’s own income, its lease roll, its submarket, and its condition decide the outcome. That is what an appraisal is for. It is also why a generic model does not settle a credit committee.

If Your Loan Matures in the Next 18 Months

If you own the property, or advise the owner, start earlier than feels necessary. Ninety days before maturity is too late to source new capital, restructure with a partner, or bring in a second lender. Six to nine months out is when an appraisal gives you room to act on what it says.

Bring the appraiser the full picture. That means the rent roll, twelve months of operating statements, the current tax bill and any pending appeal, capital spending since the last appraisal, and the existing loan terms. An appraisal is only as good as the income it can verify. Then take the report to the lender before the lender’s own appraiser has been ordered. Walking in with a supported number and a plan for any gap is a different meeting than walking in with a hope.

A Slope Rewards the Prepared

The refinancing wave did not break all at once, and MBA’s data says the worst of it is behind the market. What is left is steadier and longer: $875 billion this year and $652 billion next year, much of it already extended. Most of it sits with the banks and private lenders who have the least room to pretend the 2021 value still stands.

For a lender, the early appraisal is how a maturing loan becomes a workable refinance instead of a workout. For an owner, it is how an equity gap becomes a known number with a plan attached, not a surprise at the closing table. Either way, the number has to be current, supported, and written so a credit committee can test it.

Maturing in 2026 or 2027? Know the Number First.

PahRoo prepares commercial appraisals for refinancing, restructuring, and credit review across Chicago and the collar counties, with the income analysis and comparable sales laid out for committee scrutiny. Michael Hobbs, MAI, SRA, signs every report.

Request a Commercial Appraisal

Frequently Asked Questions

How much commercial debt matures in 2026?

According to the Mortgage Bankers Association’s 2025 Commercial Real Estate Survey of Loan Maturity Volumes, $875 billion, or 17 percent of the $5.0 trillion outstanding, is scheduled to mature in 2026. That is 9 percent less than the $957 billion scheduled for 2025, with $652 billion scheduled for 2027.

Is the commercial refinancing cliff over?

MBA’s data suggests the peak of the maturity wave has passed, but the volume remains elevated and many 2026 maturities are loans that were already extended once. The pressure has shifted from size to duration.

What is an equity gap in a commercial refinance?

The difference between the balance owed on the maturing loan and the amount a new loan will support at current value, current income, and current rates. The borrower, a capital partner, or a restructure has to cover it.

Which property types have the most loans maturing in 2026?

By share of outstanding balance, hotel loans lead at 30 percent, followed by industrial at 23 percent, office and health care at 17 and 15 percent, and multifamily at 13 percent, per MBA.

When should an owner order an appraisal before maturity?

Six to nine months out. That leaves time to act on the result: source capital, negotiate a restructure, pursue a tax appeal, or approach a second lender. Ninety days before maturity is usually too late.

Commercial Appraisals Built for Credit Review

PahRoo appraises office, industrial, retail, multifamily, and mixed-use property for lenders and owners across Chicago and Cook County. Our commercial appraisal reports are written for refinancing, restructuring, and litigation, with the income approach shown in full. The same team handles Cook County property tax appeal appraisals, which often start from the same refinance file.

NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712