Tag: Real Estate Valuation

Request a quote

Our blog

Latest news
& events

Commercial property tax appeal strategy showing how rising levies impact tax bills
Why Commercial Property Tax Bills Still Rise

Winning the Appeal Isn’t the Finish Line: Why Commercial Property Tax Bills Still Rise

For experienced property tax attorneys, a successful appeal has traditionally meant a clear outcome: lower assessed value, lower tax bill.

Increasingly, that relationship no longer holds.

Across major U.S. markets including Chicago, Philadelphia, Dallas, Naples, and Phoenix, attorneys are encountering a growing disconnect between assessment victories and actual tax relief. Clients win the appeal, yet the tax bill still increases.

This isn’t a valuation failure.
It’s a levy-driven reality that’s reshaping how effective counsel must advise commercial property owners.

The Structural Issue Attorneys Are Now Forced to Address

In levy-driven tax systems, taxing bodies determine revenue needs first. Tax rates then adjust to meet those levies, regardless of how individual assessments move. Cook County Treasurer – Property Tax System Primer, explains levy-driven systems, how levies are set, and how rates are derived across taxing districts.

Our review of 275 commercial property tax bills post-appeal showed:

  • 38% increased year over year
  • Even when assessed values were reduced by more than 15%

The culprit wasn’t weak advocacy.
It was rising levies from school districts, municipalities, and pension-obligated entities that quietly outpaced assessment reductions.

For attorneys, this creates a professional risk:

Winning the case, but losing client confidence.

How This Plays Out by Market (Attorney Perspective)

While the mechanics are universal, each market applies pressure differently and sophisticated counsel now accounts for that nuance. These dynamics are documented across property tax systems nationwide, where local governments levy property taxes as a major source of local revenue.

Chicago (Cook County) 

Aggressive levy growth, overlapping taxing districts, pension funding obligations, and frequent TIF reallocations make Cook County the most visible example. Appeals focused solely on value often fail to anticipate rate compression. Check Cook County Assessor System Overview — for local system nuance in Chicago

Philadelphia

School district funding demands and shifting assessment practices can neutralize appeal gains, particularly when levy increases coincide with reassessment cycles.

Dallas

Rapid municipal growth, infrastructure expansion, and school funding needs create levy pressure that can dilute even substantial assessment reductions.

Naples (Collier County)

Special districts, redevelopment initiatives, and targeted funding measures can quietly shift tax burdens, especially in high-value commercial corridors.

Phoenix (Maricopa County)

Voter-approved funding measures and expanding tax bases redistribute liability, requiring appeal strategies to be evaluated alongside revenue modeling.

The common thread: 
Assessment appeals are necessary, but no longer sufficient on their own.


How Leading Attorneys Are Reframing Their Advisory Role

The most effective attorneys are adapting by expanding the scope of counsel, not abandoning appeals.

They are:

    • Using district-specific levy forecasts to set expectations before filing
    • Engaging earlier in budget hearings and abatement discussions
    • Coordinating with commercial property appraisal teams to identify when appeals are technically winnable but strategically ineffective

In one downtown case, a law firm helped a client avoid a six-figure exposure by pairing its appeal strategy with a levy-impact model that flagged a mid-cycle rate increase tied to a local referendum, before it surfaced on the tax bill.

That outcome didn’t come from litigation skill alone. It came from anticipating the revenue side of the equation.

Why This Matters for Attorney-Client Relationships

Clients are no longer satisfied with reactive explanations after the bill arrives.

They expect counsel to:

  • Explain why outcomes differ from expectations
  • Flag risks before decisions are locked in
  • Provide context beyond the assessment notice

Attorneys who incorporate levy awareness into their advisory process are:

  • Better positioned to manage expectations
  • Less exposed to second-guessing
  • More likely to be viewed as strategic partners, not procedural advocates
A More Defensible Way to Advise on Commercial Property Tax

As levy-driven pressure intensifies, the attorneys who stand out will be those who prepare clients for both sides of the tax equation:

    • Assessment
    • Revenue demand

That dual-lens approach is quickly becoming the difference between “we won the appeal” and “we protected the client.”

Clients don’t expect certainty, but they do expect clarity. Attorneys who can explain why a successful appeal doesn’t always translate into tax relief will continue to set themselves apart.

Support Your Commercial Property Tax Appeal Strategy with Levy Intelligence

If you represent commercial property owners in Chicago, Philadelphia, Dallas, Naples, or Phoenix, winning the appeal is only part of the equation. In levy-driven tax environments, assessment reductions alone don’t always translate into lower tax bills.

Request a Levy Impact Analysis to:

    • Identify where commercial property tax appeal wins may be offset by rising levies
    • Strengthen client communication and expectation-setting before filing
    • Align valuation and appeal strategy with real-world tax outcomes across local taxing districts

Equip your clients with clarity and your practice with a defensible, data-driven advisory edge.
 

Downtown Chicago Office Tax Appeals: Why 2024 Assessments Still Miss the Mark


Cook County’s 2024 reassessment pushed many Class 5A downtown commercial properties up by an average of 21–22%, despite an office market that continues to struggle. Sub-50% occupancy, declining rents, and tenant downsizing have left even prime towers under pressure. Now, as those assessments move through the appeal process in 2025, the disconnect between assessor assumptions and market reality remains clear.

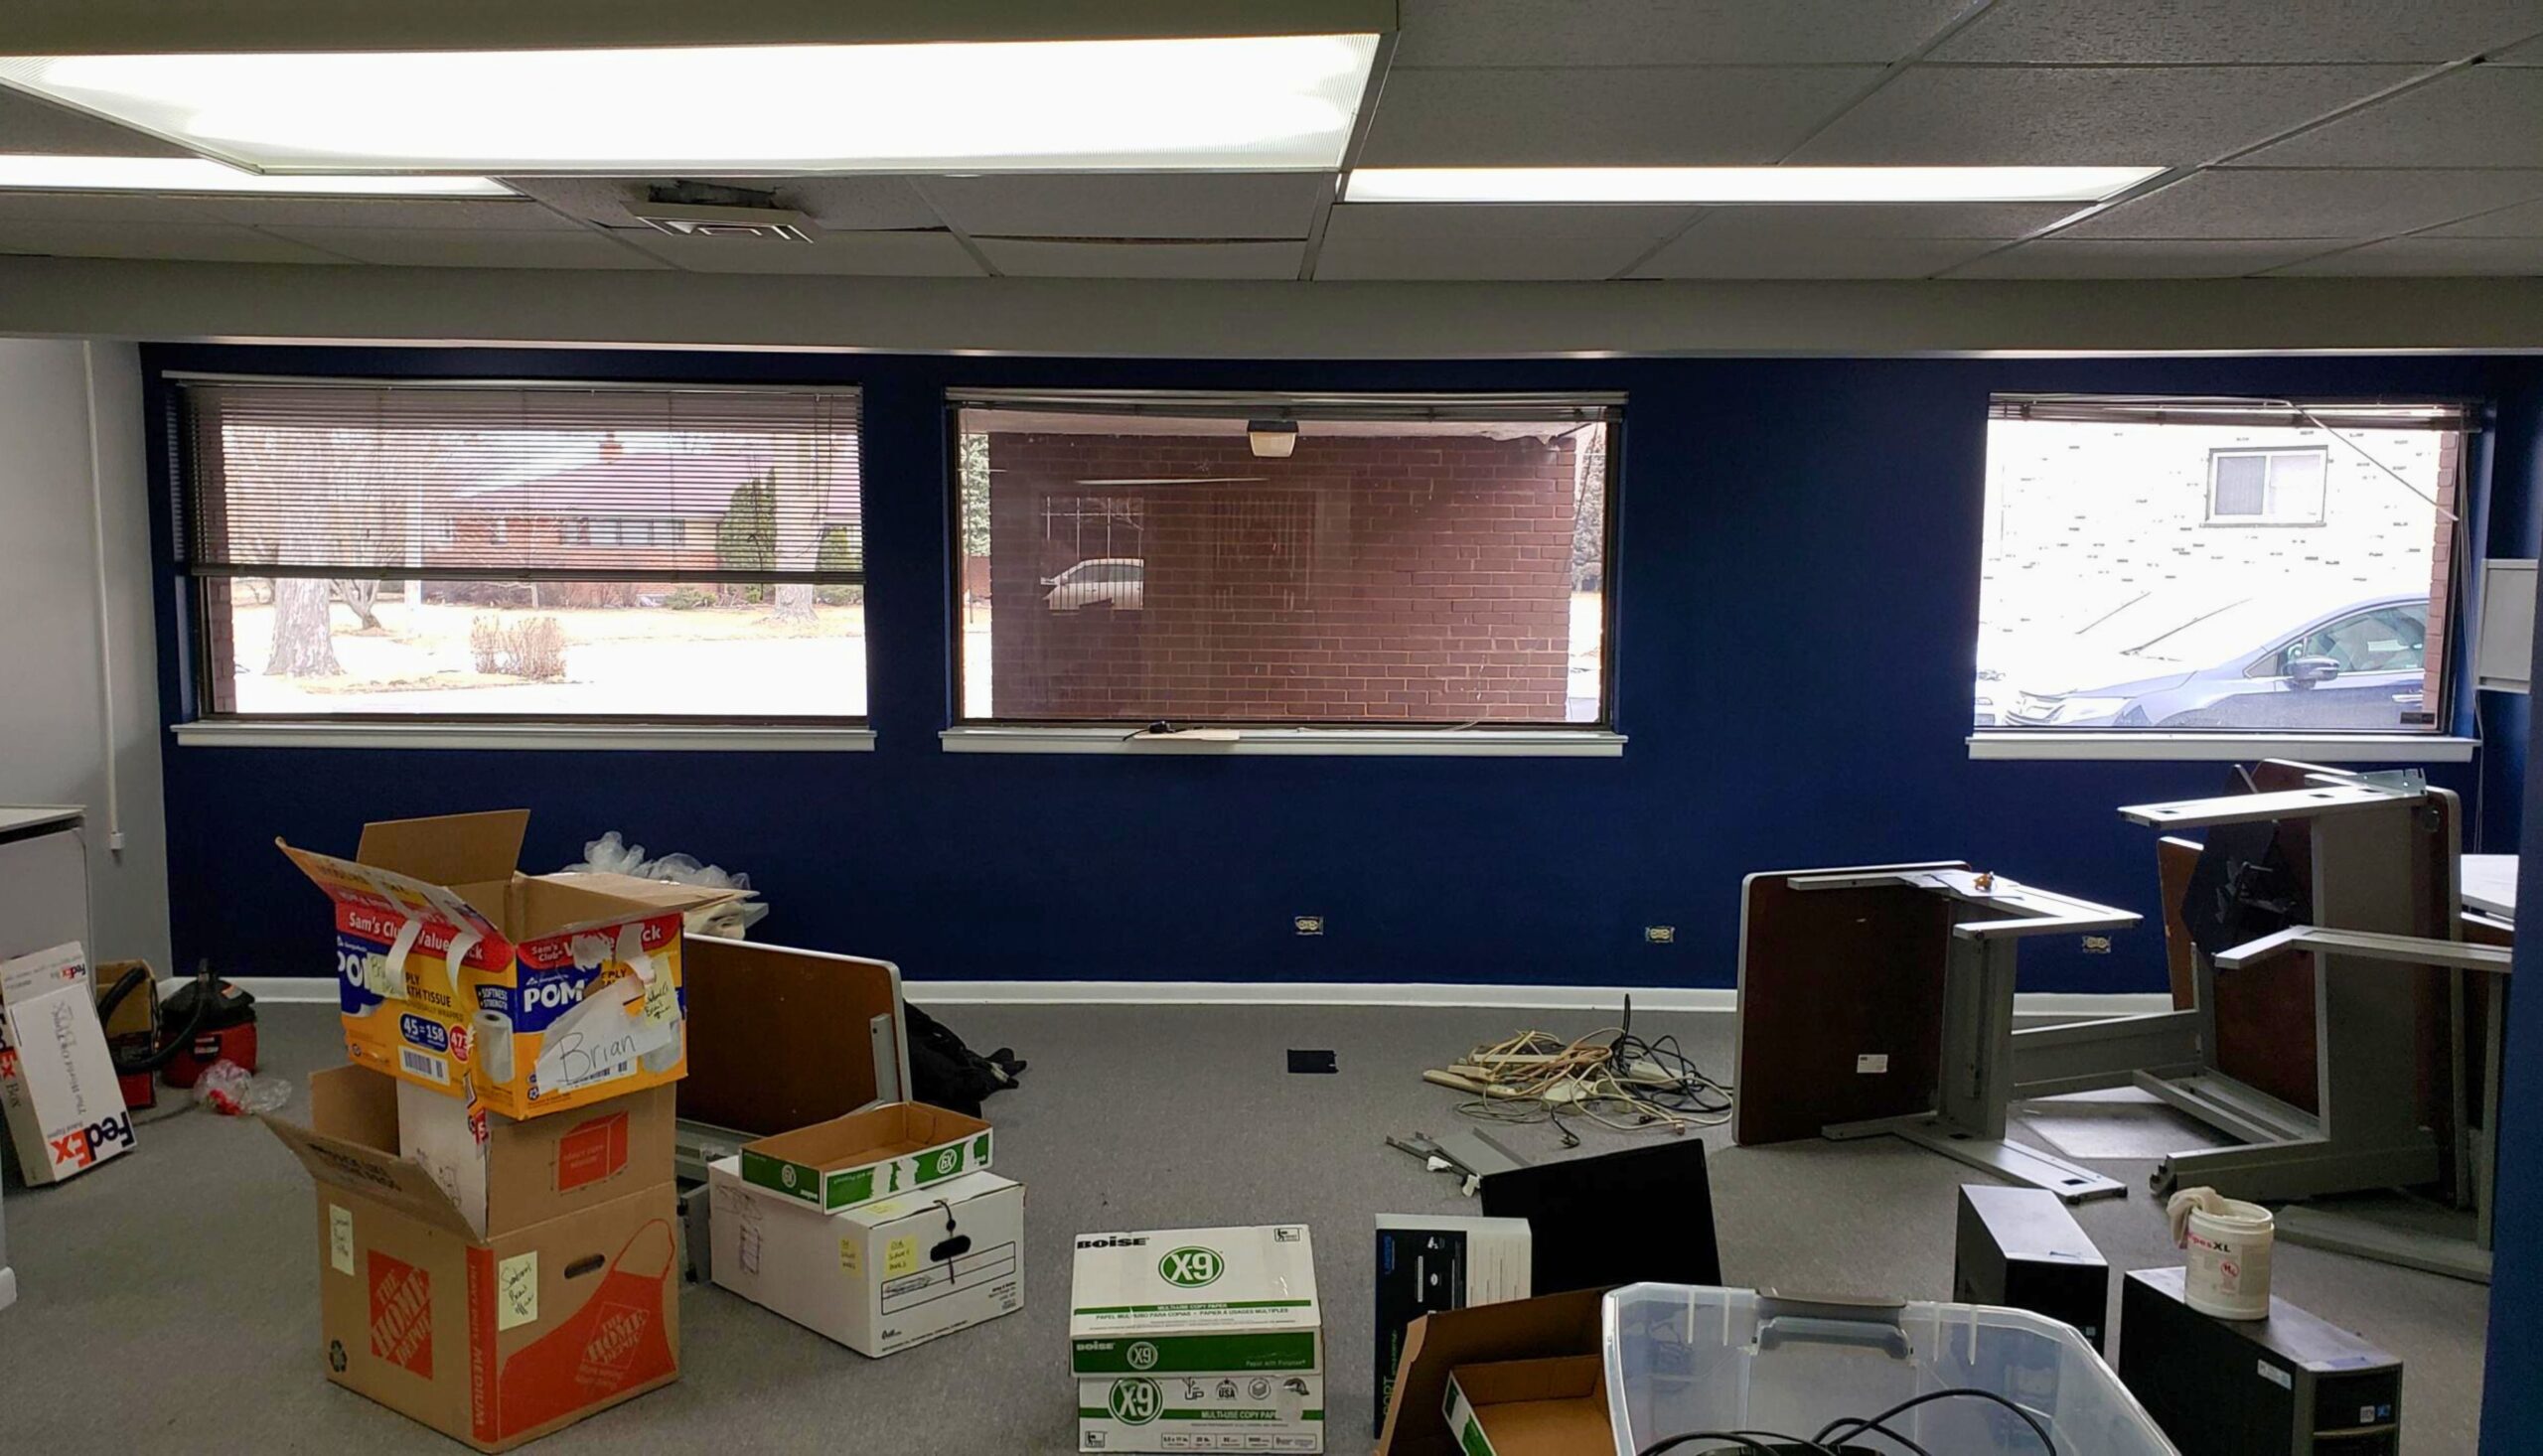
acant office floor in Chicago showing high vacancy rates impacting property values

2024 Cook County Assessments vs. Market Reality

Many buildings that saw values rise in 2024 have not rebounded operationally. Owners are facing:

  • Vacancy rates at or above 50% in numerous assets
  • Rent concessions and free rent packages just to maintain tenancy
  • Slow absorption as new leases trail far behind pre-pandemic demand

These challenges have left assessed values out of sync with actual income streams and investor expectations.

Why Owners Should Still Consider Appeals in 2025

While some may think the window has closed, viable appeal opportunities remain. Attorneys and owners can strengthen appeals with:

  • Occupancy and income documentation that shows sustained loss in 2023–2025
  • Cap rate evidence from recent downtown office sales, where risk premiums have expanded significantly
  • Deferred maintenance and capital expenditure needs that drag on net operating income

Appeals framed with real-world underwriting rather than abstract valuation models tend to resonate most strongly at the Board of Review.

The Last Clean Window to Act

Mid-2025 may represent the final clean opportunity for many downtown office assets to correct inflated 2024 assessments. Once the Board of Review cycle concludes, later adjustments become far more limited. Filing now ensures that property owners capture current market conditions before tax bills are locked in.

How PahRoo Appraisal & Consultancy Helps

At PahRoo, we partner with attorneys and office owners to create compelling, evidence-based appeals. Our team provides:

  • Updated comparable sales, rent rolls, and leasing trends
  • Market-supported capitalization rates reflecting today’s risk climate
  • Property-specific adjustments for repositioning costs or underperformance

Our approach ensures appeal arguments are credible, data-driven, and tailored to each property’s unique challenges.

Ready to Discuss Your Appeal?

If you or your clients own downtown office property in Cook County, now may be the last clean window to appeal 2024 assessments.

Luxury home interior representing a luxury real estate appraisal assignment
Luxury Real Estate Appraisal as the Buyer Pool Changes

Walk into a high-end open house today and the buyers look different than they did a decade ago. Younger, more often women buying on their own, and asking about smart systems instead of formal dining rooms. That shift changes more than marketing. It changes what a luxury real estate appraisal has to measure, and it is about to make documented values matter more than ever, because the largest wealth transfer in history is moving property along with the money.

By the end of this article, you’ll know:

  • Who the new luxury buyers are, and how much wealth is heading their way
  • Why high-end homes are the hardest properties to value, and where online estimates fail
  • Why the wealth transfer itself creates appraisal needs for estates, gifts, and trusts

The Buyers Are Changing, and So Is Luxury Real Estate Appraisal

For years, the top of the market belonged to Baby Boomers and Gen X. That is ending. Roughly $124 trillion in assets is projected to change hands through 2048, with about $106 trillion going to heirs, mostly Gen X, Millennials, and Gen Z, according to Cerulli Associates research summarized by Merrill and Bank of America Private Bank. Some of that inheritance arrives as cash that buys homes. A lot of it arrives as the homes themselves.

For a luxury real estate appraisal, the buyer pool is not trivia. Value is what the probable buyer would pay, so when the probable buyer changes, the analysis has to follow. An appraiser who still assumes a 1998 buyer profile will misread what today’s market rewards and what it ignores.

Why Luxury Homes Are the Hardest to Value

High-end properties break the tools that work everywhere else. Automated estimates lean on volume and similarity, and luxury homes offer neither. Sales are few, features are custom, and no two properties match. A $400,000 house might have a dozen recent comps within a mile. A $4 million house might have three loosely similar sales in a year, spread across neighborhoods.

So the appraiser has to work harder. That means widening the search area with care, verifying the terms behind each sale, adjusting for one-of-a-kind features with market support, and accounting for longer exposure times at the top of the market. This is the segment where designations and experience separate a defensible residential appraisal from an expensive guess.

What the New Buyers Pay For, and What They Do Not

Younger luxury buyers consistently favor smart-home technology, wellness spaces, energy performance, and turnkey condition. Sellers hear that and assume every upgrade returns its cost. The appraisal answers a colder question: what does the market actually pay for the feature?

Some of these amenities now carry real contributory value in the right submarkets. Others read as personal taste that the next buyer will renovate away. The discipline is the same one we described for green property features: cost is not value, and market evidence decides. In luxury, where a single feature can represent six figures, that distinction gets expensive to ignore.

Women Are a Growing Share of the Buyer Pool

The other structural shift is who holds the wealth. Women in the United States are projected to control about $34 trillion in assets by 2030, roughly 38 percent of the total, per McKinsey research. More high-end purchases are made by women buying independently, often through trusts or after a divorce or inheritance.

Those purchase paths share a common need: an independent value nobody can argue with. Trust purchases, divorce settlements, and estate distributions all put the number under scrutiny from trustees, attorneys, or courts. The appraisal is what keeps that scrutiny short.

The Wealth Transfer Is an Appraisal Event

Here is what the trend coverage misses. Every luxury property that passes between generations needs a documented value at the moment it moves. Estates need date-of-death values to set basis and settle fairly among heirs. Gifted property needs a supportable value for the paperwork the family’s CPA will file. Homes placed in trusts need values for funding and accounting. The tax mechanics belong to a CPA, but the value itself is appraisal work, and it has to hold up years later if anyone asks.

Families who handle this well get the appraisal at the time of transfer, not five years later when a dispute or an audit forces a retrospective reconstruction. With this much property set to change hands, the cheapest insurance in estate planning is a current, well-documented value from a qualified appraiser. Our estate planning appraisal work exists for exactly this moment.

Get the Value Documented Before the Asset Moves

If you own, advise on, or expect to inherit high-end property, the order of operations matters. Appraise before the transfer, before the listing, and before the settlement talks, while the facts are fresh and the market data is current. The new luxury market rewards buyers and families who know their number. It punishes the ones who guess.

Put a Defensible Number on a High-Value Property

PahRoo’s MAI and SRA designated appraisers value luxury and estate homes for purchases, trusts, estates, and settlements across Chicago, Dallas, Philadelphia, Phoenix, and Naples.

Request a Luxury Home Appraisal

Frequently Asked Questions

Why is a luxury home harder to appraise than a typical house?

Because comparable sales are scarce and the properties are one of a kind. The appraiser must widen the search, verify each sale’s terms, and support adjustments for custom features, which takes more skill and more market evidence than a standard assignment.

Can I rely on an online estimate for a high-end property?

No. Automated models depend on many similar recent sales, which luxury markets rarely provide. Estimates at the top of the market routinely miss by wide margins, in either direction, and carry no weight with courts, trustees, or the IRS.

Do smart home and wellness features increase appraised value?

Sometimes. The appraiser measures contributory value, meaning what buyers in that submarket actually pay for the feature, which is often less than installation cost. Well-documented, market-supported features fare best.

When does inherited or gifted property need an appraisal?

At the time of transfer. Estates typically need a value as of the date of death, and gifts need a supportable value for the related filings. Getting the appraisal when the property moves avoids a costlier retrospective reconstruction later. The tax treatment itself is a matter for your CPA.

How long does a luxury home appraisal take?

Longer than a standard assignment. The inspection alone can take several hours for a large custom home, and the research and reporting often run one to two weeks depending on how thin the comparable data is. Complex properties reward starting early.

Need an Independent Appraisal?

PahRoo Appraisal & Consultancy values luxury, estate, and unique residential properties across Chicago, Dallas, Philadelphia, Phoenix, and Naples. Led by Michael Hobbs, our MAI and SRA designated team delivers appraisals built to satisfy trustees, attorneys, and courts, not just curiosity.


Commercial Real Estate Appraisal in a Shifting Market

A commercial real estate appraisal answers one question: what was this property worth on a specific date? In a stable market, that answer holds for a while. In a shifting one, it can age fast. After several years of higher interest rates, repriced office space, and uneven sales activity, owners, lenders, and attorneys in 2026 need to understand what market movement does to a value opinion, and when a fresh one is worth ordering.

By the end of this article, you’ll know:

  • Why cap rate movement changes commercial values even when the building has not changed
  • How appraisers support value when few comparable sales exist
  • When an existing appraisal is stale, and what to check before you rely on any report

What a Shifting Market Does to a Commercial Real Estate Appraisal

Every commercial real estate appraisal carries an effective date. The value is a snapshot as of that date, built from the sales, leases, and financing conditions that existed then. Markets do not stand still, so the snapshot has a shelf life.

That shelf life shrinks when conditions move quickly. A report from eighteen months ago may reflect cap rates, rents, and vacancy assumptions that no longer describe the market. The building is the same. The value is not. This is why commercial appraisal work in a shifting market puts extra weight on the market analysis section of the report, not just the concluded number.

Cap Rates Follow Interest Rates, and Values Follow Cap Rates

For income-producing property, the math is unforgiving. Value is driven by net operating income and the capitalization rate a buyer requires. When interest rates rise, investors demand higher returns, cap rates drift up, and the same income stream buys a lower price. A single point of cap rate movement can shift value by double-digit percentages.

The reverse holds too. When rates ease, values recover before the sales data fully shows it. So a competent appraiser does more than average last year’s transactions. The appraiser reads current investor surveys, tracks financing terms, and interviews market participants to support where cap rates sit today, on the effective date, not where they sat when the last comparable closed.

Thin Sales Data: Finding Value When Few Buildings Trade

Shifting markets often go quiet. Sellers hold out for yesterday’s prices, buyers underwrite tomorrow’s risks, and transaction volume drops. The result is a thin set of comparable sales, some of which closed under conditions that no longer apply.

This is where methodology matters. The appraiser leans harder on the income approach, verifies the story behind each comparable (was it a distressed sale, an estate sale, a seller carryback?), and makes documented market-conditions adjustments rather than pretending an old sale is a current one. A report that simply grids three stale sales and calls it a day will not survive scrutiny from a lender’s review appraiser, a board of review, or opposing counsel. Standards under USPAP require the analysis to fit the market as it exists, and thin-market assignments are where that requirement earns its keep.

When to Order a New Appraisal, and When the Old One Has Expired

No regulation stamps a universal expiration date on an appraisal, but lenders and courts treat them as perishable. Federal banking regulators direct institutions to assess whether market conditions have changed enough that an existing appraisal no longer supports the decision, per the Interagency Appraisal and Evaluation Guidelines. In a fast-moving market, that threshold arrives sooner.

In practice, order a fresh commercial appraisal when you face a refinance or loan maturity, a purchase or disposition decision, a property tax appeal, a partnership buyout, or litigation where value is contested. Order one as well when the report in your file predates a clear turn in your submarket. Paying for a current opinion is cheaper than defending a stale one.

Reading the Report in a Moving Market

Before you rely on any commercial appraisal, check four things. First, the effective date: is the value as of a date that still describes your market? Second, the market analysis: does it discuss current vacancy, absorption, and rate conditions, or does it recite boilerplate? Third, the comparables: how old are they, and did the appraiser adjust for market movement between their sale dates and the effective date? Fourth, the assumptions: extraordinary assumptions and hypothetical conditions are legitimate tools, but you should know they are there.

A strong report shows its reasoning. If the value moved from the last appraisal, the report should tell you why. That transparency is what makes the number usable in a loan file, a settlement, or a hearing room.

Treat the Appraisal as a Snapshot, Then Act on It

A shifting market punishes decisions built on old numbers. Confirm the effective date matters for your purpose, retire reports that predate the turn, and put current, well-supported value evidence behind every refinance, appeal, or sale. The owners who fare best in these cycles are not the ones who guess the market. They are the ones who measure it, on the right date, with an appraiser who can defend the work.

Get a Current, Defensible Commercial Value

PahRoo delivers MAI-level commercial appraisals built on today’s market evidence, not last year’s, across Chicago, Dallas, Philadelphia, Phoenix, and Naples.

Request a Commercial Appraisal Quote

Frequently Asked Questions

How long is a commercial appraisal good for?

There is no universal expiration date. Lenders commonly question reports older than six to twelve months, and sooner in a fast-moving market. The real test is whether market conditions have changed enough that the report no longer describes current value.

Why did my property’s appraised value change when nothing about the building changed?

Because value reflects the market, not just the building. If cap rates rise, rents soften, or vacancy climbs in your submarket, the same property supports a different value. The appraisal measures what buyers would pay on the effective date.

What if there are almost no recent comparable sales?

The appraiser shifts weight to the income approach, verifies the conditions behind each available sale, and makes documented adjustments for market movement. Thin data raises the skill requirement. It does not make a credible appraisal impossible.

Can I use last year’s appraisal for a refinance or tax appeal?

Often not. Lenders follow regulatory guidance on stale appraisals, and tax appeal boards want value as of the statutory assessment date. In both cases, an appraisal tied to the wrong date or an outdated market is easy to challenge.

Do rising interest rates always lower commercial property values?

Not always, but they apply pressure. Higher rates push investor return requirements up, which tends to push values down. Strong rent growth or scarce supply in a submarket can offset some of that pressure. The appraisal weighs both forces.

Need an Independent Appraisal?

PahRoo Appraisal & Consultancy provides independent commercial and residential appraisals for lending, tax appeal, and litigation across our five markets, including Chicago. Our MAI and SRA designated team builds every report to hold up in front of reviewers, boards, and courts.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712