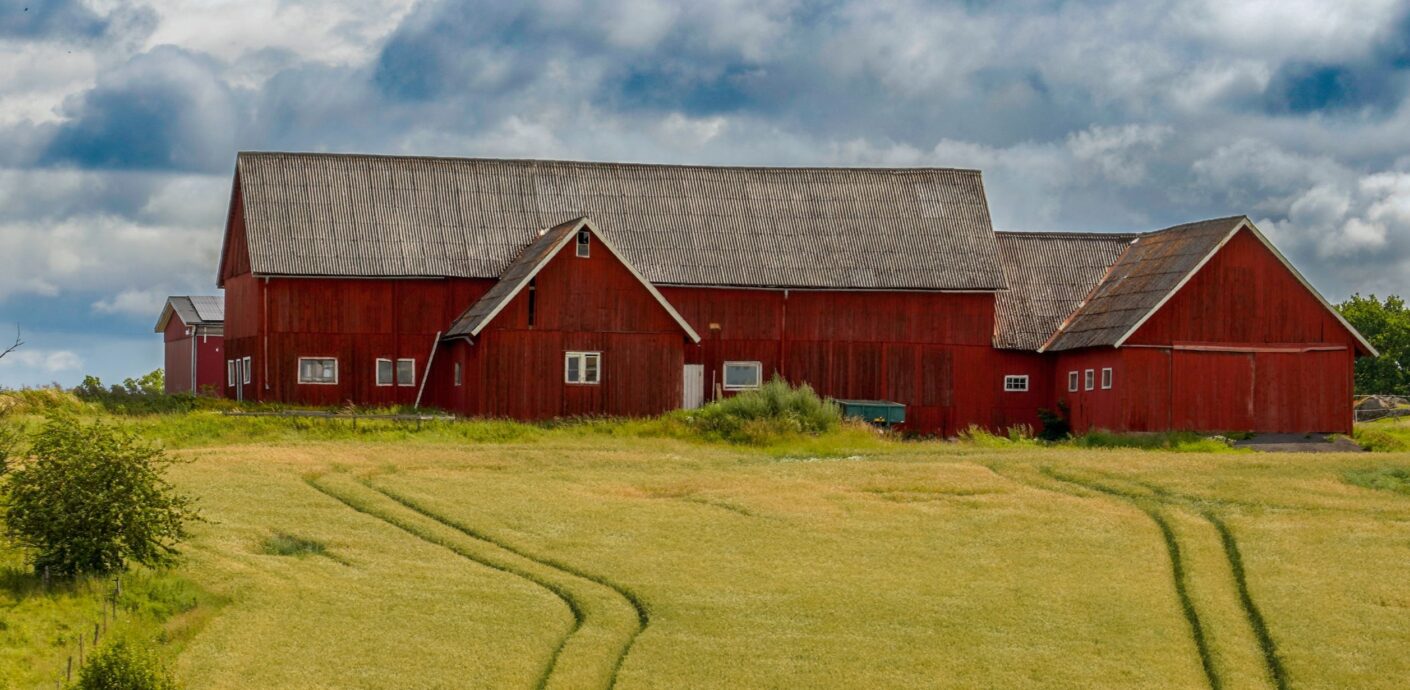
Most talk about rural vs urban appraisals stops at the obvious point: the country has fewer sales. The harder part shows up on a house with ten acres, a pole barn and a horse shelter. That property raises questions a city condo never does. Which buildings count? How far can the appraiser reach for comps? And will a lender treat it as a home at all?
By the end of this article, you’ll know:
- What Fannie Mae actually allows when rural comps are distant or old
- How the outbuildings on a property can turn a value question into an eligibility question
- What lenders and estate attorneys should check in a report on a home with acreage
Where Rural vs Urban Appraisals Actually Split
In a dense market the comps are close, recent and alike. Same block, same building type, sold this year. The analysis is mostly about small differences.
A home on acreage breaks that pattern. Fannie Mae’s Selling Guide says it plainly. Rural properties often have large lots, and rural locations can be relatively undeveloped. So there may be a shortage of recent, truly comparable sales nearby.
So the guide allows the appraiser to reach. If the best indicators of value sit a considerable distance away, those sales can be used when they produce credible results. The report has to explain why they were chosen. Every distance also gets stated in miles with a direction, measured in a straight line.
That explanation is the whole game. On a city appraisal, the comps mostly speak for themselves. On an acreage appraisal, the reasoning carries the value.
Older Sales, Farther Sales, and the Explanation That Comes With Them
The general rule is comparable sales closed within the last 12 months. But the guide carves out rural markets directly. Where sales activity is minimal, the appraiser may not find three truly comparable sales from the last year. Then older sales are acceptable, if the report explains why they were used.
Two other limits still hold. There must be at least three closed comparables. Sales from a competing market area are fine. But the appraiser cannot stretch the neighborhood boundary just to swallow the comps. The report has to say the sales come from a competing area and explain how that area compares.
When nothing truly comparable exists, the guide still allows the best available sales if the analysis is documented. What it does not allow is silence. An acreage report with distant or dated comps and no commentary draws a reviewer’s questions.
The Barn Question
This is where acreage appraisals differ most from anything in a city. Fannie Mae’s outbuildings guidance sorts them into three groups, and each one reads differently.
Minimal outbuildings, such as small barns or stables of relatively insignificant value, are acceptable. The comparable sales just have to show they are typical for residential properties in the area. An atypical minimal outbuilding is acceptable too, as long as the analysis gives it little or no contributory value.
Then there are significant outbuildings: silos, large barns, storage areas, facilities for farm-type animals. Here the guide changes the question. Their presence may indicate the property is agricultural in nature. Then the lender must determine whether it is residential, whether or not the appraiser assigns the buildings any value.
That last clause matters. A report that gives a large barn zero value has not settled the eligibility question. It has only settled the value question.
What a Lender Should Read Before the File Moves
If you are underwriting a home on acreage, four checks save a round of conditions later.
First, find the outbuildings in both places they belong. The guide expects them described in the Improvements section and in the Sales Comparison Approach section. Not in one and missing from the other.
Second, decide which of the three groups each building falls into. A pole barn for a riding mower and a machine shed for a working operation are different conversations. That holds even at the same square footage.
Third, read the comp commentary before the adjustment grid. Distance, age and competing-area sales all need an explanation. That explanation is where a weak report shows itself.
Finally, keep clarification and pressure separate. Asking the appraiser to describe an outbuilding more fully is fair. Asking for a different number is not, and a good appraiser will decline.
Estates With Acreage Run Into the Same Problems
Estate work adds a date to all of this. The IRS values a gross estate at fair market value as of the date of death. Not at what the decedent paid, and not at what the property was worth when acquired.
For a family property with land and outbuildings, that usually means a retrospective assignment in a thin market. The comp search reaches back to the date of death, not forward from today. It may also reach farther across the map than anyone expected.
The outbuildings need the same care they get in lending. What a barn cost to build and what it adds to market value are different numbers. Heirs often assume the first one. When siblings split a property or one buys out the others, that gap turns into the argument.
Tell the Appraiser About the Outbuildings Up Front
Most of the delays on acreage assignments start at the order. Tell the appraiser the acreage. List every outbuilding and what it is used for. Say whether anything on the property supports a business or animals. Mention whether the house runs on a well and septic, too.
None of that changes the value by itself. It changes the scope of the comp search and the outbuilding analysis. It also lets the appraiser flag an eligibility question before the report goes out, rather than after an underwriter finds it.
Appraising a Home With Land and Outbuildings?
Tell us the acreage, what sits on it, and who will read the report. We will scope the comp search and the outbuilding analysis before anyone sets foot on the property.
Start the Order
Frequently Asked Questions
How far can an appraiser go for comps on a rural property?
Fannie Mae sets no fixed mileage. If the best indicators of value are a considerable distance away, they can be used when they produce credible results. The report must explain why they were chosen and state each distance in miles with a direction.
Can a rural appraisal use sales older than 12 months?
Yes, when the market has minimal sales activity. Fannie Mae allows older comparable sales in rural areas as long as the appraiser explains why they are being used. At least three closed comparables are still required.
Does a barn add value to a house?
Sometimes. A barn adds what the market will pay for it, which is often far less than what it cost to build. Fannie Mae’s guidance also has the appraiser give an atypical minor outbuilding little or no contributory value.
Can a home with large outbuildings get a conventional mortgage?
It depends on the lender’s determination. Under Fannie Mae’s guidance, silos, large barns or animal facilities may indicate an agricultural property. Then the lender must decide whether it is residential in nature.
Does an estate with acreage need a different kind of appraisal?
It needs a value as of the date of death, which the IRS uses for estate property. With land and outbuildings, that usually means older and more distant comparable sales. It also means a careful look at what each building actually contributes.
Residential Appraisals Beyond the City Grid
PahRoo Appraisal & Consultancy works out of Lincolnwood, with operations in Dallas, Philadelphia, Phoenix and Naples. Michael Hobbs, MAI, SRA, signs every report. Our residential appraisal team handles homes on acreage as well as city properties, including the outbuildings that come with them. You can also read how a home appraisal runs from order to delivery.