Tag: investment real estate

Request a quote

Our blog

Latest news
& events

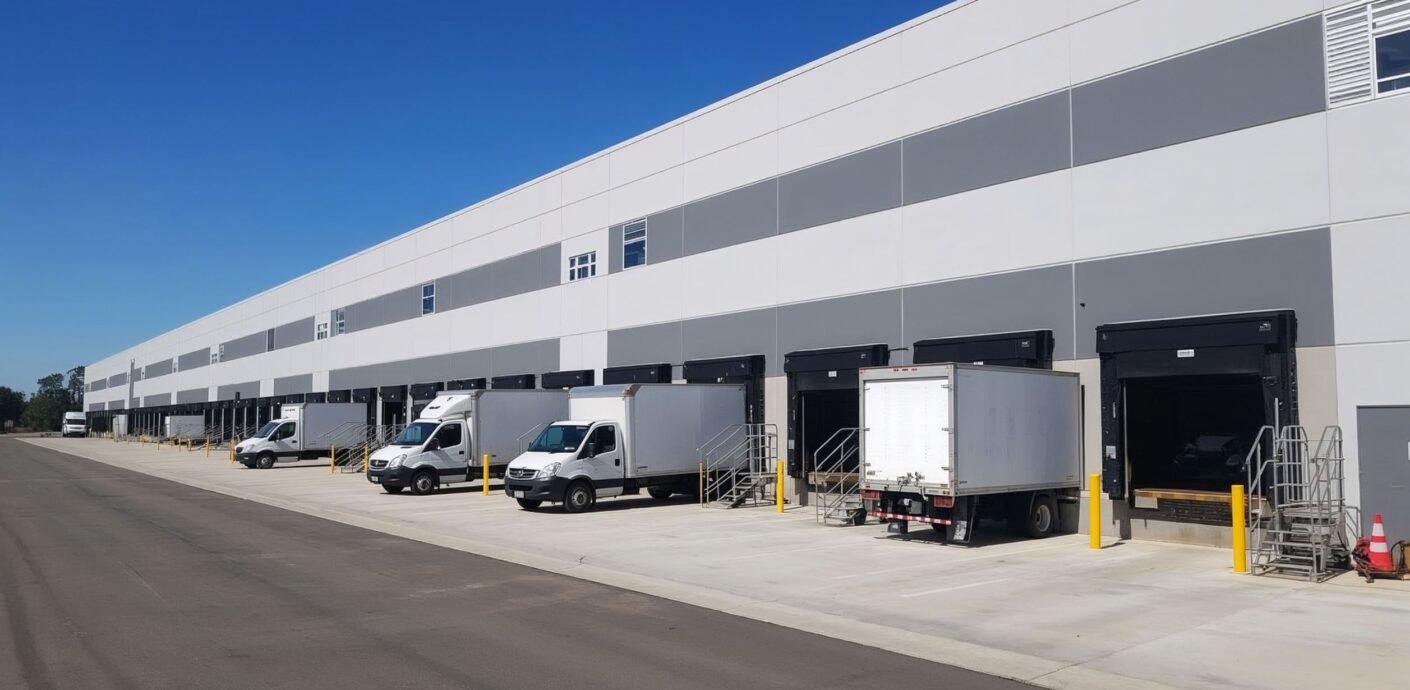
Modern distribution center with loading docks, subject of an industrial property appraisal
What Your Warehouse’s Walls Are Really Hiding

An industrial property appraisal comes down to a simple question. How fast can product move through this building, and how much space does it hold while doing it? Curb appeal barely matters here. A plain concrete box with the right clear height and enough dock doors can out-value a prettier building down the street. Instead, the reason sits in the numbers behind the walls.

By the end of this article, you’ll know:

  • The five factors that carry the most weight in an industrial valuation.
  • Why clear height and dock ratios move value more than square footage alone.
  • What is fueling warehouse and logistics demand right now, and what it means for your number.

What an Industrial Property Appraisal Weighs Most

Five factors do most of the work in an industrial valuation.

  • Location inside the logistics network. Proximity to highways, intermodal rail, and the labor pool that staffs the building.
  • Clear height and functional layout. How much usable cubic space the building offers, not just its footprint.
  • Loading and circulation. Dock door count, trailer parking, and truck court depth relative to building size.
  • Tenant credit and lease structure. Who is paying rent, on what terms, and for how long.
  • Building age and systems. Power capacity, sprinkler class, and the capital needed to bring the space current.

Most industrial buildings, in practice, get valued through a blend of two approaches. Leased distribution centers and multi-tenant parks lean on the income approach. A buyer there is purchasing the rent stream, not just the shell. Owner-user buildings lean harder on the sales comparison approach instead. Appraisers weigh those sales against similar buildings in the same size and height class. The cost approach plays a supporting role too, mostly on newer or purpose-built facilities. Our commercial appraisal services also cover all three, across office, retail, and industrial property.

Income, NOI, and the Cap Rate Behind the Number

For leased industrial, the rent roll gets read closely. Contract rents get compared against market rents. Expirations then get mapped across the holding period, and the reimbursement structure gets checked line by line. Industrial leases run triple net far more often than office leases do. The tenant typically covers taxes, insurance, and most maintenance instead of the landlord. So that keeps the landlord’s expense load lighter, and the income more predictable. That predictability is part of why industrial has held cap rates tighter than office through the same rate cycle. We walked through how that income figure gets built in our guide to net operating income in commercial real estate. The same mechanics apply here. Tenant concentration still matters too. A single-tenant distribution building lives or dies with one renewal decision. So appraisers weigh that risk against the size of the rent check.

Clear Height, Docks, and the Physical Specs That Move Value

Clear height matters more than almost any other industrial spec. It is the unobstructed vertical space from the floor to the lowest hanging obstruction. That obstruction could be a joist, a light, or a sprinkler head. Still, older buildings across the Chicago market commonly top out around 24 to 28 feet. Modern Class A distribution space runs 32 to 36 feet instead. Large e-commerce fulfillment buildings increasingly push past 40 feet to support automated storage systems. That gap is not cosmetic. Moving from a 30-foot to a 36-foot clear height can add 10 to 25 percent of usable storage capacity. It does that without adding a single square foot to the building’s footprint. So appraisers price that extra cubic space directly into value.

Dock doors, trailer parking ratio, and column spacing round out the physical picture. A building with too few docks for its size creates a bottleneck. That bottleneck shows up as functional obsolescence in the appraisal. It happens even when the square footage checks every box on paper. Brokers advising an owner ahead of a listing can get ahead of this instead of explaining it after the fact. Pull the actual clear height and dock count before setting an asking price. Then anchor the comp set to buildings in the same height class, not the metro average. An appraisal that lands under the listing price on an older building usually traces back to a spec gap, not a market swing. So flagging it early keeps the deal from stalling at the lender’s desk.

Why Logistics and E-commerce Demand Is Driving Industrial Value

Industrial has been a standout sector for years. The current data backs that up. According to CBRE’s Chicago Industrial Figures for the second quarter of 2026, the metro’s industrial availability rate fell to 8.6 percent. That is down 30 basis points from the prior quarter. Net average asking rents climbed to $9.30 per square foot, up 7.4 percent year over year. Net absorption jumped to 6.1 million square feet in the quarter. That is well ahead of the 1.1 million square feet absorbed in the first quarter. Another 11.8 million square feet remained under construction, split evenly between speculative and build-to-suit projects.

Nationally, CBRE’s second-quarter research reported the first decline in industrial vacancy since 2022. Demand broadened beyond third-party logistics providers too, as manufacturers picked up a larger share of leasing activity. E-commerce fulfillment, manufacturing reshoring, and tighter big-box supply are feeding the same story from different directions. For an appraisal, that shows up as stronger market rent growth assumptions. In many submarkets, cap rates have also held firmer than other property types through the same financing environment.

The Number Should Match the Building, Not the Market Average

A market average is only a backdrop. Still, it does not appraise your specific building. Two distribution centers half a mile apart can carry very different values. Clear height, dock ratio, and lease structure decide that, not the address. Before a sale, refinance, or partnership buyout, get a number built from the building’s actual specs and tenants instead. After all, a market headline is not a substitute.

Ready to Put a Real Number on Your Industrial Building?

PahRoo appraises warehouses, distribution centers, and manufacturing buildings across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples.

Request a Commercial Appraisal Quote

Frequently Asked Questions

How is industrial property appraised?

Most industrial buildings are valued through a blend of the income approach and the sales comparison approach. Leased distribution centers rely mainly on income, built from the rent roll, market rents, and expenses. Owner-user buildings lean more on comparable sales of similar buildings in the same size and clear height class. The cost approach plays a supporting role, particularly on newer or purpose-built facilities.

What is clear height in a warehouse?

Clear height is the unobstructed vertical space from the floor to the lowest hanging obstruction. Common examples are a joist, a light, or a sprinkler head. Older industrial buildings often run 24 to 28 feet. Modern Class A distribution space commonly runs 32 to 36 feet, and large e-commerce fulfillment buildings increasingly reach 40 feet or more to support automated storage systems.

Why is industrial real estate in such high demand?

E-commerce fulfillment, reshoring of manufacturing, and a slowdown in new construction have kept demand ahead of supply in most markets. CBRE’s second-quarter 2026 research recorded the first national decline in industrial vacancy since 2022. Manufacturers also took a growing share of leasing activity alongside traditional logistics tenants.

What is a distribution center worth?

There is no single number that applies across a market. Value depends on the building’s clear height, dock doors, and trailer parking ratio. It also depends on tenant credit, lease term, and location relative to highways and rail. Two similar-sized buildings in the same submarket can carry very different values once those specs are compared.

How does location affect an industrial appraisal?

Proximity to highway interchanges, intermodal rail, and the local labor pool drives both achievable rent and buyer demand. Submarkets along major logistics corridors typically see tighter vacancy and stronger rent growth than the metro average. Appraisers weigh that submarket-level data rather than a single citywide figure.

Built From the Building, Not the Headlines

PahRoo Appraisal & Consultancy appraises commercial property across five markets. That also includes industrial, office, and retail, for owners, investors, brokers, and lenders. For a similar look at income mechanics in another property type, see our office building breakdown of what drives the value of an office building. Or start with our Chicago appraisal services page for scope and timing questions.
What Drives the Value of an Office Building

An office building appraisal comes down to one question: how reliably will this building produce income, and for how long? Everything the appraiser examines feeds that answer. So when owners ask why two similar-looking buildings carry very different values, the explanation almost always sits in the leases, the tenants, and the submarket rather than the architecture.

By the end of this article, you’ll know:

  • The five factors that carry the most weight in office value
  • How leases, rollover, and tenant credit shape the income analysis
  • Why Class A buildings and older stock are moving in opposite directions

What an Office Building Appraisal Weighs Most

Five factors do most of the work in an office valuation:

  • Occupancy and lease terms: how much space is leased, at what rents, and for how long
  • Tenant credit: the financial strength behind each signature on the rent roll
  • Location and submarket: the vacancy, rent, and demand picture on that block, not the metro average
  • Building class and condition: where the property sits in the flight to quality
  • Market cap rates: what buyers currently pay for a dollar of office income

Office buildings are valued mainly through the income approach, because buyers purchase them for their income streams. The appraiser tests each factor above and translates it into the numbers behind the value.

Income Is the Engine: Leases, Rollover, and NOI

The rent roll gets read line by line. Contract rents are compared against market rents. Expirations are mapped across the holding period, because a building with 40 percent of its leases rolling in two years carries more risk than one with staggered ten-year terms. Rent steps, expense reimbursements, tenant improvement obligations, and leasing commissions all shape the projection.

Those inputs flow into net operating income, and we covered how that number gets built in our guide to net operating income in commercial real estate. For office specifically, the vacancy assumption does heavy lifting. Actual occupancy, submarket vacancy, and realistic downtime between tenants all get weighed rather than assumed away.

Tenant Credit: The Rent Roll Behind the Rent Roll

A lease is only as good as the tenant paying it. Ten years of income from an investment-grade company is worth more than the same rent from a startup, so appraisers consider tenant quality when weighing the durability of income. Concentration matters too. A single-tenant building lives or dies with one renewal decision, while a diversified roster spreads that risk across many decisions.

This is why two buildings with identical NOI can appraise differently. The income may match today, but the probability of it continuing does not, and buyers price that difference.

Building Class, Condition, and the Flight to Quality

The office market is splitting by quality. According to the CBRE Q1 2026 U.S. office market report, overall vacancy stood at 18.6 percent while prime buildings ran at 12.7 percent, and asking rents grew at their fastest pace in six years. Tenants are concentrating in the best space and abandoning the rest.

For the appraisal, class is not a label but a set of measurable traits: systems, amenities, floor plates, energy performance, and the capital spending needed to stay competitive. An older Class B building may need substantial investment just to hold its tenancy, and that cost comes out of value. In some cases, highest and best use analysis even asks whether the building should remain an office at all.

Why Office Values Fell, and How an Appraisal Reads the Recovery

Office values dropped for two stacked reasons. Hybrid work cut demand for space, which pushed vacancy up and rents down in weaker buildings. Then higher interest rates pushed cap rates up, which cut the price of every dollar of income. National vacancy has now edged past its peak and demand has turned positive, but the recovery is uneven across markets and building classes.

That unevenness is exactly why office work demands submarket-level analysis. A metro average tells you little when one corridor is tightening and the next is emptying. Our commercial appraisal services build the value from the property’s actual leases and its actual submarket, so the conclusion reflects your building rather than the headlines.

What is your office building actually worth right now?

In a market moving this unevenly, last year’s number is stale. PahRoo appraises office property from the rent roll up, with submarket evidence a buyer or lender can verify.

Request a Commercial Appraisal Quote

Frequently Asked Questions

What drives the value of an office building?

Occupancy and lease terms, tenant credit, submarket conditions, building class and condition, and market cap rates. These determine how much income the building produces, how durable that income is, and what buyers will pay for it.

How are office buildings appraised?

Mainly through the income approach. The appraiser analyzes the rent roll, compares contract rents to market rents, applies vacancy and expense assumptions, and converts the resulting net operating income into value using market-derived rates, checked against comparable sales.

Why have office building values fallen?

Hybrid work reduced demand for space, which raised vacancy and weakened rents, while higher interest rates pushed cap rates up. Both forces cut value at once. The decline has been uneven, hitting older buildings much harder than prime space.

What is a Class A office building?

The highest-quality tier in a market: modern systems, strong locations, competitive amenities, and creditworthy tenants. Class B and C buildings are older or less competitive. Class is relative to the local market rather than a fixed national standard.

How does vacancy affect office value?

Vacant space produces no income but still incurs expenses, so vacancy reduces net operating income directly. Appraisers also weigh submarket vacancy, because it sets how long re-leasing will take and what rent the space can realistically achieve.

Office Valuation Built From the Rent Roll Up

PahRoo Appraisal & Consultancy appraises office and other commercial property across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, for owners, investors, and lenders. Start with our Chicago appraisal services page, or review our appraisal consulting FAQ for scope and timing questions.

How Scott Voltz Built an Appraisal Business That Stands the Test of Time
What does it take to stay in the appraisal industry for five decades and still love what you do?
In this powerful episode of Appraisers on Purpose, Michael Hobbs sits down with veteran appraiser and investor Scott Voltz, who shares a lifetime of lessons, including how he built a thriving appraisal business from the ashes of the 1989 banking crisis.
From Accidental Landlord to Industry Leader


Scott’s story begins with a chance real estate purchase at 22 years old, sparked by a missed turn and a for-sale sign on a weed-covered house. That experience set him on a journey that would weave through real estate syndication, investment, and ultimately, a passion-fueled appraisal practice. I was reviewing MAI reports and thought, I’m already doing this,” Scott recalls. That realization launched his decades-long career as a respected appraiser.
The Power of Geographical Specialization


One of Scott’s most game-changing decisions? Becoming the northernmost MAI in Los Angeles County. At a time when most appraisers chased work all over, Scott doubled down on local dominance. That strategy paid off, especially after the Northridge earthquake in 1994, which made him the go-to expert when others couldn’t reach the area.

I said, ‘Hi, I’m Scott Voltz and I’m going to dominate this area.’ And I did.


Scott proves that building authority in a niche market especially one underserved by competitors is a timeless success formula.

Why Appraisal Is More Than a Job
Scott sees appraisal not just as work, but as a profession rooted in trust, knowledge, and contribution. In fact, he shares that appraisers were mentioned in the Book of Leviticus, where priests were trusted to assign value to donated land.

If you treat it like a job, it’ll be a job. But if you treat it like a profession, you’ll grow and succeed.


Scott’s perspective is both refreshing and energizing, especially for younger appraisers seeking staying power in a fast-changing market.

Get inspired by one of the most grounded and hopeful episodes yet. Whether you’re early in your career or rebuilding in a shifting market, this one’s for you.

Enjoyed Scott Voltz’s story?

Don’t miss out on more inspiring journeys and practical insights from leaders in the appraisal world. Listen to the Appraisers on Purpose podcast on Spotify or subscribe to our YouTube channel to catch every new episode. Your next breakthrough might just start with a listen.


If you’re Interested in starting your own appraisal business or looking for mentorship, contact the Pahroo team to learn more about commercial and residential real estate appraisal in Chicago.
 
Housing Market 2025: What $1 Million Gets You Today

A Million Dollars Used to Buy Luxury. Now It Buys… the Basics?

Once upon a time, a $1 million home meant luxury: space, privacy, and maybe even a pool.
Today? In cities like San Francisco, Seattle, and parts of LA, $1 million might get you a dated 2-bedroom, and a bidding war.

We’re in a new era of housing where $1M no longer equals high-end. It’s entry-level. So how did we get here?

What’s Driving the Shift?

This isn’t just a coastal problem. Even secondary markets like Austin, Denver, and Phoenix are seeing seven-figure starter homes.
Here’s why:

  • Low Inventory: Decades of underbuilding have led to a serious supply crunch.

  • Rising Construction Costs: Inflation, materials, and labor shortages drive prices higher.

  • Zoning Restrictions: Local regulations make new, affordable builds nearly impossible.

  • Remote Work Migration: High-earning buyers are leaving coastal cities and driving up prices in previously “affordable” areas.

  • Fear of Missing Out: Many first-time buyers are jumping in now, afraid prices will rise further.

Where $1 Million Doesn’t Go Far

Let’s look at what $1M gets you today:

  • San Francisco: Maybe a 1-bed condo. If you’re lucky.

  • Los Angeles: A modest fixer-upper, with multiple offers.

  • Seattle: A small single-family home… with a long commute.

  • Austin: A cookie-cutter new build 45 minutes outside the city.

Even in the suburbs, buyers are finding themselves priced out or forced to compromise on size, location, or condition.

What Is a “Starter Home” Now?

Traditionally, a starter home was affordable for entry-level buyers, often smaller, modest, and budget-friendly.
Now, “starter” just means the lowest price available in the market. For many, that’s still $800K to $1.2M.

Worse yet, many first-time buyers rely on family help, jumbo loans, or co-buying with friends to compete.

Is This Sustainable?

Experts say this level of pricing pressure isn’t sustainable long-term.

While mortgage rates have cooled slightly, affordability remains near historic lows. Wages aren’t rising fast enough, and many buyers are already at their financial limits.

Still, limited supply means prices are unlikely to drop dramatically anytime soon.

Final Thoughts

In today’s market, $1M doesn’t guarantee luxury, it simply gets your foot in the door.

For aspiring homeowners, this shift is frustrating. For real estate professionals and appraisers, it’s a reminder of how location, demand, and perception continue to reshape value.

The “starter home” hasn’t disappeared, it just has a new price tag.

For insights into how zoning laws impact property values, explore our post on Zoning: The Most Boring Topic That Can Change Everything. Additionally, for official and up-to-date market data, the National Association of Realtors is a trusted resource.

Ready to navigate the evolving housing landscape? Contact us today, and our team will provide expert guidance tailored to your real estate goals.

Commercial real estate skyline reflecting interest rate risks and market uncertainty
Commercial Real Estate Risks and How Appraisals Price Them

Every commercial property is a bundle of risks with a roof on it. The return an investor demands, and therefore the price a building commands, is compensation for carrying those risks. Most lists of commercial real estate risks stop at naming them. This one goes further. In an appraisal, each risk gets translated into a number, and knowing where that happens changes how you buy, lend, and hold.

By the end of this article, you’ll know:

  • The five risk categories that actually move commercial values
  • Which risks hide in the rent roll, and which hide in the exit
  • Exactly where each risk enters an appraisal, from vacancy assumptions to cap rate selection

Commercial Real Estate Risks Show Up in the Value First

The market does not wait for a risk to materialize before charging for it. A building with a shaky tenant, a thin buyer pool, or a looming capital expense trades at a discount today. That holds whether or not the bad thing ever happens. The cap rate is the market’s risk gauge. The riskier the income stream, the higher the return buyers demand, and the lower the price for the same income.

So the useful question is not “does this property have risks?” Every property does. The question is which risks the price already reflects, and which ones the seller is hoping you will not notice.

Market and Interest Rate Risk

The broadest risks come from outside the property line. Market cycles turn, and interest rates move cap rates whether your building changes or not. We covered the mechanics in our articles on commercial appraisals in a shifting market and the post-pandemic repricing. The short version: these risks are systemic and you cannot screen them out. The defense is underwriting on current conditions rather than the ones you remember.

One practical marker deserves mention. If a deal only works at today’s rates with no cushion, it carries refinancing risk. The purchase price should reflect that. Buildings bought with no room for rates to move are the ones that change hands involuntarily later.

Tenant and Income Risk

Inside the property line, the biggest risk lives in the rent roll. Who are the tenants, how strong is their credit, and when do their leases expire? A building with one tenant and three years of term is a very different asset than one with six tenants on staggered leases. That holds even at identical current income.

Concentration is the quiet killer. When a single tenant is most of the income, the property’s value rides on that tenant’s business. Rollover is its partner: leases expiring together create a cliff where vacancy, downtime, and re-leasing costs all land at once. Sophisticated buyers price both. Sellers rarely volunteer them.

Liquidity Risk: The Exit Nobody Prices Until They Need It

Commercial property does not sell on demand. In a normal market, a well-priced asset can still take months to close. In a stressed one, the buyer pool for certain property types nearly disappears. That is liquidity risk, and it is the one investors most consistently ignore. It costs nothing until the day it costs everything.

Specialized properties carry the most of it. A generic warehouse has many possible buyers. A purpose-built facility has few, and few buyers means longer exposure, weaker negotiating position, and deeper discounts under pressure. If your hold plan assumes a quick exit, the appraisal’s exposure time analysis is telling you whether the market agrees.

Physical, Environmental, and Tax Risk

The last category is the building itself and the rules around it. Deferred maintenance and aging systems are future capital calls wearing a disguise. Buyers deduct them from price at more than repair cost. Environmental issues, from flood exposure to contamination history, can restrict financing and shrink the buyer pool overnight. And property taxes are not a fixed line item. A sale or reassessment can move the bill enough to bend the whole income analysis, which in high-tax markets is a valuation event of its own.

How an Appraisal Prices Each Risk

Here is where the taxonomy becomes practical. A credible commercial appraisal, prepared under USPAP, does not list risks in an appendix. It embeds them in the numbers. Tenant and rollover risk enter through vacancy and collection loss assumptions. In a discounted cash flow, they also appear as downtime and re-leasing costs at each expiration. Physical risk enters as deductions for deferred maintenance and reserves for replacement. Market, rate, and liquidity risk converge in the cap rate and discount rate selection. Those rates are supported by what actual buyers of comparable risk are paying.

That is why two honest appraisals of similar buildings can conclude different values. The risk profiles differ, and the analysis says so with support. It is also why a report that quotes one cap rate for every asset in a market should worry you. Our commercial appraisal work exists to make the risk pricing explicit. The number you rely on should show what you are being paid to carry.

Know Which Risks You Are Being Paid to Take

Risk in commercial real estate is not avoidable, and it is not the enemy. Unpriced risk is. Before you buy, lend against, or hold a commercial asset, get a valuation that names the risks. It should show where each one landed in the math. The investors who get hurt are rarely the ones who took risks. They are the ones who took risks for free.

See What the Risks Are Really Costing You

PahRoo’s MAI designated appraisers price tenant, market, and property risk into defensible commercial valuations across Chicago, Dallas, Philadelphia, Phoenix, and Naples.

Request a Commercial Appraisal

Frequently Asked Questions

What are the biggest risks in commercial real estate?

Five categories cover most of it: market and rate risk, tenant and income risk, liquidity risk at exit, physical and environmental risk, and tax risk. The most damaging ones are usually inside the rent roll, in tenant concentration and lease rollover.

How does risk affect a commercial property’s value?

Through the return buyers demand. Riskier income streams push cap rates higher, which lowers the price the same income supports. The market charges for risk in advance, whether or not the risk ever materializes.

What is tenant concentration risk?

It is the exposure created when one tenant supplies most of a property’s income. If that tenant fails or leaves, the building’s cash flow collapses at once. Buyers and appraisers discount heavily concentrated rent rolls relative to diversified ones.

Where do these risks appear in an appraisal?

In the assumptions and rates. Vacancy and collection loss reflect tenant risk, while deductions and reserves reflect physical condition. Downtime and re-leasing costs reflect rollover, and the cap rate or discount rate carries market, rate, and liquidity risk.

Can an appraisal help me negotiate a lower purchase price?

Yes, when it documents risks the asking price ignores. A supported analysis of rollover exposure, deferred maintenance, or thin liquidity gives a buyer specific, defensible grounds for a price adjustment. That beats a general feeling that the price is high.

Risk Priced, Not Guessed

Buying the building is optional; carrying its risks is not. PahRoo Appraisal & Consultancy values commercial and investment property across Chicago, Dallas, Philadelphia, Phoenix, and Naples. Our analysis of how market shocks reach property and where the cycle stands feeds directly into every assignment. Led by Michael Hobbs, our MAI and SRA designated team makes the risk math visible.


Small investment property of the kind where real estate investment mistakes get expensive
Real Estate Investment Mistakes an Appraiser Keeps Seeing

Most lists of real estate investment mistakes are written by people who sell properties. This one comes from the other side of the closing table. Appraisers get called in when deals are underwritten, contested, refinanced, and unwound, so we see where investors actually lose money. The pattern is consistent. Almost every expensive mistake traces back to the same root: acting on a number nobody verified.

By the end of this article, you’ll know:

  • The six valuation mistakes that cost investors the most, and how each one starts
  • Why online estimates and listing prices fail hardest on investment property
  • Which deals justify an independent appraisal even when no lender requires one

The Real Estate Investment Mistakes That Start With a Bad Number

The first and most common of the real estate investment mistakes is treating price as value. A listing price is a seller’s ambition. An online estimate is an algorithm’s guess. It is built from public records that miss condition, layout, and everything behind the front door. Neither is an opinion of market value.

Investment properties break automated models even faster than owner-occupied homes do. Rents, expenses, and condition drive the math, and none of those live in public data. An investor who underwrites a deal on an algorithm’s number is building the whole return projection on sand. Standards-based valuation exists for exactly this reason. It is why appraisers work under USPAP rather than under whatever the listing says.

Underwriting Yesterday’s Market

The second mistake is running today’s deal on last year’s assumptions. Rents soften and cap rates move. A comparable sale from eighteen months ago may describe a market that no longer exists. We covered how this plays out for income property in our article on commercial appraisals in a shifting market. The short version applies to a two-flat as much as an office tower: value has a date on it.

Before you commit, ask what the market has done since each of your comparables closed. Then ask whether your rent and expense assumptions reflect current conditions or hopeful ones. If the deal only works with yesterday’s numbers, it does not work.

Missing What Drags Value Down

Investors are good at spotting upside and bad at pricing decay. Deferred maintenance, an obsolete layout, a flood zone designation, or environmental issues next door all pull value below what the surface suggests. These are exactly the items a drive-by look and a listing photo tour will miss.

So do the unglamorous work. Get the inspection, pull the flood maps, and walk every unit. When a defect turns up, price it as the market would, not as a contractor’s repair quote. Buyers discount problems by more than the cost to fix them.

Confusing Renovation Cost With Value

Here is the mistake that ruins flip math. Spending $80,000 on a renovation does not add $80,000 of value. Appraisers measure contributory value, meaning what the market pays for the improvement. That figure routinely lands below cost, especially for over-improvements that push a property past its neighborhood ceiling.

We walked through this discipline for green property features, and it governs every upgrade. Think granite in a C-class rental, a luxury bath in a starter-home block, or an addition that makes the biggest house on the street bigger. Budget renovations against what comparable renovated properties actually sell for, not against what the work costs.

Skipping the Appraisal Because No Lender Made You Get One

Cash purchases, off-market deals, seller financing, and partnership buy-ins share a dangerous feature. Nobody in the transaction is required to check the value. The lender’s appraisal, whatever its limits, at least forces one independent look. Remove it and the only value opinion in the room belongs to the person selling to you.

These are precisely the deals where an independent appraisal earns its fee. It is also the cheapest dispute insurance available. Partnership stakes, buyouts, and estate transfers priced without a documented value tend to resurface in litigation years later, when reconstructing the number costs far more.

Treating Taxes and Insurance as Fixed Costs

The last mistake hides in the expense column. Property taxes are not frozen at the seller’s bill. A sale and a reassessment can move them, and in high-tax markets like Cook County that swing can erase a thin margin. Insurance has its own trap. Replacement cost and market value are different numbers, and underinsuring a building to its purchase price can leave a gap when something burns.

The fix is professional, not heroic. Have your CPA model the tax picture, and ask an insurance professional to quote replacement cost properly. If the assessment comes in high after you buy, a tax appeal supported by an appraisal is a real option, not a lost cause.

Verify the Number Before You Wire the Money

Every mistake above has the same antidote: independent verification before commitment. Underwrite on current data. Price the defects and the improvements at market rather than at cost, and put a real appraisal behind any deal where no one else will check the value. The investors who last are rarely the boldest. They are the ones whose numbers were right.

Check the Number Before You Commit

PahRoo appraises residential and commercial investment property across Chicago, Dallas, Philadelphia, Phoenix, and Naples, so your deal math starts from a value you can defend.

Request an Investment Appraisal

Frequently Asked Questions

What is the biggest mistake new real estate investors make?

Acting on an unverified number. Whether it is a listing price, an online estimate, or a seller’s rent roll, new investors routinely underwrite deals on unchecked figures. Every downstream calculation inherits that error.

Is an online estimate good enough for an investment purchase?

No. Automated estimates miss condition, interior quality, actual rents, and expenses, which are the inputs that drive investment value. They are a starting point for curiosity, not a basis for wiring money.

Do I need an appraisal if I’m paying cash?

That is when you need one most. With no lender in the deal, no one is required to verify the value. The only opinion in the room belongs to the seller. An independent appraisal is the check the transaction otherwise lacks.

Will my renovation add its full cost to the property’s value?

Usually not. Appraisers measure contributory value, meaning what buyers actually pay for the improvement, which often runs below cost. Over-improvements beyond the neighborhood’s ceiling return the least.

Can property taxes change after I buy an investment property?

Yes. Reassessment can move the bill well above what the seller paid, which matters in high-tax markets. Model the tax picture with your CPA before closing. A high assessment can also be appealed with appraisal evidence.

Need an Independent Appraisal?

PahRoo Appraisal & Consultancy values investment property across Chicago, Dallas, Philadelphia, Phoenix, and Naples, from residential two-flats to commercial buildings. Led by Michael Hobbs, our MAI and SRA designated team gives investors the number before the market gives them the lesson.


Luxury home interior representing a luxury real estate appraisal assignment
Luxury Real Estate Appraisal as the Buyer Pool Changes

Walk into a high-end open house today and the buyers look different than they did a decade ago. Younger, more often women buying on their own, and asking about smart systems instead of formal dining rooms. That shift changes more than marketing. It changes what a luxury real estate appraisal has to measure, and it is about to make documented values matter more than ever, because the largest wealth transfer in history is moving property along with the money.

By the end of this article, you’ll know:

  • Who the new luxury buyers are, and how much wealth is heading their way
  • Why high-end homes are the hardest properties to value, and where online estimates fail
  • Why the wealth transfer itself creates appraisal needs for estates, gifts, and trusts

The Buyers Are Changing, and So Is Luxury Real Estate Appraisal

For years, the top of the market belonged to Baby Boomers and Gen X. That is ending. Roughly $124 trillion in assets is projected to change hands through 2048, with about $106 trillion going to heirs, mostly Gen X, Millennials, and Gen Z, according to Cerulli Associates research summarized by Merrill and Bank of America Private Bank. Some of that inheritance arrives as cash that buys homes. A lot of it arrives as the homes themselves.

For a luxury real estate appraisal, the buyer pool is not trivia. Value is what the probable buyer would pay, so when the probable buyer changes, the analysis has to follow. An appraiser who still assumes a 1998 buyer profile will misread what today’s market rewards and what it ignores.

Why Luxury Homes Are the Hardest to Value

High-end properties break the tools that work everywhere else. Automated estimates lean on volume and similarity, and luxury homes offer neither. Sales are few, features are custom, and no two properties match. A $400,000 house might have a dozen recent comps within a mile. A $4 million house might have three loosely similar sales in a year, spread across neighborhoods.

So the appraiser has to work harder. That means widening the search area with care, verifying the terms behind each sale, adjusting for one-of-a-kind features with market support, and accounting for longer exposure times at the top of the market. This is the segment where designations and experience separate a defensible residential appraisal from an expensive guess.

What the New Buyers Pay For, and What They Do Not

Younger luxury buyers consistently favor smart-home technology, wellness spaces, energy performance, and turnkey condition. Sellers hear that and assume every upgrade returns its cost. The appraisal answers a colder question: what does the market actually pay for the feature?

Some of these amenities now carry real contributory value in the right submarkets. Others read as personal taste that the next buyer will renovate away. The discipline is the same one we described for green property features: cost is not value, and market evidence decides. In luxury, where a single feature can represent six figures, that distinction gets expensive to ignore.

Women Are a Growing Share of the Buyer Pool

The other structural shift is who holds the wealth. Women in the United States are projected to control about $34 trillion in assets by 2030, roughly 38 percent of the total, per McKinsey research. More high-end purchases are made by women buying independently, often through trusts or after a divorce or inheritance.

Those purchase paths share a common need: an independent value nobody can argue with. Trust purchases, divorce settlements, and estate distributions all put the number under scrutiny from trustees, attorneys, or courts. The appraisal is what keeps that scrutiny short.

The Wealth Transfer Is an Appraisal Event

Here is what the trend coverage misses. Every luxury property that passes between generations needs a documented value at the moment it moves. Estates need date-of-death values to set basis and settle fairly among heirs. Gifted property needs a supportable value for the paperwork the family’s CPA will file. Homes placed in trusts need values for funding and accounting. The tax mechanics belong to a CPA, but the value itself is appraisal work, and it has to hold up years later if anyone asks.

Families who handle this well get the appraisal at the time of transfer, not five years later when a dispute or an audit forces a retrospective reconstruction. With this much property set to change hands, the cheapest insurance in estate planning is a current, well-documented value from a qualified appraiser. Our estate planning appraisal work exists for exactly this moment.

Get the Value Documented Before the Asset Moves

If you own, advise on, or expect to inherit high-end property, the order of operations matters. Appraise before the transfer, before the listing, and before the settlement talks, while the facts are fresh and the market data is current. The new luxury market rewards buyers and families who know their number. It punishes the ones who guess.

Put a Defensible Number on a High-Value Property

PahRoo’s MAI and SRA designated appraisers value luxury and estate homes for purchases, trusts, estates, and settlements across Chicago, Dallas, Philadelphia, Phoenix, and Naples.

Request a Luxury Home Appraisal

Frequently Asked Questions

Why is a luxury home harder to appraise than a typical house?

Because comparable sales are scarce and the properties are one of a kind. The appraiser must widen the search, verify each sale’s terms, and support adjustments for custom features, which takes more skill and more market evidence than a standard assignment.

Can I rely on an online estimate for a high-end property?

No. Automated models depend on many similar recent sales, which luxury markets rarely provide. Estimates at the top of the market routinely miss by wide margins, in either direction, and carry no weight with courts, trustees, or the IRS.

Do smart home and wellness features increase appraised value?

Sometimes. The appraiser measures contributory value, meaning what buyers in that submarket actually pay for the feature, which is often less than installation cost. Well-documented, market-supported features fare best.

When does inherited or gifted property need an appraisal?

At the time of transfer. Estates typically need a value as of the date of death, and gifts need a supportable value for the related filings. Getting the appraisal when the property moves avoids a costlier retrospective reconstruction later. The tax treatment itself is a matter for your CPA.

How long does a luxury home appraisal take?

Longer than a standard assignment. The inspection alone can take several hours for a large custom home, and the research and reporting often run one to two weeks depending on how thin the comparable data is. Complex properties reward starting early.

Need an Independent Appraisal?

PahRoo Appraisal & Consultancy values luxury, estate, and unique residential properties across Chicago, Dallas, Philadelphia, Phoenix, and Naples. Led by Michael Hobbs, our MAI and SRA designated team delivers appraisals built to satisfy trustees, attorneys, and courts, not just curiosity.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712