Tag: Residential Appraisal

Request a quote

Our blog

Latest news
& events

Appraiser filling up an appraial report of a Chicago brick home during a home appraisal
When Do You Actually Need a Home Appraisal?

Most people think about an appraisal only when a lender orders one. So when do you need a home appraisal? More often than that, and a few of those moments carry real money, because the number ends up in a tax return, a settlement, or a closing statement.

By the end of this article, you’ll know:

  • Which life events usually call for an appraisal, and which ones don’t
  • When the lender handles it and when you order one yourself
  • What a buyer can do if the appraisal comes in low

When Do You Need a Home Appraisal for a Mortgage?

If you’re buying with a loan or refinancing, the lender orders the appraisal and you usually pay for it. The report protects the lender’s collateral. It tells them the home supports the loan amount.

That isn’t always the case anymore, though. On some loans, Fannie Mae’s underwriting system can offer value acceptance, which means no appraisal for that transaction. It’s the lender’s option, not yours. Two to four unit buildings and homes priced at $1,000,000 or more don’t qualify. If you’re curious about the trade-offs, we wrote about the risks of skipping the appraisal.

When there is an appraisal, you get to see it. Federal rules under the Equal Credit Opportunity Act require the lender to give you a copy promptly, or three business days before closing if that comes first. You can waive that timing, but think twice before you do.

Buying a Home? Read the Appraisal Before You Close

Buyers often skim the appraisal for one number and move on. Instead, read the whole thing. Check the square footage, the bedroom and bathroom count, and the condition notes. Then look at the comparable sales and ask whether they really match your block.

If the value comes in below the contract price, you have a few paths. You can ask the seller to lower the price, cover the gap in cash, or lean on an appraisal contingency if your contract has one. Your agent or attorney can tell you how many days you have and what the contract allows.

You can also challenge the number. On Fannie Mae loans, a buyer can request one reconsideration of value per appraisal, through the lender, with up to five alternative comparable sales. It has to happen before closing. So gather your sales early, and pick ones that are recent, close by, and similar in size.

Paying cash? No lender means no required appraisal. Still, a cash buyer has the most to lose from overpaying, and an online estimate won’t catch a failing roof. Our piece on Zestimates versus appraisals explains why the two numbers drift apart.

Dropping PMI Before It Ends on Its Own

If you put down less than 20 percent on a conventional loan, you’re probably paying private mortgage insurance. According to the Consumer Financial Protection Bureau, you can ask your servicer to cancel it once your balance reaches 80 percent of the home’s original value. The servicer can ask for evidence, such as an appraisal, that the value hasn’t dropped below that original figure.

PMI also ends automatically at 78 percent of original value if you’re current on payments. Your servicer, or investors like Fannie Mae and Freddie Mac, may allow earlier removal under their own guidelines. Before you pay for a report, call your servicer and ask which appraisers and report types they accept. If they’ll take an independent report, PMI removal is one of the residential assignments we handle across Chicago.

Inheriting, Settling an Estate, or Gifting a Home

This is where a lot of families get caught. When you inherit a house, IRS Publication 551 says your basis is generally its fair market value on the date of death. An alternate valuation date can apply if the estate’s representative elects it. That basis affects the tax when you sell, so a documented value matters even if you plan to sell quickly.

The appraisal in that case looks backward. It values the home as of the date of death, sometimes months or years later. Our guides on appraisals for inherited property and the date-of-death appraisal walk through how that works.

Gifts follow different basis rules, tied to what the giver paid. A donation to charity brings its own qualified appraisal requirements. Either way, your CPA should weigh in on the tax side before the deed changes hands.

Divorce, Buyouts, and Splitting a Home

When a marriage ends and one spouse keeps the house, the buyout number usually starts with an appraisal. The attorneys or the court set the valuation date, and the appraiser values the home as of that date. If both sides hire their own appraisers, the reports often differ, and the gap becomes part of the negotiation. Once you have a value, our marital home buyout calculator gives a rough sense of the payment after the mortgage and other liens.

The same logic applies when siblings split an inherited home or co-owners part ways. One person keeps the property, and everyone needs a value they can trust. We cover this in more depth in appraisals in divorce proceedings and our article on marital home buyouts.

Appealing a Property Tax Assessment

If your assessment notice looks high, you can appeal. In Cook County, the Board of Review hears appeals from owners who believe their property is over-valued. An appraisal is one of the stronger pieces of evidence you can bring, especially when your home differs from what the assessor’s model assumed. Our Cook County Board of Review guide covers timing and what the Board looks at.

Selling Without Guessing

Nobody requires a seller to get an appraisal. But a pre-listing appraisal can keep you from pricing too high and sitting, or too low and leaving money behind. It also gives you a head start if the buyer’s appraisal comes in short. Here’s how appraisers help sellers price a home.

Start With Why You Need the Number

The reason drives everything else. A lender’s appraisal answers the lender’s question, at the date of inspection. An estate, a divorce, or a tax appeal usually needs a different date and a report written for that purpose. So before you order anything, know who will read the report and what date the value has to match. Then ask the appraiser to build the assignment around that.

Not Sure Which Appraisal Fits Your Situation?

Tell us what happened, whether it’s an inheritance, a buyout, PMI, or a tax notice, and we’ll scope the right report and the right date of value.

Tell Us What You Need

Frequently Asked Questions

Do I need an appraisal if I’m paying cash for a home?

No lender means no required appraisal. Many cash buyers still order one because they carry all the risk if they overpay, and an independent appraiser looks at condition and local sales that online estimates miss.

Can I get a copy of my lender’s appraisal?

Yes. For a first mortgage on a home, federal rules require the lender to give you a copy promptly after it’s done, or three business days before closing if that comes first. You can waive the timing, but reading it early gives you time to spot errors.

What can I do if the home appraisal comes in low?

You can renegotiate the price, cover the difference, or use an appraisal contingency if your contract has one. On Fannie Mae loans, you can also request one reconsideration of value per appraisal through your lender before closing, with up to five alternative comparable sales.

Can I reuse my mortgage appraisal for an estate or divorce?

Usually not. A mortgage appraisal answers the lender’s question as of the inspection date. Estates and divorces typically need a value as of a different date, in a report written for that purpose, so a new appraisal is the safer route.

Do I need an appraisal to remove PMI?

Often, if you ask to cancel it early. The CFPB says you can request cancellation once your balance reaches 80 percent of the original value, and the servicer can ask for evidence, such as an appraisal, that the value hasn’t dropped. Check with your servicer before ordering one.

About PahRoo Appraisal & Consultancy

Whatever brought you here, an inheritance, a buyout, or a tax bill, PahRoo starts by pinning down the purpose and the date of value, then builds the report around them. We’re headquartered in Lincolnwood and also serve Dallas, Philadelphia, Phoenix, and Naples, with residential, commercial, litigation support, and property tax appeal work. See our Chicago real estate appraisal services or learn more about our team.
Homes for sale on a Chicago street during the fall 2026 housing market
Fall 2026 Housing Market Brings Buyers More Choices

Buyers heading into the fall 2026 housing market will find more homes to choose from than they did a year ago. Prices, on the other hand, are barely moving. The national numbers for mid-August describe a market that is loosening slowly rather than breaking, and Chicago is quietly running against the grain.

By the end of this article, you’ll know:

  • Where inventory, sales, and prices stand as of mid-August 2026
  • Why Chicago home values are still rising while the national market flattens
  • What a flat market with heavy price cutting means for your home’s appraised value

What the Fall 2026 Housing Market Numbers Show

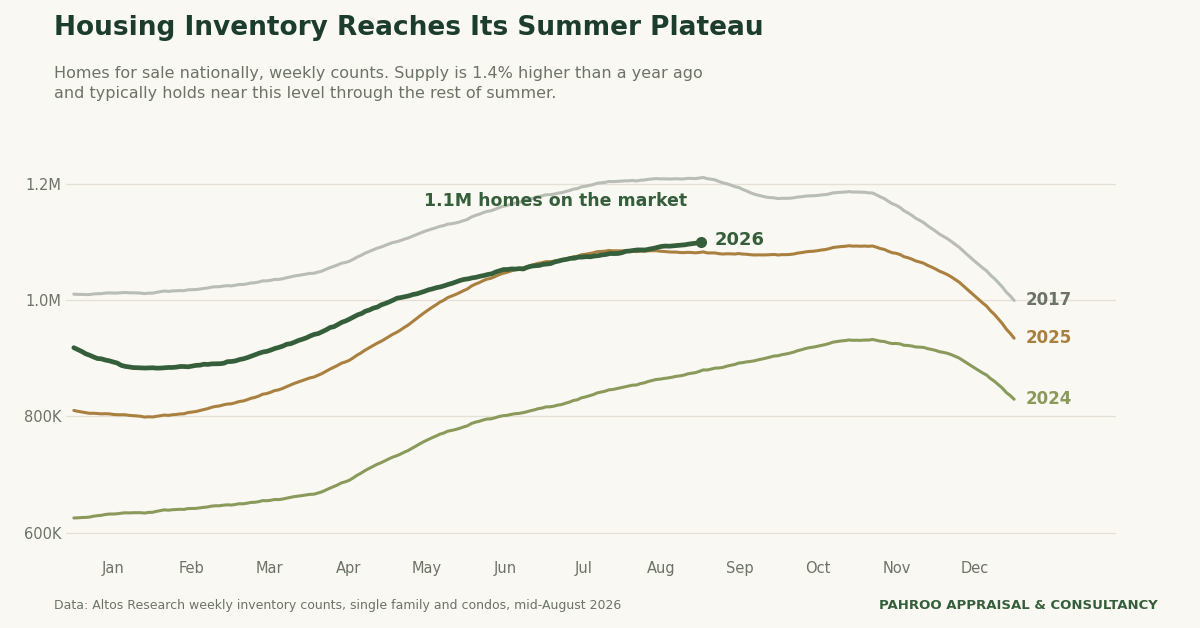
Four numbers tell the story. Mortgage rates climbed about 30 basis points in July and now sit near their highest levels of the year. Pending home sales came in around 77,000 new contracts in a recent week. That is down 3.9 percent from a year ago. Total inventory sits just above 1.1 million homes, about 1.4 percent higher than last year. The national median price for single family homes is holding near $399,000, essentially flat year over year.

Fall 2026 housing market inventory at 1.1 million homes compared to 2025, 2024, and 2017

The weekly tracking comes from Altos Research, which counts every active listing in the country. The longer arc shows up in the Federal Reserve’s national active listing data as well: supply has been rebuilding for several years, but it is still climbing gradually, not flooding the market.

Compare this to September 2023, when rates jumped 70 basis points in a single month and demand fell hard. Rates have moved a similar amount this time, but over five months. So the squeeze is real, just slower and easier to miss.

Why Chicago Is Running Against the National Grain

National averages hide a lot. Markets with plenty of supply, including Las Vegas and Seattle, are seeing slightly negative price movement. Recovering metros such as San Francisco and Miami have flipped back to appreciation. Tight supply markets, and Chicago is the clearest example, are still posting gains.

Chicago never overbuilt during the pandemic run, and listing activity here has stayed thin relative to demand. When few homes come to market, even modest buyer interest keeps prices firm. That is why a homeowner in Portage Park or Evanston can still see values inching up while the national headline reads flat.

In practice, this split means national coverage tells you very little about your own block. A Chicago real estate appraisal works from local sales, local supply, and the specific condition of your property, which is where the real answer lives.

Price Reductions Are the Early Warning System

One national figure deserves special attention: 41.7 percent of homes on the market have taken a cut from their original list price. At the current pace, that share will pass last year’s level sometime in September.

Price reductions matter because they lead sale prices by roughly three to six months. Sellers adjust their asking price before closed sales show any weakness. So a rising reduction rate in August hints at softer closing prices heading into winter, even while the median holds steady today.

Still, a price cut is not a crash signal. Reduction rates ran at similar levels last fall, and national prices finished the year flat rather than down. The takeaway is direction, not disaster: sellers have less pricing power than the headline median suggests.

What a Flat Market Means for Your Home’s Appraised Value

A flat market is deceptively tricky for valuation. When prices rise or fall steadily, recent sales point clearly in one direction. When the market goes sideways with four in ten listings cutting price, the spread between asking prices and closed prices widens. Two similar homes on the same street can sell months apart at noticeably different numbers.

This is where automated estimates struggle. Algorithms lean heavily on list prices and older sales, and both are unreliable guides right now. An appraiser instead works from verified closed sales, adjusts for condition and timing, and weighs how long comparable homes actually sat before selling.

For homeowners, the flat national picture cuts both ways. If you are selling, pricing to the market on day one matters more than usual, because chasing the market down with reductions costs both time and money. The stakes rise further in an estate, a divorce, or a tax appeal. In those settings, a defensible number matters most exactly when public data sends mixed signals. Our residential appraisal services exist for exactly these moments.

Waiting for Lower Rates Carries Its Own Cost

Plenty of buyers are sitting out this fall, waiting for rates to drop. That is understandable, but the trade is rarely free. When rates fall, sidelined demand tends to return quickly, and competition comes back with it. More inventory and less competition almost never arrive at the same time.

Buyers shopping this fall face higher borrowing costs but more choices, more negotiating room, and sellers who have already trimmed their expectations. Buyers who wait may get a cheaper loan on a more expensive, more contested house. Neither path is wrong. But each one has a price tag, and it helps to see both clearly.

How to Read Your Own Market This Fall

Ignore the national median and watch three local signals instead. First, how many homes like yours are actually for sale within a mile or two. Second, what share of those listings have cut their price. Third, how long recent sales sat on the market before going under contract. Those three numbers reveal whether your neighborhood behaves like flat national America or like tight supply Chicago. Then, if a real decision rides on the answer, skip the algorithm. Get a professional opinion of value instead.

Your Block Is Not the National Average

Flat headlines, rising Chicago values, and four in ten listings cutting price. An independent appraisal cuts through the noise with a number built from your street, not the country’s.

Get a Local Value

Frequently Asked Questions

Is fall 2026 a buyer’s market?

Not fully, but it leans that way in many metros. Inventory is above 1.1 million homes and 41.7 percent of listings have cut their price, so buyers have more choices and more room to negotiate. Tight supply markets like Chicago remain closer to balanced.

Why are home prices flat when inventory is rising?

Inventory is rising slowly, about 1.4 percent year over year, while demand has cooled by a similar amount. Supply and demand are weakening together, so the national median price near $399,000 has stayed essentially unchanged from last year.

Are Chicago home prices still going up in 2026?

Yes. Chicago remains a tight supply market, and homes here are still posting modest gains even as the national median stays flat. Local supply, not the national headline, is what drives values on your block.

What does a 41.7 percent price reduction rate mean?

It means 41.7 percent of active listings have lowered their price from the original asking number. Price reductions lead closed sale prices by roughly three to six months, so a rising rate suggests softer prices ahead, though not necessarily declines.

Should I wait for mortgage rates to drop before buying?

Waiting can backfire. When rates fall, sidelined buyers return and competition rises with them. Today’s market offers more inventory and more negotiating room, so the choice is between a cheaper loan later or a better selection now.

Get a Number You Can Act On

Founded in Chicago and led by designated MAI and SRA appraisers, PahRoo Appraisal & Consultancy values residential and commercial property across Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Whether you need a market value opinion before listing, an estate or divorce appraisal, or support for a tax appeal, our real estate appraisal services deliver independent, defensible answers you can build a decision on.

Renovated Chicago home kitchen listed for sale with unpermitted work
How to Sell a House With Unpermitted Work in Chicago

I was appraising a home in Bucktown last month. Beautiful renovation: open kitchen, custom cabinetry, new bathrooms, updated electrical. None of it had ever been permitted. So can you sell a house with unpermitted work? Yes, but not at the price her broker had assumed, and not to every buyer.

When unpermitted work surfaces during an appraisal, four things happen at once. The appraiser must disclose it. The lender’s underwriting shifts. The buyer pool narrows. And the seller lands in a conversation nobody planned for. Here is how each plays out, and what to do before the appraisal is ordered.

By the end of this article, you’ll know:

  • How appraisers and lenders are required to treat unpermitted renovations
  • How Chicago’s retroactive permit process works, and what it costs in time
  • Three pricing strategies for listing a home with unpermitted work

What Happens When You Sell a House With Unpermitted Work

The appraiser cannot look away. Under USPAP and the Fannie Mae Selling Guide B4-1.3-05, an appraiser who identifies unpermitted additions or improvements must comment on the quality and appearance of the work. Then they must assess its effect, if any, on market value.

That analysis turns on three questions. Was the work done in a workmanlike manner, with sound structure and materials that match the neighborhood? Would a typical buyer in this market accept it, or treat it as a negotiating problem? And if the work had to be permitted retroactively or removed, what would that cost?

Unpermitted work is not automatically excluded from value. A skilled renovation, typical of the market, may contribute close to its full worth. A poorly executed one may contribute very little. But either way, it gets analyzed and disclosed. Our residential appraisers see this in Chicago constantly, and the sellers who fare best are the ones who knew before the report landed.

How Different Lenders React to Unpermitted Work

Financing programs do not treat unpermitted work the same way, and this is where the buyer pool starts shrinking.

Fannie Mae and Freddie Mac will generally finance a property with unpermitted work once the appraiser has addressed quality and market impact. The space can even count toward gross living area if it is workmanlike and typical for the market. Individual lenders may layer on stricter overlays.

FHA is tougher. The property must meet the Minimum Property Requirements in HUD Handbook 4000.1. Significant unpermitted work can push the appraisal to “subject to” status, meaning the loan cannot close until the work is permitted or corrected. VA loans follow a similar pattern under their own property requirements.

Cash buyers face no lender rules at all. They simply use the unpermitted status to negotiate the price down. So a home with substantial unpermitted work often ends up competing for cash buyers and flexible conventional borrowers, while government-insured buyers drop out entirely.

The Chicago Retroactive Permit Process

For many sellers, permitting the work after the fact is the cleanest fix. The Chicago Department of Buildings handles it in a recognizable sequence: application, plan submission, plan review, inspection, correction of any deficiencies, then permit issuance.

The plans are usually the first surprise. Electrical, plumbing, and structural work typically require professional drawings of what was already built, which means architect or engineer fees before the city sees anything. The second surprise is the inspection. The completed work must meet current code, so older wiring, unvented plumbing, and unsupported structural changes all trigger correction orders before the permit issues.

Plan for roughly two to four months on a typical residential project, longer when corrections stack up. Costs run from a few thousand dollars for simple work to far more when code fixes are required. Chicago also charges more for work started without a permit, and fines can apply on top. Worse, if the city discovers the work before the seller addresses it, a stop-work order can freeze everything mid-transaction.

Three Ways to Price a Home With Unpermitted Work

Brokers have three workable strategies, and each trades money for time in a different direction.

The first is pricing at unpermitted market value. List at what the property is worth given its actual permit status. This attracts cash and flexible conventional buyers immediately. It is the fastest path to closing and the lowest number.

The second is permitting before listing. The seller completes retroactive permitting first, then lists a fully documented property to the entire buyer pool at full market value. It usually produces the best financial outcome, if the seller can absorb the months of delay and the upfront cost.

The third is disclosing and negotiating. List near full market value with the unpermitted status clearly disclosed, then handle it through price reductions or credits during the deal. This approach is common. It also produces the most extended escrows and the most collapsed contracts, because the buyer’s lender gets a vote.

Ask About Permits Before the Listing Agreement Is Signed

The intake walkthrough is where this problem should surface, not the appraisal. Ask every seller: What has been renovated since you bought the home? Which projects had permits pulled, and do you have the final inspection approvals? Was anything done by a prior owner? Has the electrical panel been upgraded, plumbing rerouted, or rooms reconfigured?

If the answers point to unpermitted work, the broker can recommend retroactive permitting, adjust the pricing strategy, or walk away from the listing. The one option that fails is assuming the appraisal will not catch it. A pre-listing appraisal answers the value question before a lender’s appraiser answers it for you, and it gives the seller real numbers to choose a strategy with.

Listing a Home With Unpermitted Work?

A pre-listing appraisal from PahRoo tells you what the property is worth as it stands, and what permitting would change, before a buyer’s lender decides for you.

Get a Pre-Listing Appraisal

Frequently Asked Questions

Can you sell a house with unpermitted work in Chicago?

Yes. Unpermitted work does not block a sale, but it must be disclosed, the appraiser must analyze it, and some financing programs will not close until it is permitted or corrected. The practical effect is a smaller buyer pool and pricing pressure.

Does unpermitted work count in the appraised value?

Sometimes. Fannie Mae guidance lets appraisers give value to unpermitted improvements that are workmanlike and typical for the market. Poor-quality work may contribute little or nothing. The appraiser must comment on the work and its market impact either way.

Will FHA finance a home with unpermitted renovations?

Only if the property still meets FHA Minimum Property Requirements under HUD Handbook 4000.1. Significant unpermitted work often makes the appraisal “subject to” repairs or permits, which delays or blocks closing until resolved.

How long does a retroactive permit take in Chicago?

Plan for roughly two to four months on a typical residential project. The timeline covers application, professional drawings, city plan review, inspection, and any code corrections. Complex projects or required repairs extend it.

Should a seller permit the work before listing or just disclose it?

Permitting first usually brings the best price because the full buyer pool returns. Disclosing and negotiating is faster to market but tends to mean longer escrows and lender complications. A pre-listing appraisal quantifies the gap so the seller can decide with real numbers.

Know the Number Before the Buyer’s Lender Does

PahRoo Appraisal & Consultancy provides pre-listing, lending, and litigation-ready real estate appraisal services across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Our team appraises renovated and Chicago-area homes with unpermitted improvements every week. Questions about a specific property? Contact our team or call 773-388-0003.


Vintage home appraisal story about a 1901 Chicago brick house with a bedroom and no closet.
Vintage Home Appraisal: The Bedroom With No Closet

One of our residential appraisers recently stood in a Chicago bedroom built in 1901 and noticed something missing. There was no closet. On a modern checklist, that looks like a problem. In a vintage home appraisal, it tells a story about how people actually lived.

By the end of this article, you’ll know:

  • Why homes built before the 1920s often have bedrooms without closets
  • Whether a room needs a closet to count as a bedroom
  • How market support saved a three-bedroom count after a renovation removed a closet

What a Vintage Home Appraisal Sees That a Checklist Misses

Plenty of people believe a room without a closet cannot be a bedroom. It is one of the most persistent myths in residential real estate. In fact, Fannie Mae’s appraisal guidance contains no closet requirement. A bedroom needs adequate size, ceiling height, privacy, heat, and a window or door for emergency egress. The closet rule comes from habit, not from the standards appraisers follow.

Still, habit shapes markets. Buyers expect closets, agents list rooms based on them, and an appraiser who treats every house like new construction will mark a closet-free room down without a second thought. That is where experience earns its fee. Our residential appraisal work across Chicago’s older housing stock means we read a 1901 floor plan on its own terms, then test that reading against real market evidence.

Why Homes Built in 1901 Rarely Have Bedroom Closets

In 1901, families did not organize their lives around hanging rods. Most clothing lived in wardrobes and large cedar trunks, often one trunk per person, parked at the foot of the bed. Some homes went a step further and built a single oversized cedar closet for the whole household. Individual bedrooms stayed small and simple, sized for a bed and a trunk and little else.

Chicago’s early twentieth century housing boom produced tens of thousands of these homes. The Chicago History Museum documents how bungalows and workers’ cottages filled the city’s neighborhoods as the population surged. Organizations like the Chicago Bungalow Association now work to preserve these layouts as a signature of the era. So when you walk into a vintage bedroom and find no closet, you are not looking at a defect. You are looking at 1901.

The Bathroom Addition That Nearly Erased a Bedroom

Now the story. The subject property was a three-bedroom home, built in 1901, with one and a half bathrooms. In 2025, the owners added a second full bathroom. Smart move on paper, because bathrooms carry real value in older housing stock. But the new bathroom took its space from a bedroom closet, which was removed entirely.

Here is the trap. Judged purely by modern convention, the home now reads as two bedrooms plus an office. That single reclassification can shift the comparable pool, the marketing story, and the final value. A renovation meant to add value would have quietly subtracted a bedroom instead. The owners had no idea. Most owners never do, because nobody warns them that a closet can carry that much weight on a report.

How Market Support Kept the Third Bedroom on the Report

Our appraiser did not simply declare the room a bedroom and move on. Sympathy is not a valuation method. Instead, she built the case. The home’s 1901 construction date placed it firmly in Chicago’s vintage stock, where closet-free bedrooms are a documented, common layout. Comparable vintage homes in the market sell as three-bedroom houses with the same configuration, and buyers in this segment accept the trade.

That is market support: a conclusion backed by evidence of how actual buyers and sellers behave, not by personal opinion. With the era established and the comparables in hand, the report could credibly carry the home as a three-bedroom. The bedroom count survived, the new bathroom added its value, and the renovation did what the owners intended. The difference between those two outcomes was never the house. It was the appraiser’s knowledge of what 1901 means.

What Owners of Older Chicago Homes Should Do Before an Appraisal

First, learn your home’s era before you remodel it. A change that seems harmless, like absorbing a closet into a new bathroom, can alter how a room is classified. Second, keep records of what your home originally looked like, because floor plans and old listing photos help an appraiser reconstruct the vintage layout. Third, and most important, choose an appraiser who knows your housing stock. A checklist can count rooms. Only experience can explain them. If your home was built before the 1920s, ask directly how the appraiser handles vintage layouts. The answer will tell you a lot.

Own a Vintage Home? Get an Appraiser Who Can Read Its Era

A 1901 floor plan deserves more than a modern checklist. PahRoo’s appraisers know Chicago’s vintage housing stock and back every conclusion with market evidence.

Request Your Appraisal Quote

Frequently Asked Questions

Does a bedroom need a closet to count in an appraisal?

No. Fannie Mae guidelines and the International Residential Code do not require a closet. A bedroom needs adequate size, ceiling height, a heat source, privacy, and a window or door for emergency egress. The closet rule is a common myth.

Why do older homes have bedrooms without closets?

Before the 1920s, most families stored clothing in wardrobes and cedar trunks rather than built-in closets. Many vintage Chicago homes also used one large shared cedar closet instead of individual bedroom closets. The layout reflects how people lived at the time.

Can a renovation lower my home’s appraised value?

It can. A renovation that removes a feature buyers expect, such as a bedroom closet, may change how a room is classified. Before you remodel an older home, consider what the change does to room count and functional utility, not just the new feature you gain.

What does market support mean in an appraisal?

Market support means the appraiser backs a conclusion with evidence from actual sales. If comparable vintage homes with closet-free bedrooms sell as three-bedroom houses, the market treats those rooms as bedrooms. The appraiser can then classify the subject home the same way.

Should I add closets to my vintage home before an appraisal?

Not automatically. In many vintage markets, buyers accept period layouts, and forcing modern closets into small rooms can hurt function. Talk with an appraiser who knows your local vintage housing stock before spending money on changes.

Need an Independent Appraisal?

PahRoo Appraisal & Consultancy has appraised Chicago’s housing stock for decades, from 1901 workers’ cottages to new construction. Whether you need a residential appraisal, an independent valuation for divorce proceedings, or simply a straight answer about what your vintage home is worth, our team is ready. Learn more about PahRoo or contact us today.


Property condition concerns identified during home appraisal inspection
Pest Infestations and What an Appraisal Must Say

The fleas started jumping before our appraiser finished the first floor. Roaches were visible in more than one room. Pest infestations at that level stop being a line in the condition section. They become a question about whether the inspection can safely finish.

By the end of this article, you’ll know:

  • What an appraisal report has to say when the appraiser sees evidence of infestation
  • When a lender can still close as is, and when the report goes subject to
  • What the Illinois disclosure form asks sellers about pests, and what it leaves out

What Pest Infestations Do to an Appraisal

Start with what the appraiser is and is not. An appraiser is not a pest inspector. Nobody on our side diagnoses an infestation, prices a treatment, or certifies that a house is clear.

The reporting duty is narrower than that, and firmer. Fannie Mae’s Selling Guide says an inspection covers the accessible areas of a property. Appraisers carry no responsibility for hidden or unapparent conditions. But the report must reflect adverse conditions that were apparent during the visit. Detrimental conditions get reported even when they are typical for competing properties nearby (Selling Guide B4-1.3-06).

So the first question after a bad walkthrough is not what this costs the value. It is what the report now has to say, and who reads it next.

Where a Condition Note Turns Into a Loan Problem

The guide has a short section titled Infestation, Dampness, or Settlement. That is the one that actually bites. When an appraisal shows evidence of infestation, the report must comment on the effect on value and on marketability.

The lender then has two ways to clear the file. One is satisfactory evidence that someone corrected the condition. The other is a professionally prepared report, based on an inspection, saying the condition poses no threat of structural damage. The appraisal itself should go subject to repairs, or subject to an inspection by a qualified professional.

Severity sets the path. Condition ratings run C1 through C6. A C6 means defects severe enough to affect the safety, soundness, or structural integrity of the improvements. If any portion of the dwelling rates C6, the whole dwelling rates C6. That loan cannot go to Fannie Mae until the deficiencies come out at C5 or better.

Worth noticing whose example the guide reaches for: wood-boring insects. Termites eat structure. Roaches, fleas and rodents usually do not. Most of the time they land in the value and marketability comment instead. That comment is the part brokers underestimate, because it travels with the file.

What a Lender Should Ask For When the Report Flags Infestation

If you are the one clearing the condition, four things are worth checking before the file moves.

Read the condition rating before anything else. A C6 is a delivery stop, not a negotiating point. Then check whether the report came in as is or subject to. If subject to, find out which one the appraiser chose: repairs, or an inspection by a qualified professional. The two close differently.

When the file clears on an inspection report, read what the inspector actually addressed. The guide asks for a professional opinion that the condition poses no threat of structural damage. A treatment receipt and a scheduled follow-up visit are not that document, and a reviewer will notice.

Finally, read the marketability comment on its own rather than folded into the value discussion. The two can move in different directions. A house can treat clean and still sit. Asking an appraiser to clarify a comment is fine. Asking for a different number is not, and a good appraiser will decline.

What the Illinois Disclosure Form Asks, and What It Leaves Out

Illinois sellers fill out the Residential Real Property Disclosure Report at 765 ILCS 77/35. It runs 24 numbered statements. Two of them touch pests. Item 19 covers current infestations of termites or other wood boring insects. Item 20 covers a structural defect caused by a previous infestation of the same.

That is the whole list. No line for roaches. No line for rodents. No line for fleas.

The form still defines a material defect broadly. It covers a condition with a substantial adverse effect on value. It also covers one that would significantly impair the health or safety of future occupants. And it puts a continuing obligation on the seller to supplement the disclosure before closing. Whether a particular infestation meets that definition is a call for the seller’s attorney. Not for the appraiser, and not for the agent.

The practical move for a listing agent is simple enough. A missing checkbox is not a missing question. If a seller tells you about an active problem, get counsel in early. Three days before closing is too late to treat and document.

When the Inspection Itself Has to Stop

No assignment is worth a health risk. The appraiser makes that call on the spot. Leaving early protects the appraiser, but it also thins out the property observations. So the report has to disclose the limitation.

That disclosure travels. A reviewer sees it, the lender sees it, and most of the time it buys a second trip. In practice that is the expensive part of a pest problem. Not the value, the calendar. The return visit waits on treatment, and the report reconciles afterward.

One more thing an experienced appraiser watches for. Pests are usually a symptom. Standing water in a crawl space, a slow leak under a kitchen sink, a blocked floor drain in a basement. Reporting the roaches and skipping the water stain gets you half the story. The less useful half.

Clear the Condition Before the Report Locks It In

If you already know about a problem, deal with it before you order the appraisal. Treat the property, keep the invoice, and hand it over at the inspection. A documented cure gives the appraiser something concrete to report. It also gives the lender a clean way to close the condition out.

When the timing does not allow that, say so before the visit. A known condition someone raised openly reads very differently than one the appraiser found on arrival. Either way, the report will describe what was there. The only part you control is whether it also describes what you did about it.

Condition Problem Standing Between You and a Closing?

Tell us what the property looks like now. We will tell you what the report will have to say about it, and what your lender is likely to ask for next.

Request Your Appraisal

Frequently Asked Questions

Can a pest infestation lower a home appraisal?

Usually not on its own. The appraiser reports what is visible and comments on the effect on value and on marketability. A minor problem that someone already treated often changes neither. A severe one can move both, because buyers price in the cure and the uncertainty around it.

Do appraisers inspect for pests?

No. An appraiser is not a pest inspector and does not diagnose infestations or recommend treatment. The inspection covers the accessible areas of a property. The report then reflects adverse conditions that were apparent during the visit.

What does a subject to appraisal mean?

It means the value opinion rests on something happening first. That might be a specific repair, or an inspection by a qualified professional. Fannie Mae asks for that approach when an appraisal shows evidence of infestation, dampness, or abnormal settlement.

Does Illinois require a seller to disclose a pest problem?

The state disclosure report asks two pest questions. Both are limited to termites and other wood boring insects. Other infestations have no checkbox on the form. Whether one still counts as a material defect is a question for the seller’s attorney.

Should I treat the property before the appraisal?

When the timing allows, yes. Treating first and keeping the invoice gives the appraiser something to document. It also gives the lender a cleaner file. If treatment cannot happen first, tell the appraiser before the visit rather than after.

Appraisals That Document Condition Properly

PahRoo Appraisal & Consultancy works out of Lincolnwood and covers Chicago and Cook County, along with Dallas, Philadelphia, Phoenix and Naples. Michael Hobbs, MAI, SRA, signs every report. Our residential appraisal team handles condition-heavy assignments regularly. You can also read how a home appraisal runs from order to delivery, or see what our Chicago appraisal work covers.

Alt: Longwood Gardens in Chester County, an iconic landmark near the single-family housing market.
Chester County Single Family Home Prices Explained

Here is a puzzle from one county in one month. In May 2026, Redfin put the Chester County median at $551,745 while brokerage Long & Foster put it at $570,000. Same homes, same month, an $18,000 gap. So anyone tracking Chester County single family home prices runs into the appraiser’s oldest lesson early: the number depends on who is counting, and how. This guide covers what the prices are doing, why sources disagree, and what actually moves value here.

By the end of this article, you’ll know:

  • Where Chester County prices stand, with sources named.
  • Why different data feeds give different answers for the same county.
  • What drives value here, and when an independent appraisal earns its fee.

Where Chester County Single Family Home Prices Stand

The short version: firm, on tight supply. Per local reporting on May 2026 data, the county median held in the mid-$500,000s, up modestly from a year earlier, with homes selling at roughly 100% to 103% of their list prices. Pennsylvania’s statewide inventory climbed nearly 12% that month to more than 44,800 listings, yet still sat about 5% below year-earlier levels.

The summer-2025 picture tells the same story from another angle. That July, the county median reached $595,000, up about 3.5% year over year, while competitive homes went under contract in a median of six days. So the pattern across seasons holds: demand stays ahead of supply, prices drift up rather than spike, and well-priced homes do not wait long. Chester County behaves like what it is, the affluent western anchor of the Philadelphia suburbs.

Why Two Sources Give Two Answers

Back to that $18,000 gap. It is not an error. A median moves with the mix of what happened to sell, so a month heavy in townhome closings reads lower than one heavy in estate properties, even if no individual home changed value. Different feeds also cover different slices of the market and define “single family” differently. Repeat-sales indexes measure something else again.

County-level data has a second trap: small samples. With a few hundred sales a month, one unusual transaction can bend a ratio or a median visibly. So when a county dashboard shows a wild spike, the right response is suspicion, not a headline. Treat every single-source number as a rough bearing. Then remember what none of them measure: your house. Averages describe the county, and you are not selling the county.

What Actually Drives Value Here

Underneath the monthly numbers, a few durable forces set Chester County prices. Land is the first, because lot sizes here run larger than the inner suburbs and buyers pay for ground. School district reputation is the second, with premiums that persist across market cycles. The third is commuter geography, as access to Philadelphia and the Route 202 corridor employment base keeps demand steady. And the county sells a lifestyle the data cannot see, the Brandywine countryside character anchored by places like Longwood Gardens. Those forces move slowly, which is why the county’s prices tend to hold rather than swing. That stability is the county’s quiet pitch to buyers, too. Values that hold are easier to finance, easier to insure, and easier to defend in court years later.

When a Chester County Appraisal Earns Its Fee

Three situations bring this market’s owners to an appraiser. Buyers paying 100% or more of list want evidence the price holds up before committing, because paying over list on a mispriced home is how equity evaporates quietly. Picture the common case. A well-kept colonial lists at $575,000 and draws three offers in a weekend. Winning may take $590,000. So the question is not whether you can win. It is whether the house supports the number once the adrenaline fades. An appraisal answers that before your deposit depends on it. Sellers want a defensible list price in a market that punishes overpricing with silence. And attorneys handling estates and divorces in the western suburbs need values that survive scrutiny, often as of a past date, which is retrospective appraisal work.

PahRoo covers Chester County through our Pennsylvania-licensed appraiser based in Philadelphia, alongside Philadelphia, Montgomery, Delaware, and Bucks counties. Our appraisers are also available for court testimony. So the comps behind your number come from someone working this market, not a national average.

Trust the Trend, Verify the House

Put it together and the advice is simple. The county data earns your trust at the trend level, since multiple sources agree prices are firm on tight supply. It earns suspicion at the decimal level, where feeds disagree and small samples wobble. And it earns nothing at the level of your specific property, because no feed has seen it. For the decision in front of you, get the trend from the data and the value from an appraisal. Our Philadelphia appraisal guide covers how that process reads this region, block by block.

Same county, same month, two different medians.

Your house deserves one defensible number. Get it from a Pennsylvania-licensed appraiser who works Chester County’s evidence.

Get the One Number That Counts

Frequently Asked Questions

What is the median home price in Chester County?

As of May 2026, sources placed the county median in the mid-$500,000s, with Redfin reporting $551,745 and Long & Foster reporting $570,000, each up modestly year over year. The gap between sources reflects different data coverage and sales mix, not an error.

Are Chester County homes selling above asking price?

Often at or slightly above it. Recent local reporting shows homes selling at roughly 100% to 103% of list prices, and in summer 2025 competitive properties went under contract in a median of six days. Well-priced homes move quickly, while overpriced ones sit.

Why do Redfin and local brokerages show different Chester County prices?

Because medians depend on which sales each source counts and how it defines a single-family home. The monthly mix of townhomes versus estates moves medians even when values hold still, and small county samples let single transactions bend the numbers. So treat any one feed as a rough bearing.

What drives Chester County home values long term?

Durable local forces: larger lot sizes that make land a real share of value, persistent school district premiums, commuter access to Philadelphia and the Route 202 employment corridor, and the Brandywine countryside character that keeps demand steady across cycles.

Does PahRoo appraise homes in Chester County?

Yes. Our Pennsylvania-licensed appraiser based in Philadelphia covers Chester County along with Philadelphia, Montgomery, Delaware, and Bucks counties, for purchases, listings, estates, and divorces. Our appraisers are also available for testimony in court.

County Evidence, Pennsylvania License

PahRoo Appraisal & Consultancy delivers defensible valuations across its markets. Michael Hobbs founded the firm in Chicago, and more than two decades of appraisal practice stand behind it. Pennsylvania assignments run through our Philadelphia-based, Pennsylvania-licensed appraiser. Maybe you need a residential appraisal before buying or listing in Chester County. Maybe an estate or divorce calls for broader appraisal services with testimony behind them. Either way, the number comes from this market’s evidence.


Liberty Bell with Philadelphia skyline, real estate appraisal
Philadelphia Appraisal Guide for Buyers and Owners

Philadelphia prices do not move in neighborhoods. They move in blocks. One stretch of rowhomes can hold a gut renovation, an estate sale in original condition, and a flipped rental. All three share a wall. So a Philadelphia appraisal has a harder job than most. It sorts real value differences from cosmetic ones, door by door, in America’s great rowhouse city. This guide covers how that works and when you need it.

By the end of this article, you’ll know:

  • Why Philadelphia values swing block to block.
  • The local factors an appraiser weighs, from historic limits to the city’s assessments.
  • When buyers, owners, and attorneys should order an independent appraisal.

Why a Philadelphia Appraisal Is a Block-Level Job

Philadelphia is the sixth-largest city in the country, and most of it was built as rowhouses. Within a few miles you move from historic Society Hill and Old City to Center City condo towers. Keep going and you hit University City student housing, Northeast Philly family blocks, and fast-changing Fishtown and Point Breeze. So comparable sales behave strangely here. Two homes in the same zip code, even on the same street, can deserve very different values.

That is exactly the environment where listing prices and online estimates mislead. An automated model averages across the variation, while a buyer pays for one specific house on one specific block. We covered the general problem in our Zestimate vs appraisal breakdown, and rowhouse markets make it worse. The tighter the housing sits, the more the differences hide inside.

Here is what that means in practice. A comp two blocks away in worse condition tells you little. A comp across the street from last month tells you a lot. So the skill is not finding sales. Philadelphia has plenty. The skill is knowing which handful actually describe your house, and what each difference between them is worth.

What an Appraiser Weighs in This Market

A licensed appraiser inspects the property, selects true comparables, and adjusts for the differences the market pays for. In Philadelphia, a few local factors carry extra weight. Condition spread tops the list, because a renovated rowhome and its original-condition twin are different products. Historic significance cuts both ways, too. Designation can support value while preservation limits constrain what an owner may change. Block trajectory matters more than neighborhood labels. Added square footage, such as a finished basement or rear addition, also counts when permitted and done right.

If you want the step-by-step of how any appraisal runs, our guide to the home appraisal process covers it. That piece walks from inspection to final report. The Philadelphia difference is not the process. It is how much judgment the comps demand.

The City’s Assessment Is Not Your Market Value

Philadelphia adds its own tax wrinkle. The city’s Office of Property Assessment determines what every property in Philadelphia is worth for tax purposes. That assessed value then drives the real estate tax bill. But a mass assessment is not a market appraisal, and the two numbers regularly disagree. Owners who believe their assessment overshoots can request a review or file an appeal. Abatement and exemption programs can also reduce bills for those who qualify. An independent appraisal tells you whether the gap is real before you spend effort on an appeal. If you proceed, it becomes your evidence. Philadelphia owners check this more than most, because rowhome variation makes mass assessment hard.

Who Orders a Philadelphia Appraisal, and When

Buyers order one to avoid overpaying in a bidding situation, since lenders will not fund above appraised value anyway. Owners order one before listing, so the price respects the block instead of the zip code. Refinancers and investors use them to test their numbers. And attorneys order them constantly, because divorces, estates, and tax disputes in Philadelphia courts all need values that survive scrutiny. For those matters, our appraisers are available for testimony in Philadelphia courts. That turns the report from a document into a witness. Estate planners lean on the same service. Pennsylvania estates often hold a family rowhome nobody has valued in decades. The settlement then needs a number as of a specific date. A retrospective appraisal fixes the value to that date, with support that holds up if anyone objects.

PahRoo’s Pennsylvania work runs through a Pennsylvania-licensed appraiser based in Philadelphia. Coverage spans the city plus Montgomery, Delaware, Bucks, and Chester counties. So the comps come from someone who knows which blocks are moving, not from a spreadsheet three states away.

Price the Block, Not the Zip Code

The thread through all of it: Philadelphia rewards specific knowledge and punishes averages. Before you buy, list, refinance, appeal, or litigate, get a value built from your block’s actual evidence. The city’s variety is the whole charm of the place. It just should never be a surprise on your settlement sheet.

Buying or selling in rowhome country?

Get a Philadelphia appraisal from a Pennsylvania-licensed appraiser who reads the block, across the city and four suburban counties.

Value My Philadelphia Property

Frequently Asked Questions

How much do Philadelphia home values vary within a neighborhood?

Substantially, because most of the city is rowhouse stock where condition varies house to house. A renovated home and its original-condition neighbor can share a wall and deserve very different values. So appraisers work at the block level rather than relying on neighborhood averages.

Is the city’s assessed value the same as my home’s market value?

No. The Office of Property Assessment sets assessed values for tax purposes across every Philadelphia property. Mass assessments regularly diverge from market value, though. Owners who believe their assessment overshoots can request a review or file an appeal. An independent appraisal shows whether the gap is real.

Do historic designations affect Philadelphia appraisals?

Yes, in both directions. Historic significance can support value in districts like Society Hill and Old City. Preservation rules, though, limit what owners may change, which constrains some buyers. An appraiser weighs both effects against how the local market actually prices designated homes.

When should a buyer order their own appraisal in Philadelphia?

Before committing in a competitive situation, especially on a renovated rowhome where the premium over nearby sales is large. Lenders will not fund above appraised value. So knowing the number early protects your deposit, your financing, and your negotiating position.

Which counties does PahRoo cover from Philadelphia?

Philadelphia plus Montgomery, Delaware, Bucks, and Chester counties, with reports completed by a Pennsylvania-licensed appraiser based in Philadelphia. Our appraisers are also available for testimony in Philadelphia courts for divorce, estate, and tax matters.

Pennsylvania Reports, Signed in Philadelphia

PahRoo Appraisal & Consultancy delivers defensible valuations across its markets. Michael Hobbs founded the firm in Chicago, and more than two decades of appraisal practice stand behind it. Philadelphia-area assignments are completed by our Pennsylvania-licensed appraiser based in the city. Maybe you need a residential appraisal before a purchase or sale. Maybe an estate, divorce, or assessment dispute calls for broader appraisal services and courtroom testimony. Either way, the value comes from the block’s evidence, read by someone who knows the block.


Real estate appraiser working alone in a home symbolic of isolation in the appraisal profession
Why Most Appraisers Are Flying Solo and What We Can Do About It


In today’s evolving housing market, many real estate appraisers are flying solo and it’s starting to take a toll on both the profession and the professionals. In this episode of Appraisers on Purpose, we sit down with Susan Alley, a reviewer, former staff appraiser, business owner, and industry advocate who brings wisdom, warmth, and a sharp eye for what’s missing in today’s profession.

Appraising isn’t just technical — it’s personal.
And for many of us, it’s also isolating.

But does it have to be?

From glue-sticking reports in the office to building a nationwide compliance review firm, Susan’s story is real, relatable, and full of insights for appraisers at every stage of their journey.

🎙️ What You’ll Learn:

  • Why most appraisers are still working solo — and why that’s a problem
  • How reviewing hundreds of reports gave Susan a powerful “aha” moment
  • What every trainee should experience before ever setting foot in a house
  • The reality of tech changes, UAD updates, and industry burnout
  • Why “being nice” might be the most undervalued skill in appraisal

“There is no perfect appraisal. But there’s always a way to get better — and it usually starts with connection.” — Susan Alley

▶️ Watch the Episode:

Whether you’re a seasoned appraiser or just starting out, this conversation will challenge how you think about connection, compliance, and what it really means to build a career with purpose.

If you’re an appraiser looking to connect or grow professionally, our real estate appraisal services offer insight into both the technical and relational sides of the work. Whether you’re flying solo or building a team, the right support can make all the difference.

Listen on Spotify

Get in touch with us!


P.S. If you’re looking to feel less alone, stay sharp, and help shape the future of our industry — don’t miss this one.


Suburban neighborhood with red HOA risk sign, representing potential impact of homeowners associations on property value.
Can Your HOA Hurt Your Home’s Value

When you buy into a condo or HOA community, you buy two things. One is your unit. The other is a share of an organization with a budget, a board, and a repair list. So your home’s value rides on both. An HOA that keeps the property sound and the reserves funded protects every unit’s price. One that defers repairs and dodges hard votes quietly taxes every owner, whether or not the dues feel cheap.

By the end of this article, you’ll know:

  • How association health reaches your unit’s price, in both directions.
  • The lending rules that can make a whole building hard to finance.
  • What an appraiser checks about the HOA, and how to check it yourself first.

How an HOA Shows Up in Your Home’s Value

The connection runs through three channels. First, condition. In a shared building, the roof, facade, and mechanicals belong to everyone, so the association’s maintenance record becomes part of your unit’s condition rating. Second, the buyer pool. Strict rental caps or pet bans shrink the set of people who can buy your unit, and a smaller pool means softer pricing power. Third, the monthly math. Buyers weigh dues against what the dues deliver, so high assessments with little to show for them read as a discount waiting to happen.

None of this appears in your unit’s listing photos. But appraisers and experienced buyers price it anyway, because an association’s problems eventually arrive at every owner’s door as an assessment, a repair, or a harder sale.

The Lending Gate Most Owners Never See

Here is the part that changed in recent years. Fannie Mae, which buys a huge share of condo loans, now screens the whole project before it will touch a loan on any unit. A September 2026 summary by Chicago-area condo law firm Kovitz Shifrin Nesbit lays out the current rules. Projects needing critical repairs, such as structural problems, water intrusion, or unsafe balconies, are ineligible until the repairs are done. So are projects that failed a local inspection. Budgets must put 10% of assessment income into replacement reserves, and a special assessment cannot substitute for that line. The screws tightened again in August 2026 on how reserve studies can be used.

Now follow the consequence. If a building lands on Fannie Mae’s ineligible list, buyers cannot easily get conventional financing for any unit in it. The buyer pool collapses to cash and specialty lenders, and cash buyers expect a discount for the trouble. An owner who kept a perfect unit can still watch its value sag because the association skipped a roof vote three years ago. That is the ripple effect in its sharpest form: the HOA’s balance sheet became the building’s credit score.

The math stings quickly. Say a unit would appraise at $300,000 in a healthy building. If the project goes ineligible, the realistic buyers become cash investors hunting a deal. Offers arrive at $255,000, and the owner eats a 15% haircut for a repair budget they never controlled. So the cheapest dues in town can be very expensive.

What an Appraiser Checks Beyond Your Front Door

So when we appraise a unit in a managed community, the inspection does not stop at your door. We look at the association’s budget and reserve funding, pending or active litigation, special assessments passed or looming, the share of units that are owner-occupied, and how the common elements actually present. Each item feeds either the condition analysis or the marketability analysis, and sometimes both.

The same review can run in your favor, too. A well-run association with funded reserves, clean financials, and maintained common areas is a selling point an appraisal can support. Buyers pay for certainty, and a healthy HOA is certainty you can document.

Read the Association Before You Buy or List

You can do a useful version of this homework yourself. Before buying, request the association’s budget, reserve information, meeting minutes, and any disclosures your state requires, then read the minutes for fights about money. Ask whether any special assessments are planned. Before listing, do the same for your own building, because surprises travel from the HOA packet to the negotiating table at the worst moment. If the association has a known problem, price and disclose with eyes open rather than losing the deal in week three.

Value the Unit and the Association Together

The clean takeaway: a condo’s value is never just the unit’s value. It is the unit times the association’s health, and lenders now grade that health formally. A pre-purchase appraisal tells you what the unit is worth inside its building’s reality. A pre-listing appraisal surfaces the association issues a buyer’s lender will find anyway, while you still have time to respond. If you are new to the process, our guide to the home appraisal process covers the basics. Either way, know what the association is doing to your number before the market tells you.

Your home’s value has a co-signer: the HOA.

Get an appraisal that reads the association’s health along with your unit, before a buyer’s lender reads it for you.

Appraise the Whole Picture

Frequently Asked Questions

Does an HOA affect property value?

Yes, in both directions. A well-run association with funded reserves and maintained common areas supports every unit’s value, while deferred maintenance, litigation, or weak finances drag it down. The association’s condition and marketability effects flow directly into how appraisers and buyers price each unit.

Can a weak HOA make my condo hard to sell?

It can make it hard to finance, which amounts to the same thing. Fannie Mae screens entire condo projects, and buildings with critical repair needs, failed inspections, or underfunded reserves become ineligible for conventional loan purchase. That shrinks the buyer pool to cash, and cash buyers expect discounts.

What do appraisers check about an HOA?

The association’s budget and reserve funding, pending litigation, special assessments passed or planned, the owner-occupancy share, and the real condition of common elements. Each factor feeds the unit’s condition rating or its marketability analysis, so association health shows up in the appraised value.

What makes a condo building ineligible for conventional loans?

Under current Fannie Mae project standards, triggers include critical repair needs such as structural problems or water intrusion, failed local inspections, and budgets that do not allocate 10% of assessment income to replacement reserves. Projects stay ineligible until the problems are documented as fixed.

Should I get an appraisal before buying into an HOA community?

For a significant purchase, yes. An appraisal values the unit inside the reality of its association, factoring in dues, condition of common elements, and marketability. Pair it with your own review of the budget, minutes, and disclosures, and you buy with the full picture.

Appraisals That Audit the Association Too

PahRoo Appraisal & Consultancy has valued homes in condo and HOA communities across the Chicago area for more than two decades. An appraiser holding both MAI and SRA designations leads the firm. Maybe you need a residential appraisal before a purchase or listing. Maybe an estate, divorce, or dispute calls for broader appraisal services. Either way, the association’s health gets read along with the unit, because that is where condo value actually lives.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712