Tag: divorce appraisal

Request a quote

Our blog

Latest news
& events

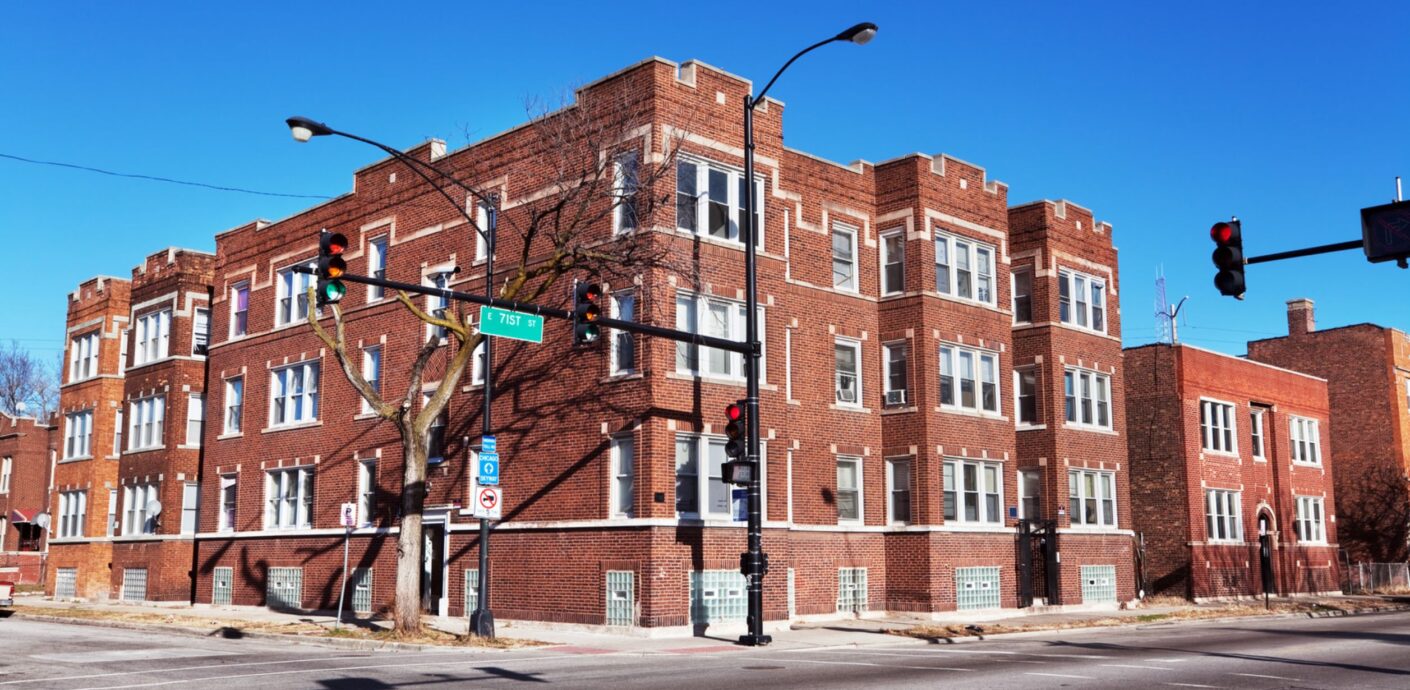
Chicago six-flat apartment building valued in a commercial real estate divorce appraisal
How Commercial Property Gets Appraised in a Divorce

A divorce with a six-flat, a strip center, or an office condo on the balance sheet needs more than a house appraisal. A commercial real estate divorce appraisal values the building the way investors do, by what it earns and what buyers pay for that income. For divorce attorneys, that changes what you ask for at engagement and what you can defend later.

By the end of this article, you’ll know:

  • Why commercial property needs a different appraisal than the marital home
  • How the valuation date, the leases, and the business affect the number
  • What CPAs should line up for the tax side of the split

Why a Commercial Real Estate Divorce Appraisal Works Differently

Most marital homes get valued mainly from recent sales of similar houses. A rented building is different, because the rent is a big part of what a buyer is paying for.

So the appraiser looks at more than sales. Federal banking guidelines sum up the USPAP rule well. According to the Interagency Appraisal and Evaluation Guidelines, an appraisal must include each approach to value that applies, whether sales comparison, income, or cost. It also has to explain any approach it leaves out. Our guide to the three approaches to value covers how each one works.

In a leased building, that usually puts real weight on the income. Our article on the income approach for commercial property shows how rent becomes a value.

Illinois also sets the standard the report has to meet. Under 750 ILCS 5/503, the court uses a fair market value standard. It also has to make specific factual findings on values. So the report should support a number a judge can actually write into those findings.

Settle the Valuation Date Before the Appraiser Starts

Illinois gives the court room on timing. Under Section 503, the valuation date is the date of trial or another date the parties agree to or the court orders. That flexibility matters more for a building than for a house.

Commercial values move with leases and capitalization rates. The federal guidelines list changes in cap rates and lease terms among the things that can make an older appraisal stale. A tenant leaving, or a lease renewing at a new rent, can shift the number between filing and trial.

So agree on the date, or ask the court to set it, before the work begins. If that date has already passed, the assignment becomes a retrospective appraisal as of the earlier date. Our piece on the date of value problem in divorce explains why timing moves value, and our explainer on cap rates shows how small rate changes add up.

Other states handle valuation dates their own way. If the building sits in another market we serve, our Dallas, Philadelphia, Phoenix, and Naples teams appraise under that state’s rules. In Cook County, our Chicago appraisal team handles the work.

Leases Can Raise or Lower What the Building Is Worth

A building with tenants comes with its leases. A long lease at below-market rent can hold value down for years. An above-market lease with a strong tenant can do the opposite, at least until it ends.

Lenders already watch for this. The federal guidelines require lending appraisals to account for partially leased buildings and non-market lease terms. A divorce file raises the same facts, so the report should compare each lease with market rent and show the effect.

Also watch for leases between family entities. If the couple’s own company rents the space, the rent may not match the market. The appraiser can report what market rent would be, and counsel can decide what that means for the case. We cover that setup in more detail in our article on the family business’s real estate.

Keep the Building Separate From the Business

A building and the business inside it are two different assets. The federal guidelines draw the same line for lenders. They say going concern value and value in use may not stand in for market value, and any such opinion has to be identified separately.

That matters when one spouse runs a restaurant, clinic, or shop in a building the couple owns. The real estate appraisal should value the land and building only. Any business value belongs with a business valuator, and the two reports should not count the same dollars twice. Our conversation on going concern appraisal with Bruce Jones, MAI covers how appraisers think about that split.

Ownership through an LLC raises a related point. PahRoo values the real estate itself. What a spouse’s share of that LLC is worth can be a separate question, so confirm early who is answering it.

For CPAs, the Same Value Can Carry Different Tax Results

Federal tax rules usually let a building pass between divorcing spouses without immediate gain or loss. Under Treasury Regulation 1.1041-1T, that applies to transfers incident to divorce. The spouse who receives the building also takes the other spouse’s adjusted basis.

So two buildings with the same appraised value may not be equal after tax. Consider a hypothetical. Building A and Building B each appraise at $2,000,000. Building A has an adjusted basis of $600,000, and Building B has $1,800,000. On a later sale at that price, Building A would show $1,400,000 of gain, while Building B would show $200,000.

Illinois courts can weigh this too, since Section 503 lists the tax consequences of the division as a factor. A few steps help. First, ask the transferring spouse for basis and holding period records, which the regulation says the transferor must supply. Second, match the appraisal’s effective date to the business valuation date when both assets are in play. Third, get the appraiser the rent roll, the leases, and three years of operating statements early.

What to Put in the Engagement Letter

Start with the intended use and the intended users. The federal guidelines note that an engagement letter identifies both, as USPAP defines them, and that sets who can rely on the report. Then state the valuation date, the property interest, and whether you expect testimony. Illinois courts can also bring in their own financial experts under Section 503, and counsel may examine a professional the court designates as its witness. A tight engagement letter gives you a report that is easier to defend if the other side attacks its scope.

Dividing a Commercial Building in the Divorce?

PahRoo appraises the real estate on its own, with the valuation date, the leases, and the property interest spelled out. Tell us about the building and the date the case needs.

Order a Commercial Appraisal

Frequently Asked Questions

How is commercial property appraised in a divorce?

The appraiser considers the sales comparison, income, and cost approaches and uses each one that applies. For a leased building, the rent and the leases usually drive much of the analysis.

What valuation date does an Illinois divorce use?

Under 750 ILCS 5/503, it is the date of trial or another date the parties agree to or the court orders. Settle the date before the appraisal starts.

Do tenant leases change a building’s value in a divorce?

Yes. A lease above or below market rent can raise or lower value, so the report should compare each lease with market rent.

Does a commercial real estate appraisal include the business?

No. It values the land and building. A business operating there, or a spouse’s share of an LLC that owns the building, is a separate valuation question.

Is transferring a building between divorcing spouses taxable?

Generally not at the time of transfer. Under Treasury Regulation 1.1041-1T, the receiving spouse takes the other spouse’s adjusted basis, so the gain can show up on a later sale. A tax advisor should confirm the details.

Commercial Appraisals for Family Law Cases

PahRoo Appraisal & Consultancy appraises commercial and investment property for family law attorneys and CPAs in Chicago and Cook County, Dallas, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, signs our Illinois reports. See our commercial appraisal services to learn how we work.
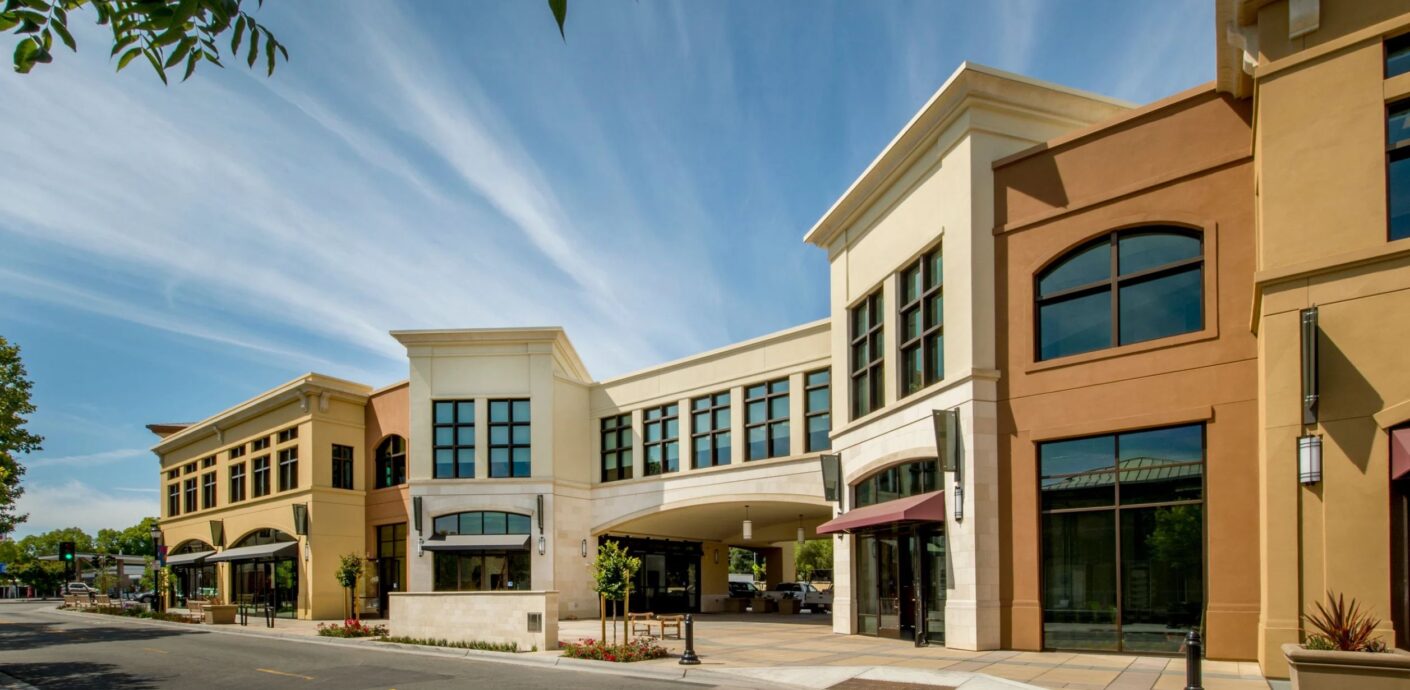
Owner-occupied family business real estate being valued in a divorce
The Family Business’s Real Estate and What Gets Appraised in a Divorce

When a divorcing client owns a business, the building often gets lost in the business valuation. Maybe the company owns it outright. Maybe a spouse holds it in a separate LLC and charges rent. Either way, family business real estate usually needs its own appraisal, and how that appraisal fits with your valuation decides whether the numbers hold together.

By the end of this article, you’ll know:

  • Which real estate questions the appraiser answers, and which stay with you
  • How related-party rent can count the building twice
  • What to settle with counsel before anyone sets a value

Family Business Real Estate Is Its Own Asset

A business and the building it occupies are different things to value. The business earns its money from customers, staff, and know-how. The building earns its value from location, size, condition, and the rent it could command.

So an appraiser values the real estate, and a business valuator values the company. In practice, the two reports have to speak to each other. If they don’t, one asset can show up twice, or the building can vanish into a goodwill number nobody can test.

The appraiser’s job here is narrow on purpose. It covers the market value of the land and building. The enterprise, its equipment, and its customer list belong in the business valuation. When a property runs as a going concern, like a restaurant or a car wash, the appraiser separates the real estate from the business. Our conversation on going concern appraisal with Bruce Jones, MAI walks through how that split works, and our piece on special use property covers buildings with few comparable sales.

Who Holds Title Changes the Work

Start with the deed. Ownership usually falls into one of three patterns, and each one asks something different of your model.

First, the operating company may own the building. Then the real estate sits on the company’s balance sheet, often at depreciated cost. That book figure can be far from market value, so an asset-based method needs an appraised number in its place.

Second, one or both spouses may own the building personally or through a separate LLC. The company then pays rent, or sometimes pays none. Now there are two assets to account for, the business and the real estate holding.

Third, the company may rent from an unrelated landlord. In that case there is usually no family real estate to appraise at all. Still, the lease terms affect the business’s costs.

Whether any of these interests is marital, separate, or mixed is a legal question for counsel and the court. Under 750 ILCS 5/503, property acquired during the marriage is presumed marital. But the appraisal stays the same either way. It reports what the property is worth, and the attorneys argue what that value means.

Related-Party Rent Is Where Values Get Counted Twice

This is the part that matters most for your normalization work. When spouses own the building and the business pays them rent, that rent is a related-party number. It may not match the market.

Consider a hypothetical. A family distribution company uses a warehouse owned by the spouses’ LLC and pays no rent. The appraiser concludes the market rent is $60,000 a year. If the business valuation never deducts that rent, the company’s earnings look $60,000 richer than they would under a market lease. That extra income then gets capitalized into business value.

Meanwhile, the appraisal values the warehouse using that same $60,000 of income. At a hypothetical 8% capitalization rate, the building comes in near $750,000. Now the same stream of rent props up two values. The fix is to adjust the business’s rent expense to the market rent from the appraisal, so each asset carries only its own income.

The reverse happens too. Rent can rise before a divorce, which drains reported business income into the real estate entity. Either way, the market rent figure from the appraisal gives you a tested benchmark. For how appraisers build that income figure, see our guide to the income approach for commercial property.

Fee Simple or Leased Fee Should Be Decided Up Front

If a lease exists between the business and the property owner, the appraiser has to know which interest to value. A fee simple value assumes the building is free of that lease and could rent at market terms. A leased fee value reflects the owner’s position subject to the actual lease, including its rent and remaining term.

When the contract rent matches market rent, the two values tend to land close together. When a related-party lease sits well above or below market, they can split apart. A reading on leased fee valuation from Illinois State University lays out how contract rent and market rent drive that difference.

Because the lease was written inside the family, it may not survive the divorce. So the right interest to appraise is a scoping call to settle with counsel and the appraiser before any work begins. Write it into the engagement letter.

For Divorce Attorneys, Settle the Scope Before Anyone Values Anything

Attorneys can head off most of these problems early. A few steps make the experts’ work fit together.

Pull the deed and the entity records first. Who holds title, and through what entity, tells everyone which pattern you have. Then request every lease and the rent actually paid for several years, including any recent changes.

Next, align the valuation date. Section 503(k) sets the date of trial unless the parties agree on another date or the court orders one. The appraiser and the business valuator should work to the same date. Our article on the date of value in a divorce appraisal explains why mismatched dates cause trouble.

Finally, have both experts share their real estate figures before either report is final. That includes the market value, the market rent, and the interest appraised. Section 503(l) also lets the court seek advice from financial experts or other professionals, so a clean, consistent record helps if the court brings in its own.

Get the Building Valued Before the Business Number Is Set

If your engagement involves a business that owns or occupies real estate, ask for the appraisal early. You need the market rent to normalize earnings and the market value to complete the balance sheet. Waiting until the business valuation is done invites rework, or worse, competing appraisals in divorce court that disagree on facts nobody checked.

Is the Building Hiding Inside the Business Value?

PahRoo appraises the real estate on its own, with a market rent figure your business valuation can use. Tell us about the property and who holds title.

Value the Building Separately

Frequently Asked Questions

Is the family business’s building marital property?

That is a legal question for counsel and the court. Illinois presumes property acquired during the marriage is marital, but title, timing, and contributions all matter. The appraisal reports the property’s value either way.

How is company real estate valued in a divorce?

An appraiser sets the market value of the land and building, usually relying on comparable sales and an income analysis based on market rent. Illinois courts value divided assets at fair market value.

Does the business or the building get appraised?

Usually both, by different experts. A real estate appraiser values the property, and a business valuator values the company. Their reports should share the same date and the same market rent figure.

Who owns the property a business uses?

Check the deed. The company may own it, the spouses may hold it personally or through a separate LLC, or an unrelated landlord may own it. Each pattern changes what needs appraising.

Can the building be counted twice in a divorce?

Yes. If the business pays no rent or below-market rent to the spouses, its earnings look higher and the building’s income can inflate the business value too. Adjusting rent to market avoids that.

Real Estate Valuation That Fits the Financial Picture

PahRoo Appraisal & Consultancy appraises commercial and owner-occupied property for CPAs and family law attorneys across Cook County and the Chicago area. Michael Hobbs, MAI, signs our Illinois reports and is available to testify on them. See our commercial appraisal services, our overview of appraisals in divorce proceedings, and our Chicago appraisal coverage.

Appraiser filling up an appraial report of a Chicago brick home during a home appraisal
When Do You Actually Need a Home Appraisal?

Most people think about an appraisal only when a lender orders one. So when do you need a home appraisal? More often than that, and a few of those moments carry real money, because the number ends up in a tax return, a settlement, or a closing statement.

By the end of this article, you’ll know:

  • Which life events usually call for an appraisal, and which ones don’t
  • When the lender handles it and when you order one yourself
  • What a buyer can do if the appraisal comes in low

When Do You Need a Home Appraisal for a Mortgage?

If you’re buying with a loan or refinancing, the lender orders the appraisal and you usually pay for it. The report protects the lender’s collateral. It tells them the home supports the loan amount.

That isn’t always the case anymore, though. On some loans, Fannie Mae’s underwriting system can offer value acceptance, which means no appraisal for that transaction. It’s the lender’s option, not yours. Two to four unit buildings and homes priced at $1,000,000 or more don’t qualify. If you’re curious about the trade-offs, we wrote about the risks of skipping the appraisal.

When there is an appraisal, you get to see it. Federal rules under the Equal Credit Opportunity Act require the lender to give you a copy promptly, or three business days before closing if that comes first. You can waive that timing, but think twice before you do.

Buying a Home? Read the Appraisal Before You Close

Buyers often skim the appraisal for one number and move on. Instead, read the whole thing. Check the square footage, the bedroom and bathroom count, and the condition notes. Then look at the comparable sales and ask whether they really match your block.

If the value comes in below the contract price, you have a few paths. You can ask the seller to lower the price, cover the gap in cash, or lean on an appraisal contingency if your contract has one. Your agent or attorney can tell you how many days you have and what the contract allows.

You can also challenge the number. On Fannie Mae loans, a buyer can request one reconsideration of value per appraisal, through the lender, with up to five alternative comparable sales. It has to happen before closing. So gather your sales early, and pick ones that are recent, close by, and similar in size.

Paying cash? No lender means no required appraisal. Still, a cash buyer has the most to lose from overpaying, and an online estimate won’t catch a failing roof. Our piece on Zestimates versus appraisals explains why the two numbers drift apart.

Dropping PMI Before It Ends on Its Own

If you put down less than 20 percent on a conventional loan, you’re probably paying private mortgage insurance. According to the Consumer Financial Protection Bureau, you can ask your servicer to cancel it once your balance reaches 80 percent of the home’s original value. The servicer can ask for evidence, such as an appraisal, that the value hasn’t dropped below that original figure.

PMI also ends automatically at 78 percent of original value if you’re current on payments. Your servicer, or investors like Fannie Mae and Freddie Mac, may allow earlier removal under their own guidelines. Before you pay for a report, call your servicer and ask which appraisers and report types they accept. If they’ll take an independent report, PMI removal is one of the residential assignments we handle across Chicago.

Inheriting, Settling an Estate, or Gifting a Home

This is where a lot of families get caught. When you inherit a house, IRS Publication 551 says your basis is generally its fair market value on the date of death. An alternate valuation date can apply if the estate’s representative elects it. That basis affects the tax when you sell, so a documented value matters even if you plan to sell quickly.

The appraisal in that case looks backward. It values the home as of the date of death, sometimes months or years later. Our guides on appraisals for inherited property and the date-of-death appraisal walk through how that works.

Gifts follow different basis rules, tied to what the giver paid. A donation to charity brings its own qualified appraisal requirements. Either way, your CPA should weigh in on the tax side before the deed changes hands.

Divorce, Buyouts, and Splitting a Home

When a marriage ends and one spouse keeps the house, the buyout number usually starts with an appraisal. The attorneys or the court set the valuation date, and the appraiser values the home as of that date. If both sides hire their own appraisers, the reports often differ, and the gap becomes part of the negotiation. Once you have a value, our marital home buyout calculator gives a rough sense of the payment after the mortgage and other liens.

The same logic applies when siblings split an inherited home or co-owners part ways. One person keeps the property, and everyone needs a value they can trust. We cover this in more depth in appraisals in divorce proceedings and our article on marital home buyouts.

Appealing a Property Tax Assessment

If your assessment notice looks high, you can appeal. In Cook County, the Board of Review hears appeals from owners who believe their property is over-valued. An appraisal is one of the stronger pieces of evidence you can bring, especially when your home differs from what the assessor’s model assumed. Our Cook County Board of Review guide covers timing and what the Board looks at.

Selling Without Guessing

Nobody requires a seller to get an appraisal. But a pre-listing appraisal can keep you from pricing too high and sitting, or too low and leaving money behind. It also gives you a head start if the buyer’s appraisal comes in short. Here’s how appraisers help sellers price a home.

Start With Why You Need the Number

The reason drives everything else. A lender’s appraisal answers the lender’s question, at the date of inspection. An estate, a divorce, or a tax appeal usually needs a different date and a report written for that purpose. So before you order anything, know who will read the report and what date the value has to match. Then ask the appraiser to build the assignment around that.

Not Sure Which Appraisal Fits Your Situation?

Tell us what happened, whether it’s an inheritance, a buyout, PMI, or a tax notice, and we’ll scope the right report and the right date of value.

Tell Us What You Need

Frequently Asked Questions

Do I need an appraisal if I’m paying cash for a home?

No lender means no required appraisal. Many cash buyers still order one because they carry all the risk if they overpay, and an independent appraiser looks at condition and local sales that online estimates miss.

Can I get a copy of my lender’s appraisal?

Yes. For a first mortgage on a home, federal rules require the lender to give you a copy promptly after it’s done, or three business days before closing if that comes first. You can waive the timing, but reading it early gives you time to spot errors.

What can I do if the home appraisal comes in low?

You can renegotiate the price, cover the difference, or use an appraisal contingency if your contract has one. On Fannie Mae loans, you can also request one reconsideration of value per appraisal through your lender before closing, with up to five alternative comparable sales.

Can I reuse my mortgage appraisal for an estate or divorce?

Usually not. A mortgage appraisal answers the lender’s question as of the inspection date. Estates and divorces typically need a value as of a different date, in a report written for that purpose, so a new appraisal is the safer route.

Do I need an appraisal to remove PMI?

Often, if you ask to cancel it early. The CFPB says you can request cancellation once your balance reaches 80 percent of the original value, and the servicer can ask for evidence, such as an appraisal, that the value hasn’t dropped. Check with your servicer before ordering one.

About PahRoo Appraisal & Consultancy

Whatever brought you here, an inheritance, a buyout, or a tax bill, PahRoo starts by pinning down the purpose and the date of value, then builds the report around them. We’re headquartered in Lincolnwood and also serve Dallas, Philadelphia, Phoenix, and Naples, with residential, commercial, litigation support, and property tax appeal work. See our Chicago real estate appraisal services or learn more about our team.

Attorney comparing two competing appraisals in a divorce case side by side on a conference table
When Two Appraisals of the Same House Disagree in Court

Two appraisers walk the same Park Ridge house a few weeks apart. One report says $985,000 and the other says $840,000. It’s a hypothetical, but family law attorneys will recognize it. The competing appraisals divorce counsel bring to trial rarely disagree about everything. Usually the $145,000 sits in three or four specific choices, and each one can be found. So before anyone attacks the other side’s number, it pays to find out where the gap lives.

By the end of this article, you’ll know:

  • The five places two reports on the same house usually split
  • A step-by-step way to trace the gap to its sources before the deposition
  • What a rebuttal review covers, and what the CPA should do with two values

Why Competing Appraisals Divorce Courts See Rarely Match

Two competent appraisers can reach different values without either one being careless. An appraisal is an opinion built from data, and the choices stack up. In my experience the split shows up in five places.

The first is the date. Under 750 ILCS 5/503, the court uses fair market value as of the trial date, or another date the parties agree to or the court orders. If one report carries a March date and the other an October date, they measure two different markets. Our article on the date of value in a divorce appraisal covers how that date gets set.

The second is the house itself. One appraiser measured 3,150 square feet, and the other pulled 2,900 from the assessor’s record. One saw the finished basement, while the other never got past the kitchen because a spouse cut the visit short. Measurement method matters too. Fannie Mae has required the ANSI measuring standard on its loans since April 2022, but a divorce assignment isn’t a Fannie Mae loan. So ask each appraiser how the living area was measured.

The third is comparable selection, and it usually carries the most dollars. Two sales from a stronger school boundary or a newer subdivision will pull a value up. Leaving out the one sale that didn’t fit will do the same. The fourth is the adjustments: what each appraiser added or subtracted for size, condition, and location, and what market evidence backs each figure. The fifth is reconciliation, meaning which sales got the most weight at the end and why.

Trace the Gap Before You Attack the Number

Put the two reports side by side and work through them in order. It’s the same sequence I follow when counsel sends me an opposing report.

  1. Match the assignment terms. Compare the effective date, the definition of value, and the intended use on the first pages.
  2. Match the property. Compare living area, room count, lot size, condition rating, and what each appraiser inspected.
  3. Compare the sales. List every comparable in both reports, then mark the ones only one appraiser used.
  4. Compare adjustments on shared sales. If both used the same sale and adjusted it differently, that difference is pure judgment.
  5. Read both reconciliations. See which sales each appraiser leaned on at the end.
  6. Put a dollar figure on each difference. Then you know which fights matter.

Here is how that might run on the Park Ridge example. The 250 square feet of disputed living area, at a hypothetical $120 per square foot adjustment, accounts for $30,000. A seven-month difference in effective dates might explain $25,000. One appraiser rated the kitchen as updated and the other as average, worth perhaps $40,000. Then the last $50,000 comes from two sales in a stronger pocket that only one report used. Together those four items make up the full $145,000.

Now the dispute looks different. Two of the four items are facts. A tape measure settles the square footage, and the court’s order settles the date. Only the condition rating and the comparable selection are judgment calls, and they total $90,000. In practice, that is the real fight.

What the Judge Has to Work With

Section 503 requires the court to make specific factual findings on values. When the experts disagree, the judge resolves it as the trier of fact. Illinois appellate courts have long said that conflicts in valuation testimony are for the trial court. One 1998 decision added that a valuation within the range the experts testified to ordinarily will not be disturbed on appeal. How that applies to your case is counsel’s call. But from where I sit, it means the judge doesn’t have to adopt one report whole. A number in between is possible too.

So credibility is the contest. A judge reading two reports looks for the appraiser who verified the sales, supported each adjustment with market evidence, and inspected the whole property. Then cross-examination tests whether the explanation holds. We covered that test in what makes an appraisal defensible on the witness stand.

The statute also offers a third route. Under 503(l), the court may seek advice from its own financial experts or other professionals. That advice must be in writing, and counsel may examine the professional as a witness. So a third opinion can enter the case even if neither side orders one.

What a Rebuttal Appraisal Review Does

A rebuttal is usually an appraisal review. USPAP defines appraisal review as developing an opinion about the quality of another appraiser’s work, and Standards 3 and 4 govern it. The Appraisal Institute guidance on reviews makes two points attorneys should know. A reviewer evaluates the work, not the person. And a reviewer may or may not develop a separate opinion of value.

That second point shapes the engagement. A review without a value tells the court where the opposing report lacks support. A review with a value also gives the court another number, and the reviewer then has to support it like any appraisal. Sometimes the first kind is enough, because your retained appraiser’s report already supplies the value. So decide which one you need before you order it.

Timing matters as well. A reviewer needs the full opposing report, and ideally the workfile, well before the deposition. If you haven’t picked the person yet, our list of questions to ask an expert witness appraiser applies to reviewers too. One caution, though. The review should stay in the appraiser’s lane. Opinions about the other expert’s motives belong to counsel.

For the CPA Carrying Two Values Into the Schedules

Accountants often get both reports before anyone resolves the dispute, and the marital balance sheet still has to get built. Three habits keep your work clean.

First, don’t average the two numbers. An average has no effective date, no comparables, and no appraiser to defend it. Instead, run the balance sheet twice and show both. On the Park Ridge example, a $145,000 gap with an equal split of equity moves the equalizing payment by $72,500. That figure tells counsel what the fight is worth.

Second, check each report’s effective date against your own schedules. If the business valuation and the account balances are as of one date and an appraisal is as of another, say so in a footnote. Third, ask counsel for the gap analysis described above. Once you know $55,000 of the difference is date and square footage, you can model the likely range instead of the extremes.

Narrow the Fight to What Is Actually in Dispute

Most dueling appraisals get closer once someone does the tracing. So do it early. Stipulate to the effective date and the living area if you can, because those are facts. Then have a qualified reviewer put the remaining differences in writing, with a dollar figure on each. If the gap survives that, you’ll go into the deposition knowing which two or three questions matter. If it doesn’t, you may have found the settlement range instead. Our guide to disputed property value in an Illinois divorce lists the records to pull first.

Opposing Appraisal Just Landed on Your Desk?

Send us both reports. PahRoo prepares appraisal reviews under USPAP Standards 3 and 4 that show where the two values split and what each difference is worth. Michael Hobbs, MAI, SRA, signs our Illinois litigation work and testifies to it.

Request an Appraisal Review

Frequently Asked Questions

What happens when two appraisals disagree in court?

The judge decides value as the trier of fact. Each appraiser testifies and faces cross-examination, and the court weighs which opinion has better support. Under 750 ILCS 5/503, an Illinois court must make specific findings on the value of the property it divides.

Why do two appraisals of the same house differ so much?

Usually for a handful of traceable reasons: different effective dates, different measurements or condition ratings, different comparable sales, different adjustments, and different weight in the final reconciliation. Putting a dollar figure on each one shows which differences are facts and which are judgment.

How does a judge decide between competing appraisals?

By credibility and support. Judges look at whether the appraiser inspected the property, verified the sales, backed each adjustment with market evidence, and held up under cross-examination. Illinois appellate decisions say conflicts in valuation testimony are for the trial court to resolve.

What is a rebuttal appraisal?

Most often it is an appraisal review: a second appraiser’s written opinion about the quality of the other side’s report, prepared under USPAP Standards 3 and 4. The reviewer may stop there or may also develop a separate opinion of value.

Can you get a third appraisal?

Yes. Either side can retain another appraiser, subject to the court’s disclosure deadlines. Under 750 ILCS 5/503(l), an Illinois court may also seek written advice from its own financial experts or other professionals. Whether a third opinion helps is a strategy question for counsel.

Appraisal Review and Testimony for Contested Divorce Cases

When a second report turns a valuation into a dispute, family law attorneys and forensic accountants call PahRoo Appraisal & Consultancy. From our Lincolnwood office we prepare divorce appraisals and appraisal reviews across Chicago and Cook County, and the firm also works in Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, founded the firm and is available for deposition and trial in Cook County. See our residential appraisal services, or contact us with both reports and the disclosure deadline.

Family law attorney interviewing an appraiser before choosing an expert witness appraiser for a divorce case
12 Questions to Ask Before You Hire an Expert Witness Appraiser

Most family law attorneys meet their appraiser twice. Once on the phone, and again at the deposition. But the deposition is the wrong place to learn who you hired. Choosing expert witness appraisers takes a real interview, not a quote request, because the person who signs the report is the person opposing counsel will cross-examine. Here are the questions worth asking first, and what a good answer sounds like.

By the end of this article, you’ll know:

  • The twelve questions to ask before you retain an appraiser for a contested case.
  • How to verify a license, a designation, and disciplinary history yourself.
  • Which answers should end the interview on the spot.

Choosing Expert Witness Appraisers Before the Disclosure Clock Runs

Timing shapes every other choice. Under Illinois Supreme Court Rule 218, the court sets witness disclosure dates at case management. Those dates must let discovery close at least 60 days before the expected trial date, unless the parties agree otherwise. The committee comment also goes further. It says opinion witnesses should be disclosed early enough to be deposed before that 60-day line. Local rules and the case management order control the details, so check both.

An appraiser retained a month before disclosure has a month to inspect, research, write, and answer your questions. In practice, that rarely goes well. We covered what makes the report itself hold up in our article on what makes an appraisal defensible on the witness stand. This one is about the person behind the report instead.

Credentials and Competency: Questions 1 to 4

  1. What credential do you hold, and in which states? The federal system recognizes three levels: State Licensed, Certified Residential, and Certified General. Trainees, however, don’t appear on the federal registry and can’t independently appraise for federally related work.
  2. Can I confirm that myself? Yes, and you should. The Appraisal Subcommittee’s National Registry is searchable by name and state. It also shows active discipline that limits an appraiser’s work, such as a revocation or suspension. For resolved or older matters, call the state licensing agency.
  3. Do you hold a professional designation? The Appraisal Institute awards the MAI for all property types and the SRA for residential work. Its online directory also lets you confirm a designation by name. A designation isn’t a license, and a license isn’t a designation, so check both.
  4. How many properties like this one have you appraised in this market? A Kenilworth estate, a Pilsen three-flat, and a strip center held in an LLC are three different assignments. So ask for a rough count over the last three years and the price range. A vague answer here matters more than a thin resume.

Testimony and Independence: Questions 5 to 9

  1. How many times have you testified, and where? Separate depositions from trials, and ask which courts and case types. Then request case names, subject to confidentiality, so you can pull transcripts if you want them.
  2. Has any court excluded or limited your testimony? A yes isn’t automatically disqualifying. But a yes the appraiser didn’t volunteer usually is.
  3. Have you worked on this property, or for either spouse, before? A refinance appraisal from two years ago, or a friendship with the other side, becomes a cross-examination theme. You want to hear about it now, not at the deposition.
  4. Who hires you in family cases? An appraiser retained only by one side of the bar hands opposing counsel an easy story about bias. Work for petitioners, respondents, and joint engagements reads as independence instead.
  5. How is your fee set? Expect a fixed report fee plus hourly rates for preparation, deposition, and trial. USPAP’s Ethics Rule bars compensation that depends on the value reached or on a result that favors the client. So any hint of a fee tied to the number ends the conversation.

The Report and the File: Questions 10 to 12

  1. Who inspects the property, and who signs the report? If an associate does the fieldwork, the signer still has to describe the house under oath. Find out how that handoff works before a deposition exposes it.
  2. What report format will you use, and can you value a past date? A lender form limits explanation by design. A narrative report written for litigation, by contrast, walks a judge from the data to the value. So it holds up better when the value is contested. If the court may use a date other than trial, confirm retrospective experience. Our article on the date of value in a divorce appraisal explains why that matters.
  3. Will you produce your workfile on request, and how fast? Opposing counsel will ask for it, often in the first deposition notice. An appraiser who hesitates now will hesitate under subpoena too.

Answers That Should End the Interview

Some answers are dealbreakers on their own. Watch for these, even when the rest of the interview goes well.

  • A value quoted, or hinted at, before anyone has inspected the property.
  • Any fee that depends on the number or on how the case turns out.
  • A license you can’t find on the National Registry, or an active suspension on it.
  • No testimony history, and no interest in preparing for cross.
  • Reluctance to share the workfile or to explain an adjustment in plain English.

That last one deserves a live test, because judges need the plain-English version. Ask the appraiser to walk you through one adjustment from a past report, redacted, as if you were the judge. If you’re lost after two minutes, the judge will be too.

For the CPA Coordinating the Valuation

Forensic accountants often build the appraiser shortlist, or inherit one counsel already picked. Either way, four questions belong in your own interview. First, can the appraiser value the property as of the same date as your business valuation or balance sheet? Second, will the report state its definition of value, so you can reconcile it with the standard you’re using? Third, if the real estate sits inside an entity, will the appraiser value the real property and leave interest-level adjustments to you? Finally, will you get the adjustment grid and comparables in a form you can cite in your schedules?

Then put those answers in the engagement letter. That way the two reports meet at the same date and the same definition, instead of colliding at trial.

Interview the Appraiser the Way Opposing Counsel Will

Opposing counsel will ask most of these questions eventually. Asking them first, before the report is ordered, costs you an hour. Skipping them, though, can cost you the valuation. So verify the credential yourself, test the testimony record, and pin down the fee and the date in writing. Then hire the person you’d be comfortable putting on the stand.

Vetting an Appraiser Before Disclosure?

Put PahRoo through the same twelve questions. Michael Hobbs, MAI, SRA, signs our litigation reports and testifies to them, and we’ll answer every question before you retain us.

Schedule an Expert Consult

Frequently Asked Questions

What should you ask an expert witness appraiser?

Start with credentials: license level and states, any Appraisal Institute designation, and experience with the property type. Then ask about testimony history, any exclusion, prior work for either party, how the fee is set, who inspects and signs, and whether the workfile will be produced on request.

What is an MAI or SRA designation?

Both are awarded by the Appraisal Institute. The MAI covers all property types, including commercial and residential. The SRA covers residential property. Each requires education and experience beyond a state license, and holders agree to the Institute’s ethics and standards.

When should you hire an appraisal expert?

As soon as value is contested. In Illinois, Rule 218 has the court set witness disclosure dates so discovery ends at least 60 days before trial, unless the parties agree otherwise. The appraiser needs time to inspect, research, write, and be deposed inside that window.

How much does an expert witness appraiser cost?

It depends on the property, the report type, and how much testimony the case needs. Most engagements pair a report fee with hourly rates for preparation, deposition, and trial. Get both in writing, and confirm nothing depends on the value reached.

How do I check an appraiser’s license?

Search the Appraisal Subcommittee’s National Registry by name and state. It lists the credential level and any active discipline limiting the appraiser’s work. For past or resolved matters, contact the state licensing agency.

Expert Witness Appraisal for Family Law Counsel

If you’re building a shortlist, start with our residential appraisal services page, which covers divorce work across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, signs PahRoo’s litigation reports and is available for deposition and trial. For a contested estate home, see our guide to appraising luxury homes in high-asset divorce, or contact us with the case caption and the disclosure deadline.

Divorce attorney and expert witness appraiser reviewing a defensible appraisal report before trial
What Makes an Appraisal Defensible on the Witness Stand

Consider a hypothetical Oak Park two-flat in a contested divorce. One appraiser says $1,150,000. The other says $960,000. The judge has to pick, and in Illinois the judge has to explain the pick in writing. What decides it is rarely the number. It is which appraiser can still explain the number after an hour of cross-examination. That is what a defensible appraisal expert witness delivers. It is a different product from a lender appraisal.

By the end of this article, you’ll know:

  • What Illinois and federal courts test when an appraiser takes the stand
  • Where reports break under cross-examination, and how to spot weak ones early
  • What to check before you retain, and what the CPA on the case needs

What Defensible Appraisal Expert Witness Testimony Rests On

Under Illinois Rule of Evidence 702, an expert may testify when specialized knowledge will assist the trier of fact. The rule’s committee comment confirms Illinois is a Frye state. But the general-acceptance burden only applies when the opinion rests on a new or novel scientific methodology. The sales comparison, cost, and income approaches are not novel. So in a Cook County divorce, the fight over an appraiser is rarely about admissibility. It is about weight and credibility.

Federal court is stricter on paper. Under Federal Rule of Evidence 702, the proponent must show four things are more likely than not. The testimony helps the court, rests on sufficient facts or data, uses reliable methods, and applies them reliably. That is the Daubert framework. The committee notes add that valuation opinions get judged by the standards of the appraisal field itself. In practice, opposing counsel in state court borrows the same four questions on cross. Was the appraiser qualified? Is the data sufficient? Does the method have standing in the field? Did the appraiser apply it correctly?

Which standard governs is counsel’s call. What an appraiser controls is whether the report answers all four before anyone asks. Our overview of appraisals in divorce proceedings covers the basics. Below is what changes when testimony is likely.

Where Appraisal Reports Break Under Cross-Examination

The attacks are predictable, because they work. The first is the date. A refinance appraisal carries the lender’s effective date and intended use. In a divorce it answers a question the court did not ask. Under 750 ILCS 5/503, the court applies fair market value as of the trial date or another date it sets. The wrong date sinks a report before the comparables come up. Our article on the date of value in a divorce appraisal explains how that date gets chosen.

The second is verification. Did the appraiser confirm each sale, or lift it from the MLS? Did anyone drive past the comps? An appraiser who cannot describe the confirmation loses that comparable in front of the judge.

The third is adjustment support, and this is where most reports fail. The Colorado Division of Real Estate names four: boilerplate that claims paired sales or regression support but shows no analysis, predetermined adjustments reused from file to file, cost figures treated as market reaction, and averages standing in for real comparisons. Each is one question from collapsing on the stand.

The fourth is the file. USPAP requires a workfile holding all data behind the conclusions, including data considered and not used, plus summaries or transcripts of any testimony. Illinois Rule of Evidence 705 lets cross-examining counsel demand the underlying facts. A thin workfile means a thin opinion, and everyone in the room finds out at once.

Then comes the appraiser. An expert who argues the client’s side, moves the number after a phone call, or forgets a prior report on the same property has written the other side’s closing. Independence, after all, is the whole basis for weight.

What a Defensible Report Looks Like on the Page

USPAP, published by The Appraisal Foundation and authorized by Congress in 1989, is the recognized standard for U.S. appraisers. It requires the appraiser to identify the problem before solving it. That means naming the client and intended users, the intended use, the type and definition of value, the effective date, the property’s relevant characteristics, and any assignment conditions. A court-ready report states each on its first pages, and each matches the case.

From there, the report shows its work. Every adjustment ties back to evidence the reader can check: a paired sale, a bracketed range, a documented buyer interview, or a regression. The reconciliation then says which approach carried the weight and why. Extraordinary assumptions, such as an interior the appraiser could not access, appear up front. And the report discloses what research the appraiser did and did not do, as USPAP’s reporting standard requires.

Format matters too. A lender form limits explanation by design. A narrative report written for litigation walks a judge from the data to the number. It is one reason a divorce appraisal and a price opinion land so differently in court.

What Attorneys Should Check Before the Report Is Ordered

Disclosure shapes the retention. Under Illinois Supreme Court Rule 213(f)(3), a retained appraiser is a controlled expert. On interrogatory you must disclose the subject matter, the opinions and their bases, the qualifications, and any reports. Rule 213(g) then limits direct examination to those disclosures. So the report becomes an exhibit the day the appraiser signs it, and the number cannot drift at trial. Retain early, then, not late.

Vet the witness first. Ask how many times the appraiser has testified at deposition and at trial. Find out whether any court has excluded or limited that testimony. Ask whether they have worked for both husbands and wives, because a one-sided record is a cross-examination theme. Designations matter too; the MAI and SRA require experience beyond a state license. And ask whether they will produce the workfile without a fight.

Then scope the engagement in writing. Name the effective date, or two dates if the case needs a current and a retrospective value, as a quitclaim transfer mid-case often does. State the intended use as the dissolution proceeding. If the appraisal is joint, name both counsel as intended users. Confirm a fixed fee with no tie to the outcome. Confirm a full inspection, which matters most on an estate home with custom features. Our guide to disputed property value in an Illinois divorce lists the records to gather first.

The statute adds one more path. Under 503(l), the court may consult its own financial expert, who is subject to examination and cross-examination too.

For the CPA on the Case

Accountants in a divorce carry the real estate value into the marital balance sheet, the tracing schedule, or a business valuation. If the appraisal falls, those schedules fall with it. Four checks protect your work.

First, match the effective dates. If the business valuation is as of December 31 and the house is as of a May inspection, the balance sheet mixes two markets. So get the appraisal to the same date, or document the bridge. Second, match the definition of value. Section 503(k) calls for fair market value. A lender’s market value definition, or a fair value standard in a business valuation, may not line up. Third, check the arithmetic in the adjustment grid before the number lands in your schedule. The appraiser’s addition error becomes your error on the exhibit. Fourth, if rental property sits inside a business you are valuing, agree with the appraiser in writing on who values the real estate and who values the enterprise. Otherwise the same rent counts twice or not at all.

Keep the appraisal in your permanent file too. The Supreme Court’s standard matrimonial interrogatories ask each party about appraisals from the prior three years and about any net worth statements prepared for them. Whatever you build on the appraisal gets disclosed, so read the report first.

Retain the Witness Before You Order the Report

Sequence is what makes the report defensible. Choose the appraiser you would put on the stand, then order the report from that person. Fix the effective date and intended use in the engagement letter. Get the report early enough to read it, question it, and let the appraiser fix anything that will not hold. A report produced the week before disclosure draws the hardest cross. One built for testimony from the first page usually settles the value question before anyone reaches the courtroom.

Is Your Appraiser Ready for Cross-Examination?

PahRoo prepares litigation appraisals built for Rule 213 disclosure, deposition, and trial. Michael Hobbs, MAI, SRA, signs the report and takes the stand to defend it in Cook County and across our other markets.

Retain an Appraisal Expert Witness

Frequently Asked Questions

What makes an appraisal defensible in court?

It states an effective date, intended use, and definition of value that match the case, uses comparable sales the appraiser verified, supports every adjustment with market evidence, explains which approach carried the weight, and rests on a complete workfile. Then the appraiser explains each choice under cross-examination without changing the number.

Can an appraiser be an expert witness?

Yes. Under Illinois and federal Rule 702, a witness qualified by knowledge, skill, experience, training, or education may give opinion testimony that helps the court. A licensed appraiser with experience in the property type and market generally qualifies. Weight depends on the method and the support behind it.

What happens during appraiser cross-examination?

Opposing counsel tests the effective date and intended use, comparable verification, the evidence behind every adjustment, the workfile, the appraiser’s qualifications and testimony history, and any prior reports on the property. Illinois Rule of Evidence 705 lets counsel demand the underlying facts and data.

What is a Frye or Daubert challenge?

Both ask a judge to exclude expert testimony. Illinois follows Frye, which requires general acceptance only when an opinion rests on a new or novel scientific methodology. Federal courts follow Daubert, which requires sufficient data and reliable, reliably applied methods. Standard appraisal methods are rarely excluded, so most challenges go to weight.

How do you choose an expert appraiser for a divorce?

Look for experience with the property type and price tier, deposition and trial testimony that no court has excluded, work for both sides of prior disputes, an Appraisal Institute designation such as the MAI or SRA, and a willingness to produce the workfile. Then fix the effective date, intended use, and fee in the engagement letter.

Litigation Appraisal and Testimony From One Appraiser

Family law attorneys and forensic accountants across Cook County and the wider Chicago area, along with Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, bring PahRoo Appraisal & Consultancy into contested cases. Since 1999 the firm has prepared appraisals for dissolution, estate, and tax matters, and Michael Hobbs, MAI, SRA, signs every report and is available for deposition and trial. See our residential appraisal services, or contact us with the case caption and the disclosure deadline.


Attorney reviewing a luxury home appraisal report in a high-asset divorce case
Appraising Luxury and Estate Homes in High-Asset Divorce

In a high-asset case, the house is rarely just a house. It might be a 9,000-square-foot estate in Winnetka with a coach house, or a full-floor Gold Coast condominium. The luxury home appraisal divorce counsel puts in front of the court has to survive three readers. An opposing expert, a skeptical judge, and a spouse who is sure the number is wrong. Reports built for lending were never designed for that.

By the end of this article, you’ll know:

  • Why estate and luxury homes are harder to value, and what a defensible method looks like
  • How appraisers find and adjust comparable sales when almost nothing matches
  • What to ask before you retain the appraiser, and how a broker can strengthen the file

What Makes a Luxury Home Appraisal Divorce-Ready

Three things separate a high-value home from the typical marital residence, and each adds risk to the final number. First, the buyer pool is thin. A property at the top of the Kenilworth market competes for a small group of qualified buyers. Second, the features are bespoke. No two estates share the same wine cellar, the same lot, or the same view. Third, the sales data is sparse. A submarket can produce only a handful of closings above a given price in a year.

Illinois law raises the stakes. Under 750 ILCS 5/503, the court must make specific factual findings on the value of each asset. It applies a fair market value standard. And it values the property as of the trial date, or another date the court sets. So the appraisal cannot hedge. It has to state a number, tie it to a date, and show the evidence.

That is where standards come in. The Uniform Standards of Professional Appraisal Practice, published by The Appraisal Foundation, govern how the analysis is developed and reported. A report that follows them names the effective date, explains the scope of work, and supports every adjustment. One that skips those steps hands opposing counsel a script. Our overview of appraisals in divorce proceedings covers the basics. Below is what changes at the top of the market.

Why Few Comparable Sales Is Not an Excuse

Attorneys often hear that there are no comps. In practice that means the appraiser has to work harder. The search widens in three directions.

Geography comes first. A Lake Forest estate may compete with Winnetka, Glencoe, and Barrington Hills rather than the next street over. The buyer choosing among them is the same buyer. The same logic holds in our other markets. A Highland Park buyer in Dallas may also be looking in University Park. Main Line buyers in Philadelphia shop across several townships. A Port Royal buyer in Naples is often weighing Aqualane Shores too. The appraiser then makes a supported location adjustment instead of pretending the sales are next door.

Time comes second. A luxury sale from 18 months ago can still be useful. But the appraiser has to adjust for market movement between that closing and the effective date. That adjustment needs evidence, such as repeat sales or price trends in the same tier, not a guess.

Then the appraiser brackets. Ideally one comparable is superior to the subject and one is inferior. Then the value falls inside a range the market actually produced. Paired sales analysis, where two similar sales differ mainly in one feature, is how the size of an adjustment gets tested. When the paired data is thin, the cost approach steps in as a check. It adds land value from vacant or teardown sales to the depreciated cost of the improvements. It rarely drives the number on an older estate, but it exposes an inflated sales comparison quickly.

Bespoke Features and the Superadequacy Problem

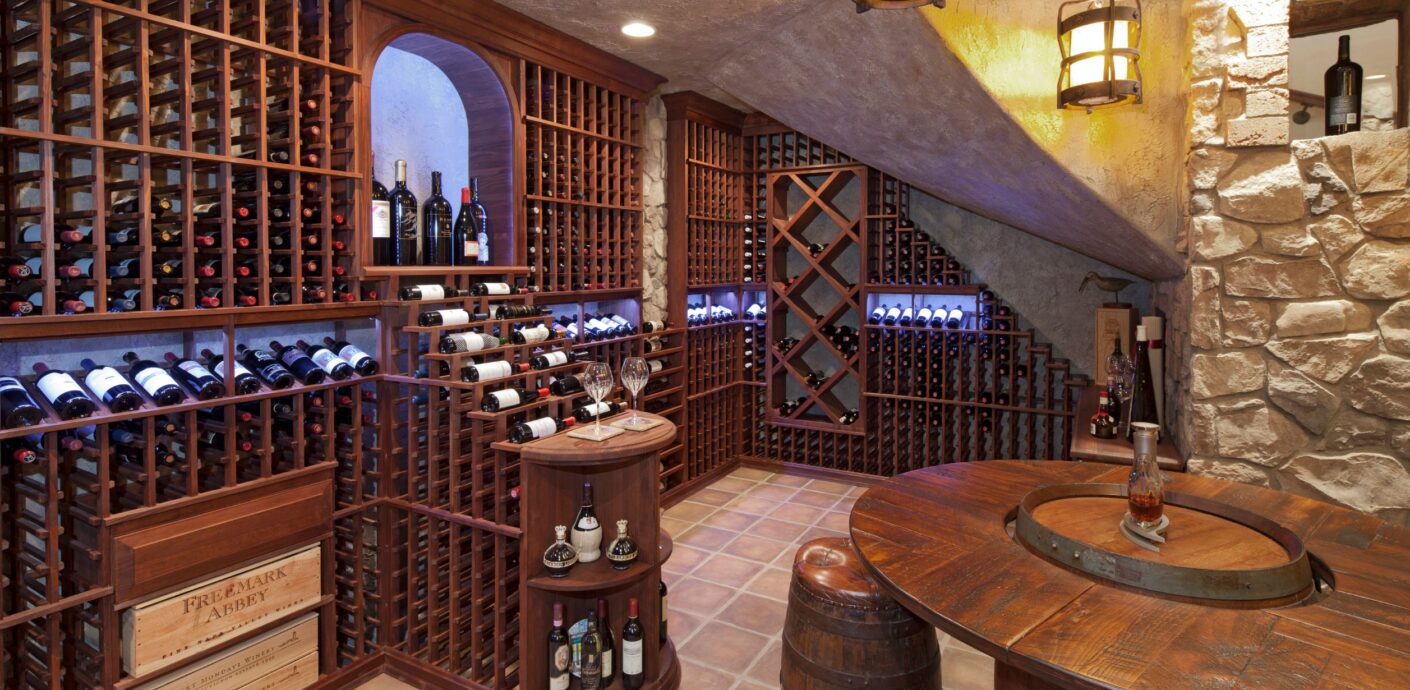
Custom features are where luxury appraisals go wrong most often. An owner who spent $180,000 on a wine cellar expects to see $180,000 in the value. The market usually disagrees.

Appraisers call the excess a superadequacy. The Dictionary of Real Estate Appraisal defines it as an excess in the capacity or quality of a structure or component, judged by market standards. It is a form of functional obsolescence, and it shows up in luxury homes more than anywhere else. The more unusual the feature, the smaller the pool of buyers who will pay for it.

Consider a hypothetical estate in Hinsdale with that $180,000 cellar. Suppose paired sales in the tier show buyers paying roughly $60,000 more for a home with a serious cellar. Then the contributory value is $60,000. The other $120,000 was consumed, not invested. The same math applies to indoor pools, sport courts, elevators, and eight-car garages. The report should state what each feature contributes and show how that figure was derived.

A prior lending appraisal from a refinance is useful here but not decisive. It was written for a different purpose, often on a form that limits explanation. Counsel should still request it, as our guide to disputed property value in Illinois divorce explains. Then expect the litigation appraisal to go well beyond it.

Who Should Appraise an Estate Home in a Divorce

Not every licensed appraiser should take this assignment, and USPAP says so. The Competency Rule requires an appraiser to determine, before agreeing to an assignment, that they can perform it competently. Competency covers the property type, the market, and the intended use. A residential appraiser who works mainly on $500,000 lender assignments may be fully licensed. That same appraiser can still be outside their competence on a $6 million estate headed to trial.

Ask four questions before you retain. How many properties above the relevant price point has the appraiser valued in this submarket in the last three years? Which designation do they hold? The Appraisal Institute awards the MAI for all types of real property and the SRA for residential work. Both require demonstrated experience beyond a state license. Have they testified, and how did the report hold up? And can they support the date of value the case needs, including a retrospective date if the court sets one? Our article on the date of value in a divorce appraisal explains why that last question matters.

Then plan for disclosure. Illinois Supreme Court Rule 213(f)(3) requires a party, on interrogatory, to disclose a controlled expert’s opinions, their bases, qualifications, and reports. A luxury appraisal built to be disclosed reads differently from one built to close a loan. The reasoning is on the page, the comparables can be verified, and the appraiser’s file is ready for deposition.

What Brokers Can Bring to the Appraisal

Luxury brokers hold data the MLS lacks. Off-market sales, buyer feedback on specific features, and the real reason a listing sat for months rarely reach a public record. In a divorce, that knowledge can make or break the comparable analysis.

If you have listed or sold in the subject’s tier, this is what helps the appraiser most. Send the full listing history for the subject, including expired and canceled listings. Prior exposure to the market is evidence of what buyers would not pay. Share any private sales you can verify with a closed price and date. Pass along showing feedback on features the appraiser has to value, such as the indoor pool nobody wanted or the view everyone mentioned. And be candid about concessions and seller credits. A recorded price with, say, $150,000 in credits behind it is not the price the comparable grid should carry.

Brokers also benefit on the back end. If the settlement leads to a sale, a court-ready appraisal gives you a defensible list price. It also protects your own price opinion. A broker price opinion serves a listing decision, but it is not the standard courts apply to a contested value. Our comparison of a divorce home appraisal and a price opinion explains why.

Put the Estate Home’s Value on the Record Early

High-asset cases move slowly, but expert deadlines do not. Retain the appraiser as soon as the property is identified as contested. Agree the effective date with opposing counsel if you can. Then give the appraiser access to the whole property, not a walkthrough of the main floor. If a buyout is on the table, the same report anchors the equity math, as our marital home buyout guide shows. The goal is one number, built on evidence a judge can follow, delivered in time to use it.

Is the Estate Home the Largest Asset in the Case?

PahRoo appraises luxury and estate homes for divorce counsel in Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, with comparables you can verify and an appraiser who will defend the work on the stand.

Order a Luxury Home Appraisal

Frequently Asked Questions

How is a luxury home appraised in a divorce?

The appraiser inspects the whole property, identifies the competing luxury submarkets, and analyzes comparable sales adjusted for location, time, size, and features. Paired sales and the cost approach test the adjustments. The report ties the value to the effective date the court uses and explains every step so it can be defended in testimony.

Why do luxury home appraisals vary so widely?

Thin sales data and custom features leave more room for judgment. Two appraisers may select different comparables, adjust for a feature differently, or treat a costly improvement as full value when the market pays a fraction. A wide gap usually signals weak support in one report rather than a market that cannot be measured.

How do you find comps for a unique home?

Widen the search to the submarkets the same buyer would consider, extend the time frame with a supported market adjustment, and bracket the subject with a superior and an inferior sale. Verified off-market sales, often known to luxury brokers, can fill gaps the MLS leaves.

Who should appraise an estate home in a divorce?

An appraiser with documented experience in the property type and price tier, ideally holding an Appraisal Institute designation such as the MAI or SRA, who has testified and can support the effective date the case requires. USPAP’s Competency Rule puts the burden on the appraiser to confirm this before accepting the work.

Do custom features add their full cost to the appraised value?

Rarely. A feature contributes what buyers in that market will pay for it, which is often less than it cost to build. The excess is called a superadequacy. The appraisal should state each feature’s contributory value and show the market evidence behind it.

Independent Valuation for High-Asset Divorce Cases

Since 1999, PahRoo Appraisal & Consultancy has valued estate homes, luxury condominiums, and complex residential property across Cook County and the wider Chicago area, along with Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, signs every report and is available for testimony. See our residential appraisal services, or contact us to discuss a high-value property.


Signed quitclaim deed on a desk, the kind of divorce transfer an appraiser values at the transfer date
Quitclaim Deed Divorce Transfers and What Appraisers See

A quitclaim deed takes five minutes to sign and a few days to record. In a divorce, that speed is the problem. A quitclaim deed divorce transfer can move a house, a rental building, or a vacant lot to a relative or a new LLC. It can happen before the other spouse knows the marriage is ending. When that happens, the attorney’s first question is usually about the law. My first question is about the date. Everything the court eventually weighs depends on what the property was worth the day it changed hands.

By the end of this article, you’ll know:

  • What a quitclaim deed does, and why it shows up in divorce files
  • The specific things an appraiser checks when a property was transferred mid-case
  • How a transfer-date appraisal gives counsel a number to argue from

What a Quitclaim Deed Divorce Transfer Actually Does

A quitclaim deed conveys whatever interest the signer holds in a property, with no promise that the interest is any good. It is the simplest deed there is. Spouses use it every day for legitimate reasons. Most often, one spouse keeps the house after a marital home buyout and the other signs off.

The trouble starts when the deed runs the other direction, away from the marital estate. A spouse signs the family’s two-flat over to a sibling for ten dollars. A vacant lot moves into a newly formed LLC. Title to a lake house lands with an adult child from a first marriage. On paper the property is gone. In the market, nothing about the property changed that day except the name on title.

That gap is where an appraiser earns a fee. The Illinois Uniform Fraudulent Transfer Act treats real estate as transferred once the conveyance is perfected. It then measures the remedy against the asset’s value at the time of the transfer. Whether that Act, the dissipation rules in the divorce statute, or some other theory applies is the attorney’s call. Each one, though, turns on the same fact: what the property was worth on the transfer date.

Why the Transfer Date Becomes the Effective Date

In most divorce appraisals the court or the parties set the effective date, and it is often the trial date. We covered that choice in our piece on the date of value in a divorce appraisal. A transferred property breaks the pattern. The question is no longer what the house is worth today. It is what walked out of the estate, and when.

So the appraisal is retrospective. I value the property as of the deed’s signing or recording date, using only sales and market conditions that existed then. Sometimes the case also needs a current value, because the court may order the property returned or its value charged against the transferring spouse. That is a second effective date and a second analysis. Ordering both at once costs less than ordering the second one later.

Under USPAP, a retrospective value has to rest on information a market participant could have known as of the effective date. A sale that closed two months after the deed cannot support the value at the deed. Counsel should expect the report to say so plainly.

What an Appraiser Looks For in a Mid-Divorce Transfer

The deed itself is the first exhibit. I read the recorded instrument, not a summary, because the details matter. The grantee’s name tells me whether the property went to an insider: a relative, a business the spouse controls, a close friend. The stated consideration, along with the transfer tax declaration or exemption stamp attached to it, tells me what value reached the county’s records. A deed reciting ten dollars for a $600,000 two-flat is not evidence of value. It is evidence that value was not exchanged.

Then I look at what happened after the transfer. Who is living in the property? Who collects the rent and pays the taxes and insurance? If the transferring spouse still holds the keys and the bank account, the deed changed the name on title and little else. That pattern, retained possession after a transfer to an insider for nominal consideration, appears on the statute’s own list of factors a court may consider. I do not decide whether it is fraud. I do document it, because those facts sit inside the appraisal’s scope.

The property’s condition on the effective date matters too. Photos from a prior listing, a refinance appraisal, permit history, or the other spouse’s recollection all help reconstruct what the building looked like that day. They also show whether the deed came before or after a major repair, a fire, or a new roof.

Lenders meet the same deed from the other side. When one spouse tries to refinance the marital home to fund a buyout, a recent quitclaim to a relative or an LLC surfaces in the title search. Underwriting stalls until the ownership question is settled. A transfer-date appraisal already in the file answers the value half of that question before the loan officer has to ask.

Finally, I check the encumbrances. A property quitclaimed subject to a mortgage moves equity, not the whole value. The report separates the market value of the real estate from the debt against it. That way the attorney sees the actual dollars that left the estate. The same records we recommend in our guide to disputed property value in an Illinois divorce do double duty here.

Reconstructing the Market at the Transfer Date

A retrospective analysis takes more work than a current one, and the reasons are practical. Comparable sales have to reflect the record as it stood then, before later sales and later price movement crept in. Interest rates and inventory as of that date, not today’s, frame the adjustments. When the transfer happened years earlier, archived MLS records, county records, and old listing photos become the evidence base.

The result is a value the court can hold up against the consideration on the deed. A $600,000 building conveyed for ten dollars to a brother-in-law tells its own story once the number is on the table. So does a building conveyed for $580,000 to an unrelated buyer. That one looks like a real sale at a modest discount rather than a stripped asset. The appraisal does not argue the point. It removes the guesswork about the size of the gap.

Where the Appraiser Stops and the Attorney Starts

I establish value at the date the case needs. I document the facts around the transfer that fall within an appraiser’s competence. And I stand behind the report on the witness stand. Whether the deed was fraudulent, dissipative, or voidable, and what remedy the court should order, is legal characterization. That belongs to counsel and the judge. A report that wanders into it loses credibility fast, and opposing counsel will notice.

The same goes for reversing a transfer. Courts have tools to unwind a bad conveyance or charge its value against the party who made it. Which tool fits is a legal question. The appraiser’s job is to make sure that whatever tool the court reaches for, the value it applies is the right one.

Order the Transfer-Date Appraisal Before Discovery Closes

When a transferred property surfaces in a case, pull the recorded deed and the transfer declaration first. Confirm the exact date. Decide with the appraiser whether the case needs one effective date or two. Then order the retrospective appraisal early enough to disclose it with your expert designations. A value produced the week before trial draws the hardest attack. Fix the number to the date, and the rest of the argument has a foundation.

Did a Property Leave the Estate Before the Filing?

PahRoo prepares transfer-date and current-value appraisals for real estate quitclaimed before or during a divorce, documented for discovery and testimony.

Value the Transferred Property

Frequently Asked Questions

What is a quitclaim deed in a divorce?

A quitclaim deed transfers whatever ownership interest the signer holds in a property, with no guarantee of title. In divorce it is commonly used to move the marital home to the spouse who keeps it after settlement. Before or during the case, it can also shift property out of the marital estate to a relative or an entity.

Can a spouse transfer property before a divorce?

A spouse can sign and record a deed, but that does not settle whether the transfer holds up. Courts can examine transfers made in anticipation of divorce, and Illinois law allows dissipation and fraudulent transfer claims in the right circumstances. Whether a given transfer is open to challenge is a legal question for the attorney.

How is a transferred home valued in a divorce?

With a retrospective appraisal. The appraiser sets the effective date at the date of the deed. The value then rests only on sales and market conditions that existed at that time. If the court may also need a current value, the same assignment carries a second effective date.

Is a pre-divorce property transfer reversible?

Sometimes. Courts have remedies that can unwind a transfer or charge its value against the spouse who made it. Fraudulent transfer law provides its own relief. Which remedy applies, and whether one applies at all, depends on the facts and the attorney’s argument. The appraisal supplies the value that sets the size of the remedy.

What is a fraudulent conveyance?

In general terms, a transfer made to hinder, delay, or defraud a creditor. It also covers a transfer made without reasonably equivalent value while the transferor was in financial trouble. Illinois codifies this in the Uniform Fraudulent Transfer Act. Deciding whether a specific deed meets that definition is the court’s job, informed by counsel and by the appraised value at the transfer date.

Appraisal Support When a Deed Changes Hands Mid-Case

Attorneys across Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples bring PahRoo Appraisal & Consultancy into cases where a property changed hands at the wrong moment. Our MAI and SRA designated team prepares retrospective and current-value divorce appraisals built for discovery and cross examination. Start with our overview of appraisals in divorce proceedings, review our residential appraisal services, or contact us with the recorded deed in hand.

A family home with two parties reviewing documents, weighing a marital home buyout.
Marital Home Buyout: How an Appraisal Sets a Number Both Sides Can Trust

A marital home buyout looks simple from the outside. One spouse keeps the house, pays the other for their share, and everyone moves on. The hard part is the number. Get it wrong and the deal falls apart or a lender walks. A marital home buyout appraisal fixes that number to defensible market value, which is why both sides, and the bank behind the refinance, tend to start there.

By the end of this article, you’ll know:

  • How a buyout figure is actually calculated
  • Why the lender needs an independent appraisal
  • What can shift the number, and who usually pays for the report

What a Marital Home Buyout Appraisal Does

A buyout appraisal is an independent opinion of the home’s current market value, prepared by a licensed or certified appraiser. That value is the anchor. Everything else in the buyout, the equity, each spouse’s share, the size of the refinance, builds off it.

Bankers care because the buyout usually runs through a refinance. The new loan pays off the old mortgage and funds the cash going to the departing spouse. The appraised value sets the loan-to-value, so it decides whether the deal is even financeable. Attorneys care because that same number has to hold up in the settlement.

How the Buyout Is Calculated

The math is short once you have a credible value. Here is the sequence most buyouts follow:

  1. Start with the appraised market value. This comes from the independent appraisal, not a listing estimate.
  2. Subtract the mortgage payoff and any liens against the property. What remains is the net equity.
  3. Subtract agreed costs, if the court allows them. Some settlements deduct estimated costs of sale, others do not.
  4. Split the net equity per the settlement. Illinois divides marital property in just proportions, which is not always a 50/50 cut.
  5. Pay the departing spouse their share. The spouse keeping the home funds it, usually through a refinance.

In short form: buyout amount equals appraised value, minus the mortgage payoff, times the departing spouse’s equity share. Under 750 ILCS 5/503, that share reflects what the court finds equitable, so the split is a legal decision while the value is an appraisal one.

Why Buyouts Are So Common Right Now

Rates are the reason. The 30-year fixed has held in the mid-6% range through 2026, according to Freddie Mac, well above the lows many couples locked in a few years ago. Selling the home and each buying again means trading a cheap mortgage for an expensive one, twice.

So keeping the house through a buyout often beats selling. That makes the appraised value the pivot point of the whole settlement. If the number is soft, the departing spouse feels shortchanged. If it is inflated, the refinance may not appraise out, and the deal stalls.

What Can Move the Number

Condition, recent sales, and the effective date all matter. A home that has been neglected during a long separation may appraise lower than either spouse expects. A fast-moving local market can shift the value between the offer and the closing. So a buyout appraisal is a snapshot tied to one date, and a stale one invites a challenge.

This is where a defensible report earns its fee. The appraiser documents the comparable sales and the reasoning, so the number survives a skeptical spouse, an opposing attorney, or a lender’s review.

Start the Buyout With a Real Value

Order the appraisal before the negotiation hardens, not after. Confirm the appraiser is licensed, works to recognized standards, and can support the effective date the case needs. Then build the buyout off that figure. It is far easier to agree on a split when nobody is arguing about the value underneath it.

Need a Buyout Number That Holds Up?

PahRoo prepares independent, USPAP-compliant appraisals that set a defensible buyout figure for the settlement and the refinance behind it.

Order a Buyout Appraisal

Frequently Asked Questions

How is a house buyout calculated in a divorce?

Start with the appraised market value, subtract the mortgage payoff and any liens to get net equity, then split that equity per the settlement. The spouse keeping the home pays the departing spouse their share, usually funded by a refinance. The appraisal sets the starting number the whole calculation rests on.

Do you need an appraisal for a marital home buyout?

In most cases, yes. A buyout needs a defensible market value, and if a refinance funds it, the lender requires an appraisal anyway. An informal estimate can work only when neither spouse contests the value and no lender is involved, which is rare in a real buyout.

Who pays for the buyout appraisal?

It varies. The spouses often split the fee, the party who orders it pays, or the court allocates the cost. Many couples share one neutral appraisal rather than commissioning two competing reports, which saves money and avoids a battle over whose number is right.

How long is a buyout appraisal valid?

There is no fixed expiration, but the value is tied to a specific effective date. Lenders and courts generally want a recent appraisal, often within the last few months. In a moving market, an older figure gets questioned, so timing the report close to the buyout matters.

Can one spouse force the sale of the home?

That is a legal question for the court, not the appraiser. A court can order the home sold if an equitable division requires it, or it can approve a buyout that lets one spouse keep the house. Either way, the appraisal supplies the market value the decision runs on.

Need an Independent Buyout Appraisal?

PahRoo Appraisal & Consultancy prepares buyout and divorce valuations across Cook County and the wider Chicago area. For more on how we support attorneys, lenders, and their clients, see our residential appraisal services and our overview of appraisals in divorce proceedings, or contact us to order a buyout appraisal.

NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712