Tag: Chicago real estate appraisal

Request a quote

Our blog

Latest news
& events

Property condition concerns identified during home appraisal inspection
Pest Infestations and What an Appraisal Must Say

The fleas started jumping before our appraiser finished the first floor. Roaches were visible in more than one room. Pest infestations at that level stop being a line in the condition section. They become a question about whether the inspection can safely finish.

By the end of this article, you’ll know:

  • What an appraisal report has to say when the appraiser sees evidence of infestation
  • When a lender can still close as is, and when the report goes subject to
  • What the Illinois disclosure form asks sellers about pests, and what it leaves out

What Pest Infestations Do to an Appraisal

Start with what the appraiser is and is not. An appraiser is not a pest inspector. Nobody on our side diagnoses an infestation, prices a treatment, or certifies that a house is clear.

The reporting duty is narrower than that, and firmer. Fannie Mae’s Selling Guide says an inspection covers the accessible areas of a property. Appraisers carry no responsibility for hidden or unapparent conditions. But the report must reflect adverse conditions that were apparent during the visit. Detrimental conditions get reported even when they are typical for competing properties nearby (Selling Guide B4-1.3-06).

So the first question after a bad walkthrough is not what this costs the value. It is what the report now has to say, and who reads it next.

Where a Condition Note Turns Into a Loan Problem

The guide has a short section titled Infestation, Dampness, or Settlement. That is the one that actually bites. When an appraisal shows evidence of infestation, the report must comment on the effect on value and on marketability.

The lender then has two ways to clear the file. One is satisfactory evidence that someone corrected the condition. The other is a professionally prepared report, based on an inspection, saying the condition poses no threat of structural damage. The appraisal itself should go subject to repairs, or subject to an inspection by a qualified professional.

Severity sets the path. Condition ratings run C1 through C6. A C6 means defects severe enough to affect the safety, soundness, or structural integrity of the improvements. If any portion of the dwelling rates C6, the whole dwelling rates C6. That loan cannot go to Fannie Mae until the deficiencies come out at C5 or better.

Worth noticing whose example the guide reaches for: wood-boring insects. Termites eat structure. Roaches, fleas and rodents usually do not. Most of the time they land in the value and marketability comment instead. That comment is the part brokers underestimate, because it travels with the file.

What a Lender Should Ask For When the Report Flags Infestation

If you are the one clearing the condition, four things are worth checking before the file moves.

Read the condition rating before anything else. A C6 is a delivery stop, not a negotiating point. Then check whether the report came in as is or subject to. If subject to, find out which one the appraiser chose: repairs, or an inspection by a qualified professional. The two close differently.

When the file clears on an inspection report, read what the inspector actually addressed. The guide asks for a professional opinion that the condition poses no threat of structural damage. A treatment receipt and a scheduled follow-up visit are not that document, and a reviewer will notice.

Finally, read the marketability comment on its own rather than folded into the value discussion. The two can move in different directions. A house can treat clean and still sit. Asking an appraiser to clarify a comment is fine. Asking for a different number is not, and a good appraiser will decline.

What the Illinois Disclosure Form Asks, and What It Leaves Out

Illinois sellers fill out the Residential Real Property Disclosure Report at 765 ILCS 77/35. It runs 24 numbered statements. Two of them touch pests. Item 19 covers current infestations of termites or other wood boring insects. Item 20 covers a structural defect caused by a previous infestation of the same.

That is the whole list. No line for roaches. No line for rodents. No line for fleas.

The form still defines a material defect broadly. It covers a condition with a substantial adverse effect on value. It also covers one that would significantly impair the health or safety of future occupants. And it puts a continuing obligation on the seller to supplement the disclosure before closing. Whether a particular infestation meets that definition is a call for the seller’s attorney. Not for the appraiser, and not for the agent.

The practical move for a listing agent is simple enough. A missing checkbox is not a missing question. If a seller tells you about an active problem, get counsel in early. Three days before closing is too late to treat and document.

When the Inspection Itself Has to Stop

No assignment is worth a health risk. The appraiser makes that call on the spot. Leaving early protects the appraiser, but it also thins out the property observations. So the report has to disclose the limitation.

That disclosure travels. A reviewer sees it, the lender sees it, and most of the time it buys a second trip. In practice that is the expensive part of a pest problem. Not the value, the calendar. The return visit waits on treatment, and the report reconciles afterward.

One more thing an experienced appraiser watches for. Pests are usually a symptom. Standing water in a crawl space, a slow leak under a kitchen sink, a blocked floor drain in a basement. Reporting the roaches and skipping the water stain gets you half the story. The less useful half.

Clear the Condition Before the Report Locks It In

If you already know about a problem, deal with it before you order the appraisal. Treat the property, keep the invoice, and hand it over at the inspection. A documented cure gives the appraiser something concrete to report. It also gives the lender a clean way to close the condition out.

When the timing does not allow that, say so before the visit. A known condition someone raised openly reads very differently than one the appraiser found on arrival. Either way, the report will describe what was there. The only part you control is whether it also describes what you did about it.

Condition Problem Standing Between You and a Closing?

Tell us what the property looks like now. We will tell you what the report will have to say about it, and what your lender is likely to ask for next.

Request Your Appraisal

Frequently Asked Questions

Can a pest infestation lower a home appraisal?

Usually not on its own. The appraiser reports what is visible and comments on the effect on value and on marketability. A minor problem that someone already treated often changes neither. A severe one can move both, because buyers price in the cure and the uncertainty around it.

Do appraisers inspect for pests?

No. An appraiser is not a pest inspector and does not diagnose infestations or recommend treatment. The inspection covers the accessible areas of a property. The report then reflects adverse conditions that were apparent during the visit.

What does a subject to appraisal mean?

It means the value opinion rests on something happening first. That might be a specific repair, or an inspection by a qualified professional. Fannie Mae asks for that approach when an appraisal shows evidence of infestation, dampness, or abnormal settlement.

Does Illinois require a seller to disclose a pest problem?

The state disclosure report asks two pest questions. Both are limited to termites and other wood boring insects. Other infestations have no checkbox on the form. Whether one still counts as a material defect is a question for the seller’s attorney.

Should I treat the property before the appraisal?

When the timing allows, yes. Treating first and keeping the invoice gives the appraiser something to document. It also gives the lender a cleaner file. If treatment cannot happen first, tell the appraiser before the visit rather than after.

Appraisals That Document Condition Properly

PahRoo Appraisal & Consultancy works out of Lincolnwood and covers Chicago and Cook County, along with Dallas, Philadelphia, Phoenix and Naples. Michael Hobbs, MAI, SRA, signs every report. Our residential appraisal team handles condition-heavy assignments regularly. You can also read how a home appraisal runs from order to delivery, or see what our Chicago appraisal work covers.
Chicago residential appraisal market trends Week 18 across Cook, DuPage, Lake, and Will Counties
Chicago Residential Appraisal Market Trends: Week 18 Analysis
Chicago Housing Markets Are Moving in Different Directions

Chicago residential appraisal market trends for Week 18 show a clear split across the metro area. Cook and DuPage Counties are still showing strong seller-market momentum. Lake and Will Counties are showing more caution, with softer demand and rising supply pressure.

That matters for attorneys, lenders, accountants, brokers, and investors. A broad “Chicago market” view can miss what is really happening at the county level. Accurate real estate appraisals now need local market context, not general assumptions.

Cook County Remains the Strongest Seller Market

Cook County continues to lead the Chicago metro area in demand and pricing strength.

Single-family pending sales increased 10.2% from the prior week and 11.1% from last year. Active inventory fell 12.1% year-over-year, creating one of the tightest supply environments in the region.

Cook County also posted an absorbed-to-list ratio of 1.09x. In plain terms, many well-positioned homes are selling above asking price.

For professionals involved in lending, estate planning, divorce, property tax appeals, or pre-listing strategy, this kind of market requires careful appraisal support. Strong demand can move quickly, and pricing decisions need to be backed by current local data.

Cook County condos and townhomes also performed well. Pending sales rose 21.2% year-over-year while active inventory dropped 14.1%, showing continued buyer interest across multiple residential property types.

DuPage County Shows Strong Demand With Pricing Disconnects

DuPage County had some of the strongest demand growth in the Chicago area during Week 18.

Single-family pending sales rose 32.7% year-over-year. The absorption rate increased 39.1%, and months of supply tightened to 1.24 months. Those numbers point to a strong seller-market environment.

Still, one issue deserves attention.

DuPage reported an absorbed-to-list ratio of 0.76x. That means closed sales were much lower than current listing prices. This does not automatically mean the market is weakening. More likely, it shows a gap between higher-priced active listings and the mid-market homes that are actually closing.

For brokers, lenders, and attorneys, this is where appraisal judgment matters. Active listings alone may not tell the full story. Comparable sales, property class, buyer activity, and price range all need to be reviewed carefully.

DuPage condos also showed a sharp increase in absorbed prices during Week 18. Because condo transaction volume can be thinner, that jump may reflect the mix of properties that sold rather than a broad pricing shift.

Lake County Presents Mixed Market Signals

Lake County is currently one of the harder Chicago-area markets to read.

Several demand indicators weakened during Week 18. Pending sales declined 12.8% from the prior week. Inventory increased. Price reductions rose. Homes also took longer to sell.

At the same time, median absorbed prices moved sharply higher, rising 13.9% from the prior week and 21.3% from last year.

Those two signals do not line up neatly.

The likely explanation is that fewer homes sold overall, but the homes that did sell were concentrated in higher price ranges. That can lift the median absorbed price without proving that the entire market is gaining strength.

This matters in appraisal work. For estate matters, litigation, financing, portfolio reviews, and investment decisions, relying only on headline price growth can create risk. Lake County needs a closer look at the actual sales behind the numbers.

Will County Faces Growing Supply Pressure

Will County is showing the clearest signs of a shift toward buyers.

Active inventory increased 20.0% year-over-year. New listings rose 42.5% year-over-year. The pending-to-new listings ratio fell below parity at 0.90x, and months of supply increased 17.2%.

Unlike Cook and DuPage, Will County is seeing much more supply come onto the market. Demand has not kept up at the same pace.

That can lead to:

      • More buyer leverage
      • More seller concessions
      • Greater pricing pressure
      • Slower absorption
      • More competition among listings

Will County condos are also showing stress. The condo market posted the lowest absorbed-to-list ratio among the counties at 0.84x, which points to larger gaps between asking prices and completed sale prices.

For lenders and investors, this is a market where appraisal accuracy is especially important. Rising supply can affect collateral risk, pricing expectations, and timing decisions.

Mortgage Rates Still Matter

National housing affordability and inventory conditions continue influencing local Chicago-area buyer behavior.

The average 30-year fixed mortgage rate rose slightly to 6.30% during Week 18, according to housing finance data and broader Federal Reserve rate trends. The increase was small, but affordability pressure still affects each county differently.

Cook County remains more affordable compared with higher-priced areas, which helps support buyer activity. Lake and DuPage Counties have higher median absorbed prices, so buyers there may be more sensitive to rate changes.

These affordability differences help explain why county-level trends are starting to move apart.

Why County-Level Appraisals Matter More in 2026

The main takeaway from Week 18 is simple: Chicago is not moving as one market.

Conditions now vary by county in meaningful ways. Demand, inventory, pricing, seller leverage, buyer leverage, and market speed are all changing at different rates.

For attorneys, accountants, lenders, brokers, and investors, this creates real risk if decisions are based only on broad metro data.

A reliable appraisal should reflect the specific market, property type, price range, and current transaction activity. That level of detail helps support stronger lending decisions, clearer litigation support, better pricing strategy, and more confident financial planning.

Chicago Housing Market Outlook for Q2 2026

Cook County remains the strongest seller-market environment in the Chicago region. Low inventory and steady buyer demand continue to support pricing.

DuPage County also shows strong demand, but pricing signals need careful review.

Lake County has mixed indicators, so deeper sales analysis is needed before drawing firm conclusions.

Will County carries the most supply-side risk right now. Inventory growth is outpacing demand, and that could create more pricing pressure if the trend continues.

The next few weeks will show whether these county-level differences widen or settle. For now, local real estate appraisal insight remains essential for anyone making high-stakes property decisions across the Chicago metro area.

Chicago single-family housing inventory trends and appraisal insight March 2026
Chicago Real Estate Appraisal Update: Second Week of March 2026

What the Chicago Housing Market Means for Attorneys, Accountants, Bankers, and Brokers

During the second week of March 2026, the Chicago metro housing market continued to show a familiar pattern: tight supply, stable pricing, and demand that remains sensitive to interest rates. For professionals who rely on real estate appraisal in litigation, lending, estate work, tax matters, and transaction support, this matters because even small market shifts can affect value conclusions and decision quality.

This is not a market where surface-level pricing trends tell the full story. You need appraisal analysis that explains how current supply, buyer behavior, and financing conditions influence property-specific outcomes.

Tight Inventory Continues to Shape Value

The Chicago metro remains a supply-constrained market. The report shows about 7,615 single-family homes and 3,956 condominiums on the market, for total inventory near 11,570 properties, which is roughly 2.3% below last year.

For you, that has direct appraisal implications.

When supply remains limited, comparable sale selection becomes more important. Fewer relevant comps can increase the significance of adjustment support, neighborhood context, and timing analysis. That is especially important when an appraisal must hold up in underwriting, dispute resolution, or advisory review.

In practical terms, a constrained market can create pricing resilience while also increasing interpretation risk. That means you benefit from an appraisal that does more than summarize data. You need one that explains what the data means.

Single-Family Housing Still Shows More Strength

Single-family housing remains the stronger segment in the Chicago metro area. In the report, the median list price for single-family homes reached $389,900, up 2.6% year over year, while the median absorbed price rose to $379,900, up 5.6% year over year. Months of supply remained low at 1.44 months.

That combination points to continued support for pricing, even though transaction activity is not accelerating aggressively.

For attorneys, lenders, and financial professionals, this matters because stronger pricing does not remove the need for caution. It increases the need for supportable conclusions. A rising market can still contain overpricing, weak comparables, and negotiation-driven price differences that need proper interpretation.

The Condo Segment Looks More Balanced

The condo segment shows a different pattern. Active inventory rose modestly year over year, and pricing gains were more restrained. The median condo list price was $329,999, while the median absorbed price was $304,950. Months of supply sat near 1.41 months, with more balanced supply-demand conditions than in the single-family segment.

This distinction matters because condo appraisal assignments should not be interpreted through the same lens as single-family properties. If you are advising on a condo-related matter, you may be dealing with different buyer behavior, different competitive pressures, and different pricing support.

That difference can materially affect appraisal conclusions, especially when the assignment is tied to litigation strategy, portfolio review, or transaction structuring.

Mortgage Rates Still Influence Market Behavior

Financing conditions remain one of the biggest variables affecting the market. The report notes a 30-year mortgage rate of approximately 6.11%, lower than last year but still elevated relative to the ultra-low-rate environment seen earlier in the decade.

For your decisions, that creates a higher-rate operating environment where demand can improve modestly without becoming fully loose or aggressive. Buyers may have more relief than they had a year ago, but affordability still limits movement.

That is important in appraisal work because financing conditions affect:

      • buyer pool depth
      • pricing sensitivity
      • time on market
      • negotiation behavior

In other words, rates do not just affect sales volume. They influence the market evidence used to support value.

Demand Is Holding, but It Is Not Immune to Risk

Pending activity suggests a market that is stable but not immune to disruption. Single-family pending sales were slightly below last year, and condo pending sales also showed softening year over year. At the same time, weekly movement reflected some seasonal spring activity.

That creates an important takeaway for professionals: this is a market where conditions can hold steady and still remain fragile.

For appraisal users, the risk is assuming stability means predictability. It does not. Interest-rate shifts, inflation pressures, and broader economic changes can affect value support faster than many stakeholders expect.

Price Reductions Still Matter

Even with constrained inventory, not every listing has pricing power. The report shows 25.2% of single-family listings had price reductions.

That matters because it shows a more nuanced market than headline price growth alone suggests. Sellers may still need to adjust expectations, and buyers remain selective. For you, that means appraisal analysis should separate broad market strength from individual asset performance.

A credible appraisal helps you understand whether a property is benefiting from real market support or simply entering the market with aspirational pricing.

Why This Matters for Appraisal Clients

In the second week of March 2026, the Chicago market continued to reflect a combination of:

      • limited supply
      • stable to modestly rising prices
      • interest-rate sensitivity
      • different conditions by property type

That matters to you because appraisal assignments in this environment require more than basic market commentary. They require defensible interpretation.

Whether you are handling litigation, advising a client, underwriting a loan, evaluating collateral risk, or planning for estate or tax decisions, accurate real estate appraisal helps you move forward with more confidence and less uncertainty.

Bottom Line

The Chicago housing market remains structurally tight, especially in single-family housing, and that continues to support pricing into March 2026. But this is still a rate-sensitive market with uneven conditions across segments. That makes reliable real estate appraisal especially valuable.

When the market is stable but fragile, your advantage comes from clear analysis, supportable conclusions, and local appraisal expertise.

Chicago condo months of supply February 2026
Chicago Residential Real Estate Market Trends – Week 7

Chicago Residential Real Estate Market Trends – Week 7, 2026

The latest Chicago residential real estate market trends show declining pending sales, rising months of supply, and widening pricing gaps across Cook, DuPage, Lake, and Will Counties.

If you rely on defensible real estate appraisal analysis for litigation, lending, estate planning, or brokerage strategy, these trends directly affect risk exposure and value conclusions.

This market intelligence is based on Week 7 data ending February 13, 2026.

Executive Summary: A Market Tilting Toward Buyers

Week 7 data confirms continued softening across the Chicago residential landscape.

      • Cook County pending sales: -26.6% YoY
      • Lake County pending sales: -13.8% YoY
      • Single-family months of supply: Up as much as 40.6% YoY
      • 30-year mortgage rate: 6.09% (down 11.4% YoY)

You can verify national mortgage rate trends via the Freddie Mac Primary Mortgage Market Survey.

And historical 30-year fixed data on FRED: https://fred.stlouisfed.org/series/MORTGAGE30US

Lower financing costs typically stimulate activity. However, current Chicago residential real estate market trends show buyers remain cautious despite improved borrowing conditions.

Why this matters to you:
When absorption slows while inventory expands, appraisal support must carefully reconcile time adjustments, pricing pressure, and concession analysis.

Single-Family Homes: Supply Expansion Meets Demand Slowdown

Cook County

      • Active Inventory: 3,415 (-8.1% YoY)
      • Pending Sales: -26.6% YoY
      • Median Days on Market: 84 (+9.1%)
      • 25.8% of listings reduced price

Longer marketing times combined with widespread price reductions indicate negotiating leverage is shifting.

For attorneys and lenders, this affects:

      • Date-of-value defensibility
      • Retrospective appraisal exposure
      • Refinance underwriting risk

If your case or transaction requires court-defensible analysis, review how PahRoo structures litigation-ready appraisal reports, you can find out more from here: If Your Appraisal Gets Challenged, Does It Hold Its Ground?

DuPage County

      • Median Absorbed Price: $489,900 (-14.7% YoY)
      • Absorbed-to-List Ratio: 75%

A 75% absorbed-to-list ratio suggests significant discounting in upper-tier suburban segments.

For estate planning or partnership disputes, this means comparable selection must be segmented and time-supported, not averaged.

If you need a defensible residential appraisal for lending, litigation, or estate work, start here: Residential Home Appraisal Services

Will County

      • Inventory: +14.3% YoY
      • Months of Supply: +40.6% YoY

Rapid supply expansion without matching demand creates downward pricing pressure if Q2 stabilization fails.

For Chicago-area assignments requiring defensible, court-ready analysis, review our Chicago Real Estate Appraisals services.

Condominium Market: Mixed Signals

Condo segments present a more nuanced pattern within current Chicago residential real estate market trends.

Cook County Condos

      • Active Inventory: -9.7% YoY
      • Median Absorbed Price: -5.1% YoY
      • Days on Market: 70 (-9.1%)

Shorter marketing times contrast with price softening, suggesting selective buyer activity rather than broad strength.

Will County Condos

      • Inventory: +56.4% YoY
      • Months of Supply: +53.2% YoY

Oversupply risk is emerging in specific condo corridors.

If you’re handling probate, divorce, or estate assignments, market segmentation is critical. Learn how probate appraisal risk is addressed here: Chicago Probate Appraisal: A Legal Safeguard in 2026

Pricing Indicators Professionals Should Monitor

Key signals in these Chicago residential real estate market trends:

      • Absorbed-to-List below 100% in DuPage (75%) and Lake (77%)
      • 25.8% of Cook single-family listings reducing price
      • Days on market expansion in key submarkets
      • Declining pending-to-new-list ratios

These increase:

      • Refinance exposure
      • Litigation sensitivity
      • Estate tax defensibility risk
      • Broker pricing misalignment risk

When absorption weakens and supply expands, appraisal credibility depends on segmented data interpretation, not headline averages.

Interest Rates: A Cushion, But Not a Catalyst

The effective federal funds rate is 3.64% right now.

If you want to track rate movement (and cite it cleanly in a memo, underwriting file, or expert report), use these primary sources:

  1. Check the official benchmark on the New York Fed’s EFFR reference page
  2. Pull the historical trend line from FRED’s EFFR time series
  3. Confirm broader rate context on the Federal Reserve’s H.15 rates release

Here’s the key takeaway for decision-makers: cheaper money helps, but it doesn’t force buyers off the sidelines. Current Chicago residential real estate market trends show that even with easing borrowing costs, transaction velocity hasn’t snapped back.

Why? Buyers still act like they’re holding the remote. They’re waiting for clearer signals: pricing realism, job confidence, and the sense that they won’t overpay today for a market that could soften tomorrow.

Q2 2026 Outlook: Stabilization or Prolonged Buyer’s Market?

If:

      • Pending sales stabilize
      • Months of supply plateaus
      • Mortgage rates remain near 6%

The market may rebalance by late Q2.

If:

      • Inventory continues rising
      • Price reductions expand
      • Absorption weakens further

A prolonged buyer’s market becomes likely.

For attorneys, bankers, accountants, and brokers, this is where professional-grade real estate appraisal analysis protects you from unsupported assumptions and mispriced exposure.

Markets move fast. Risk moves faster. Stay informed with our Chicago Real Estate Market Insights and Weekly Analysis Updates.

Why These Chicago Residential Real Estate Market Trends Matter to You

You gain:

      • Early identification of pricing pressure
      • Stronger comparable support
      • Defensible time adjustments
      • Reduced underwriting or litigation exposure
      • Market-backed decision clarity

In a transitioning environment, precision matters.

Is your assignment, transaction, or case dependent on analysis that will actually hold up under scrutiny?

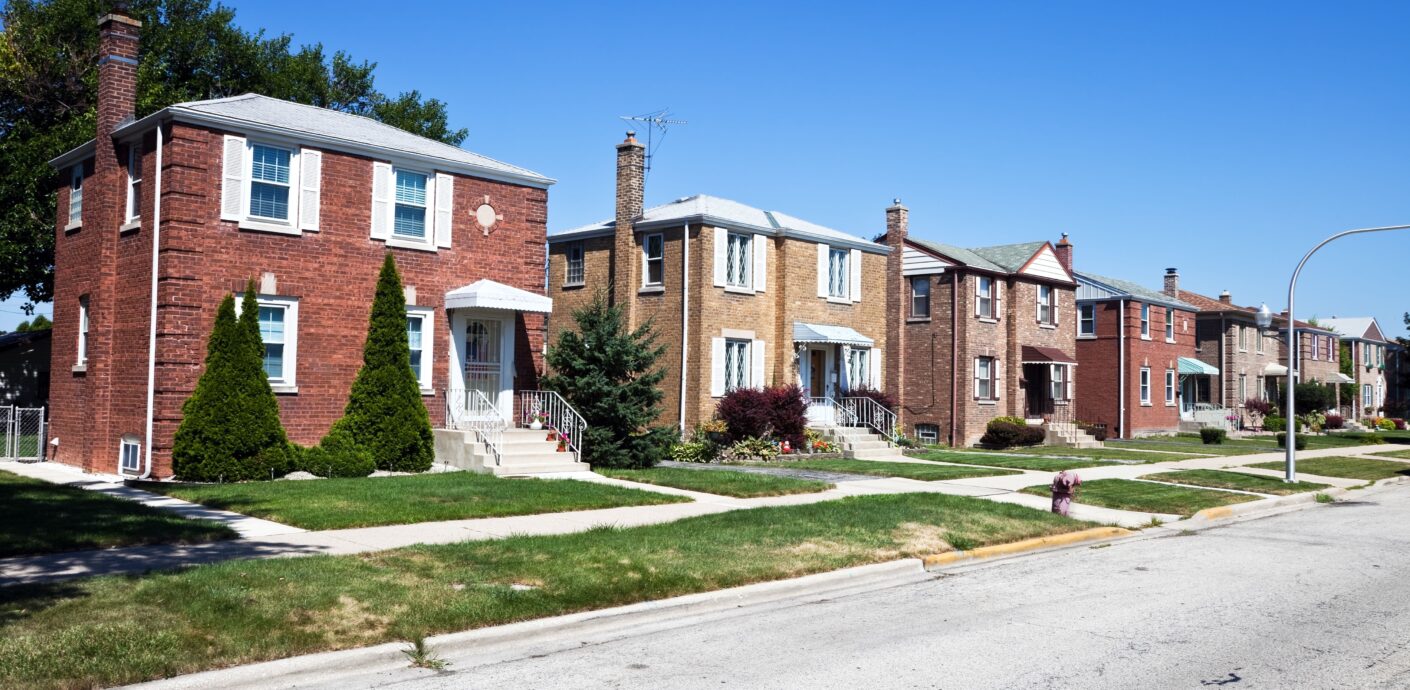
Chicago neighborhood streetscape reflecting the real estate trends shaping the market
Chicago Real Estate Trends an Appraiser Watches

Chicago generates a fresh pile of market headlines every month, and most of them expire just as fast. The Chicago real estate trends that matter are the ones underneath: the patterns that hold while the monthly numbers wobble. As appraisers, we watch those patterns for a living, because they decide what properties are worth here. So this page tracks the durable ones, and our monthly reports handle the wobble.

By the end of this article, you’ll know:

  • Why Chicago keeps landing on the tight-supply side of the national map.
  • How one metro splits into four different markets, county by county.
  • The two local forces, taxes and zoning, that bend values here like nowhere else.

The Chicago Real Estate Trends That Persist

So start with the pattern national data keeps confirming. In Realtor.com’s 2026 Market Clock analysis, only about a quarter of the 50 largest metros remain seller’s markets. Those sit mostly in the Midwest and Northeast, and Chicago made the short list of peak seller markets. Every buyer’s market sits in the South or West. So while much of the country rebuilt its for-sale inventory, Chicago stayed supply-constrained.

That is not a fluke of one survey. The region’s housing stock is old, and new construction has lagged demand for years. Owners holding low mortgage rates also have little reason to list. Tight supply became Chicago’s resting state, so it shapes everything downstream. Expect competitive conditions for well-priced homes, resilient prices, and a market that punishes overpricing by silence rather than lowball offers. One more durable habit follows from it. Well-prepared listings move fast here, while stale ones linger visibly. So Chicago sellers win by pricing right in the first week. Chicago buyers win by being ready before the right house appears.

One Metro, Four Different Markets

Averages, after all, hide the real Chicago. Our June 2026 market report found the metro splitting by county. Cook held prices on scarce inventory, while DuPage and Will showed demand-led growth. Lake County’s gains, meanwhile, rested on thin demand. Two sellers thirty miles apart can face opposite markets in the same month. So a metro-wide headline tells neither of them much.

The city also tells its own two-track story. Family buyers keep pushing into space, which keeps the suburbs and the bungalow neighborhoods competitive. Downtown’s condo segment runs on a different clock. In our appraisal work, the high-rise overhang that built up after 2020 has been steadily absorbed. Demand for well-located units has returned, too. The recovery is a trend precisely because it has persisted across seasons rather than spiking in one.

So match the trend to the move you are making. Selling a bungalow in a tight ward? Supply is your friend, if the price respects the block. Buying downtown? The recovery rewards patience less every season. Hunting in DuPage or Will? Expect company, and expect to prove your number. Each answer comes from the pattern, not the headline.

The Chicago X-Factor Is Property Taxes

No durable read on this market survives without the tax layer. Cook County’s system bends buyer math here like nowhere else. Assessments run on a three-year cycle, and the City of Chicago gets reassessed in 2027. The bill also arrives a year behind the value. So tax risk is part of every Chicago purchase, and savvy buyers price it in. A home with a stale low assessment carries a future bill increase. One with a fresh high assessment may carry appeal potential instead. So when you tour a Chicago home, ask for the tax history, too. If the assessment lags the price, budget for the catch-up. If it overshoots, an appeal may claw some back. Either way, the tax layer belongs in your offer math. Our plain-language guide to Cook County property taxes walks through the whole chain.

Policy Keeps Redrawing the Map

The second local force is zoning, and it moved recently. In September 2025, the City Council unanimously approved an ordinance legalizing accessory dwelling units. It covers areas zoned for small apartment buildings and business districts, with by-right status in the original pilot zones. In single-family zones, allowance depends on the local alderperson. So the same bungalow can hold ADU potential in one ward and none next door. That ward-by-ward patchwork is now part of lot values across the city. We covered the mechanics in our piece on how zoning changes property value. It belongs on any list of trends shaping Chicago prices, too.

Follow the Monthly Numbers, Price on the Pattern

Put the two layers together and the playbook writes itself. Check the monthly data for where the market sits right now, because timing questions live there. Then make the actual decision on the structural picture. That means your county’s dynamics, your block’s supply, the tax trajectory, and what the zoning permits. A pre-decision appraisal pulls all of it into one defensible number for your specific property. In a metro where the answer changes every few miles, that number beats any trend piece, including this one.

Which Chicago are you buying in?

Cook, DuPage, Will, and Lake run on different math. Get an appraisal built from your county’s evidence, not the metro average.

Value My Side of the Metro

Frequently Asked Questions

Is Chicago a buyer’s or seller’s market?

In 2026, Chicago ranks among the strongest seller markets in the country, per Realtor.com’s Market Clock analysis. Tight Midwest inventory drives it. Conditions vary by county and neighborhood, though, so check current local data before pricing a specific property.

Why is Chicago housing inventory so tight?

Three durable reasons. The region’s housing stock is old and new construction has lagged demand for years. Owners holding low mortgage rates have little incentive to list, and demand for well-located homes has stayed steady. Together they made tight supply Chicago’s resting state.

Are the Chicago suburbs more competitive than the city?

Often, because family buyers compete for space. Our June 2026 report found DuPage and Will counties showing demand-led growth while Cook County held prices on scarce inventory. The city runs two tracks of its own. Neighborhood homes stay competitive while the downtown condo segment sits in a steady recovery.

How do property taxes affect Chicago home values?

Heavily. Cook County reassesses on a three-year cycle, with the City of Chicago next reassessed in 2027. Bills also run a year behind values. Buyers price in tax trajectories. So a stale low assessment implies a future increase, while an overshooting one may support an appeal.

Where can I see current Chicago market data?

Our monthly Chicago market reports track prices, inventory, and county-level dynamics as they move. This page covers the structural patterns behind them. For a decision about a specific property, an independent appraisal translates both layers into one defensible value.

Field Data From Two Decades of Chicago Appraisals

PahRoo Appraisal & Consultancy has valued Chicago-area homes and buildings for more than twenty years. An appraiser holding both MAI and SRA designations leads the firm. Maybe you need a residential appraisal before a purchase or sale. Maybe an estate, divorce, or tax matter calls for broader appraisal services. Either way, the trends above stop being abstractions and become the evidence behind your number.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712