Tag: Commercial Real Estate Appraisal

Request a quote

Our blog

Latest news
& events

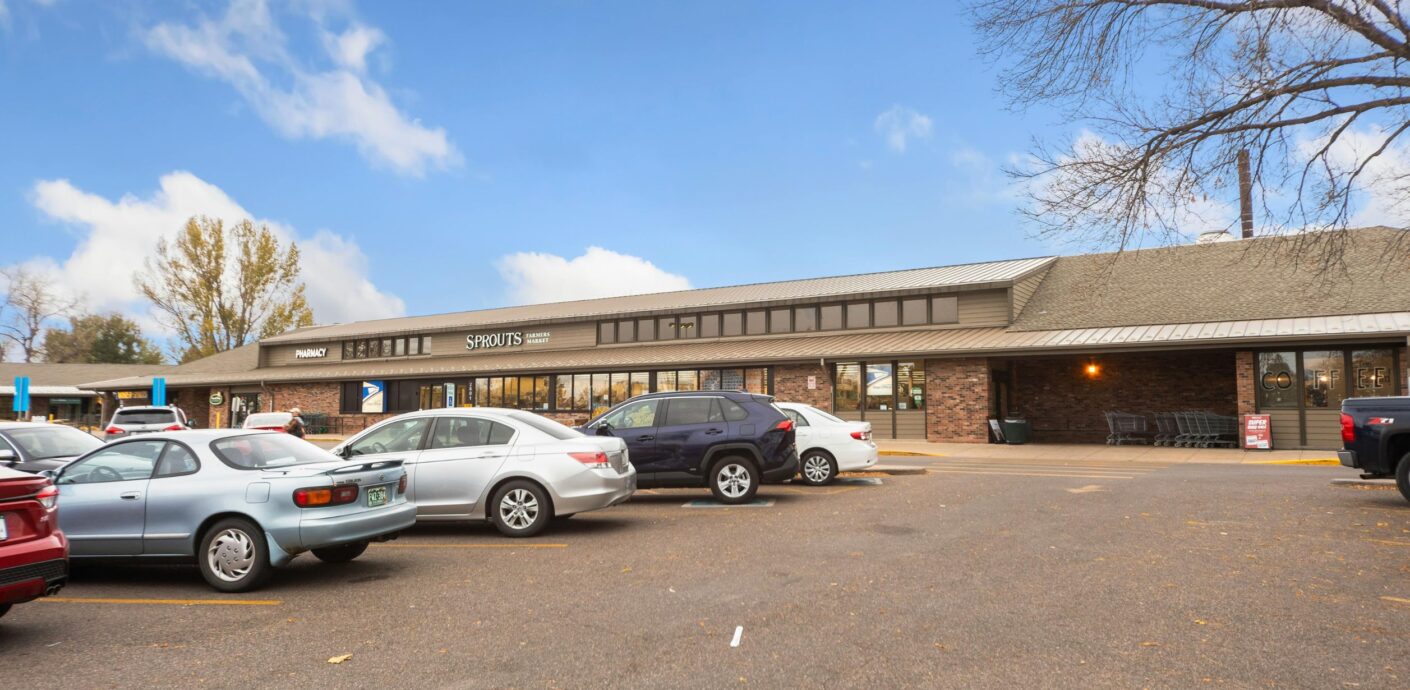
Neighborhood strip center with grocery anchor and inline shops, the subject of a retail property appraisal
Retail Property Appraisal and What Moves the Value

Two strip centers on the same road, same size, same age, same asking price. One is worth 15 percent more than the other, and nothing about the buildings explains why. The leases do. A retail property appraisal spends less time on the roof and the parking lot than brokers expect. It spends far more on who signed the leases, how long they run, and what happens to the rent when they end. So here is how location, tenants, and lease terms each move the number.

By the end of this article, you’ll know:

  • How trade area, access, and co-tenants set the ceiling on retail rent
  • Why tenant credit and tenant category can move a cap rate more than the building does
  • What a rent roll and lease abstract have to show before the appraisal can start

Location Sets the Ceiling

Retail rent is a function of what a tenant can sell from that spot. So the appraiser starts outside the property line. The trade area is the geography a center actually draws from. That may be a one-mile ring for a grocery-anchored neighborhood center, or a 20-minute drive for a destination power center. Population, household income, and daytime employment inside that area tell the appraiser what rent the market can bear. Then traffic counts, visibility, and access decide whether a tenant can capture it.

Co-tenancy matters almost as much as the corner. An inline space next to a strong grocer rents for more than the same space next to a vacant box. The grocer brings the cars. Anchors, shadow anchors across the street, and out-parcel pads all shape the rent an inline tenant will pay. So when the appraiser selects rent comparables, the first filter is not square footage. It is whether the comparable center has the same kind of draw.

Tenants Set the Cap Rate

Once the rent is established, the question shifts to how reliable it is. Two centers with the same net operating income can trade at very different prices. A buyer pays more for income that is likely to arrive. A national credit tenant on a long lease is income a buyer can underwrite. A first-year local operator is a bet. The appraiser reflects that difference in the capitalization rate. In practice, the spread between a credit-anchored center and a local-tenant center can be wider than the spread between a new building and an old one.

Tenant category matters too, and the national numbers show why. The Census Bureau’s July 2026 retail sales release put total retail and food services sales up 5.0 percent from a year earlier. Underneath that headline, nonstore retailers were up 7.7 percent and restaurants and bars were up 5.0 percent. Furniture stores were down 1.2 percent. So a center full of restaurants and service tenants is riding a different current than a center full of furniture showrooms. The appraiser’s vacancy and credit loss assumptions should say so.

Where tenant sales are available, the occupancy cost ratio is the health check. Rent plus recoveries, divided by sales, tells the appraiser whether a tenant can afford its lease. A tenant paying more of its sales than its category can sustain is a renewal risk no matter what the lease says. Most appraisals do not get sales data, though. Then the appraiser leans on category trends and the tenant’s public reporting where it exists.

Lease Terms That Change the Number

This is the section that does the work, and the one most rent rolls are least prepared for. The lease structure comes first. Under a triple net lease, the tenant pays its share of taxes, insurance, and common area maintenance on top of base rent. So the landlord’s net income sits close to the base rent. Under a gross lease, the landlord absorbs those costs, and rising taxes come straight out of net operating income. A modified gross lease splits them. Two centers with identical base rents can have very different net income. That is why our guide to net operating income starts with the recovery structure.

Term and rollover come next. A center where 40 percent of the income expires within 24 months carries costs a fully leased center does not: downtime, tenant improvement allowances, and leasing commissions. The appraiser models those costs in the year they land. So a long-term rent roll and a short-term rent roll with the same current income do not support the same value under the income approach. Renewal options, and whether they are at fixed rent or market, sit inside the same analysis.

Then the clauses that brokers sometimes skip. A co-tenancy clause lets a tenant reduce rent or leave if an anchor goes dark or occupancy drops below a threshold. So one vacancy can cascade. An exclusive-use clause blocks the landlord from leasing to a competing use. That narrows the pool of replacement tenants. Rent escalations, percentage rent breakpoints, and caps on CAM recoveries all change the income stream. None of them show up on a one-page rent roll. All of them show up in value.

What a Retail Property Appraisal Needs From the Rent Roll

A usable rent roll lists every suite with tenant name, square footage, lease start and expiration, and current base rent. It also shows the escalation schedule, recovery structure, renewal options, and any abatement still running. Behind it, the appraiser needs lease abstracts or the leases themselves for anchors and any tenant over about ten percent of the income. Add the last two years of CAM reconciliations and operating statements. Vacant suites need asking rent and the date they went dark.

When that package is complete, the appraisal moves quickly and the conclusions are defensible. When it is missing, the appraiser fills gaps with market assumptions. Market assumptions rarely favor the seller. The same package is what the buyer’s lender will ask for. So assembling it once serves the listing, the appraisal, and the closing.

A Hypothetical Neighborhood Center

Consider a 25,000 square foot center: a 12,000 square foot grocer on a triple net lease with 11 years left, six inline tenants, and one 1,800 square foot vacancy. Net operating income is $504,000. Suppose the inline leases are staggered, with no more than one expiring in any year, and the grocer is a regional credit. An appraiser might support a 7.0 percent cap rate, indicating $7,200,000.

Now change one fact. Four of the six inline leases expire within 18 months, and two tenants are month-to-month. The grocer has a co-tenancy clause tied to inline occupancy. Same building, same income today. An appraiser might now support an 8.0 percent rate, landing near $6,300,000, and deduct lease-up costs on top. The gap is close to $900,000 before those deductions. Every dollar of it lives in the leases.

Where Owners Get Ahead of the Appraisal

For an owner planning a sale or a refinance, the highest-return work happens before the appraiser is engaged. Renew the tenants whose leases expire inside the next two years, even at a modest concession. Term is worth more than the last dollar of rent. Resolve open co-tenancy exposure by backfilling the space that triggers it. Finish the CAM reconciliations so recovery income is documented rather than estimated. And abstract every lease so the rollover schedule, options, and clauses sit in one place. Each step converts an assumption into a fact the appraiser can cite.

Read the Rent Roll Before You Read the Cap Rate

When a retail appraisal lands on your desk, skip the cover value and go to the rent roll analysis. Check that lease structures are identified suite by suite and the rollover schedule is laid out by year. Check that the anchors’ clauses are addressed by name. Then check that the cap rate reflects the tenants actually in the building, not a survey average. If those pieces are there, the value will hold up with the buyer’s lender. If they are not, the number is a guess with a decimal point. Our overview of the three approaches to value shows how the income analysis fits with the others. For retail, it is nearly always the one that decides.

Pricing a Center With Rollover on the Horizon?

PahRoo appraises retail property from the leases up, with rollover modeling and cap rate support a buyer’s lender will accept.

Request a Retail Appraisal Quote

Frequently Asked Questions

How is a retail property appraised?

Primarily through the income approach. The appraiser analyzes the rent roll and leases to establish net operating income, evaluates tenant credit and lease term to select a capitalization rate, and models lease-up costs for expiring or vacant space. Sales comparison serves as a check on the result, and location analysis of the trade area, traffic, and co-tenancy frames the rent the market will bear.

What is a triple net lease and why does it matter to value?

Under a triple net lease the tenant pays its share of property taxes, insurance, and common area maintenance in addition to base rent. The landlord’s net income is close to the base rent and is insulated from rising expenses. Under a gross lease the landlord absorbs those costs, so the same base rent produces lower net operating income and a lower value.

How does tenant credit affect the cap rate?

Buyers pay more for income they are confident will arrive, so a center anchored by a national or regional credit tenant on a long lease supports a lower capitalization rate than a center leased to local operators on short terms. The appraiser reflects that in the rate, and the spread between the two can move value more than the age or condition of the building.

What is a co-tenancy clause?

A lease provision that lets a tenant reduce rent or terminate if a named anchor closes or center occupancy falls below a set level. It means one vacancy can trigger others. An appraiser reads anchor and major tenant leases for these clauses and accounts for the exposure in the vacancy and credit loss analysis.

What does an appraiser need from the rent roll?

Every suite with tenant name, square footage, lease start and expiration, current base rent and escalations, recovery structure, renewal options, and any abatements still running. Behind the rent roll, the appraiser needs lease abstracts or full leases for anchors and major tenants, two years of operating statements, and the CAM reconciliations.

Retail Valuation From the Lease Up

Brokers, owners, and lenders across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples engage PahRoo Appraisal & Consultancy for retail assignments from single-tenant pads to anchored centers. Our commercial appraisal services page lists the property types we cover, and our article on office building value drivers shows the same lease-first method applied to a different asset class. To discuss a retail property, contact our team.

Newly built commercial property valued through a cost approach commercial appraisal
The Sales Comparison and Cost Approaches in Commercial Appraisal

Two of the three approaches to value get less attention than they deserve. The income approach dominates most commercial reports, so brokers and lenders tend to skim the rest. That is a mistake on the wrong property. A cost approach commercial appraisal is often the only credible path to value on a new building or a special-use facility. And the sales comparison approach tells you whether a buyer’s likely price lines up with what the income says. So here is how each one works, when it leads, and what to check when you read one.

By the end of this article, you’ll know:

  • How the sales comparison approach is adapted for commercial property with thin data
  • What a cost approach actually adds up, and how depreciation is measured
  • When each approach should carry the weight, and how to check that it does

How the Sales Comparison Approach Works for Commercial Property

The sales comparison approach values a property by what similar properties sold for, adjusted for the differences. Residential appraisers usually have several nearby sales from the last few months to work with. Commercial appraisers rarely have that luxury. A submarket may produce four flex-industrial sales in two years, and none of them is a twin of the subject.

So the method bends to fit the data. The search area widens, sometimes to the whole metro. The time window stretches too. Then a market conditions adjustment has to account for price movement between the comparable’s sale and the effective date. The unit of comparison also changes with the property type: price per square foot for industrial and office, price per unit for apartments, price per net rentable square foot for self-storage, price per key for hotels.

Adjustments are where the work lives. Location, size, age and condition, construction quality, ceiling height, loading, parking ratio, and lease status all get weighed. Where possible, paired sales or market participants support each adjustment, not the appraiser’s instinct. A grid of round-number adjustments with nothing behind them is the first thing a reviewer questions. Our overview of the three approaches to value covers how they fit together. This piece goes deeper on the two that get skipped.

One more commercial wrinkle. A sale of a leased building reflects the leases, not just the bricks. A comparable with a credit tenant on a ten-year lease is not the same as a vacant building of the same size. So the appraiser has to know the terms of each sale. Confirming them with a broker or a principal is part of the job, not a courtesy.

What a Cost Approach Commercial Appraisal Adds Up

The cost approach asks a simple question. What would it cost to buy the land and build this property new today, less the value the existing building has lost? The formula runs: site value, plus replacement cost new, plus entrepreneurial incentive, minus accrued depreciation.

Site value comes from land sales, so the cost approach starts with its own small sales comparison analysis. Replacement cost new is the cost to build a modern equivalent with the same utility, not an exact copy. That distinction matters on older buildings. Reproducing a 1920s masonry warehouse with its original details would cost far more than replacing its function with a tilt-up box. Buyers pay for function. Cost figures come from published cost services, contractor bids, and recent local projects. They cover direct costs such as labor and materials, plus indirect costs such as architecture, permits, financing, and lease-up.

Entrepreneurial incentive is the profit a developer would need to take on the project. Leaving it out understates cost. Including it without market support overstates it. Either way, it should be visible in the report, not buried.

The Uniform Standards of Professional Appraisal Practice require a developed cost approach to address site value, cost new, and accrued depreciation. That last item is where most of the judgment sits.

How Depreciation Is Measured

Depreciation in an appraisal is not the tax schedule. It is the gap between what the building would cost new and what it contributes to value today. It comes in three forms.

Physical deterioration is wear. Roofs age, parking lots crack, mechanical systems reach the end of their lives. Some of it is curable, meaning the cost to fix is less than the value it adds back, and some is not. Functional obsolescence is a design problem. Think 14-foot clear height in a market that wants 32 feet, or too little power for modern loads. External obsolescence comes from outside the property line, such as rising submarket vacancy or a highway interchange that moved the traffic.

Appraisers measure depreciation several ways. The age-life method compares effective age to total economic life. Market extraction pulls depreciation out of actual sales. Subtract land value from the sale price, then compare what remains to cost new. Breakdown analysis prices each form of depreciation separately. On a new building the number is small and easy to support. On a 45-year-old building it can exceed half of cost new. The further the estimate has to reach, the less weight the approach deserves.

A Worked Example on an Industrial Building

Consider a 36,000 square foot warehouse, twelve years old, in a stable industrial submarket. The cost approach might run like this:

  • Site value from land sales: $900,000
  • Replacement cost new, including indirect costs and entrepreneurial incentive: $4,200,000
  • Less accrued depreciation at 30 percent: $1,260,000
  • Depreciated cost of improvements: $2,940,000
  • Indicated value by the cost approach: $3,840,000

Now the sales comparison approach. Four metro warehouse sales, adjusted for location, age, clear height, and market conditions, bracket $98 to $112 per square foot. The appraiser reconciles to $105 per square foot, which indicates $3,780,000.

The two approaches land within two percent of each other. That agreement is itself evidence. When the approaches disagree by 20 percent, something is wrong with an input, and the reconciliation should say which one.

When There Are No Comps

Some properties have almost no market. A fire station, a school, a church, or a purpose-built manufacturing plant may trade once in a generation, and often not as the same use. These are special-use properties. Income struggles because there is no rental market. Sales comparison struggles because there are no sales. Cost is usually the only approach with real evidence behind it.

New construction is the other clear case. A building completed last year has minimal depreciation, current cost data, and a land value that can be supported. Lenders financing construction lean on cost for exactly that reason. Still, they expect it to reconcile against the completed value from the other approaches.

Cost also plays a quieter role on ordinary income property. When the income approach lands well below what it would cost to build, new supply is not feasible at current rents. That gap tells a lender something about competitive risk. It tells a broker something about how long existing stock will hold its pricing. An appraiser who develops cost even when it does not lead is giving you that signal for free.

Where Each Approach Earns Its Weight

On a stabilized multi-tenant building, income leads and sales comparison supports it. On an owner-occupied building with an active market, sales comparison may lead. Owner-user buyers think in price per square foot, not cap rate. On a special-use facility or a building still in its first year, cost leads. Our piece on what drives office building value shows the income-led case in detail.

The weighting is a judgment the appraiser has to explain. A report that develops all three approaches and then averages them has not reconciled anything. A report that leans on one approach should say why its evidence is stronger. Read the reconciliation with that question in mind, and you will know quickly whether the report was built or assembled.

Ask Which Approach Carried the Weight, and Why

Before relying on a commercial value, find the reconciliation and check three things. First, was the leading approach the right one for this property type and its data? Second, do the sales adjustments and the depreciation estimate have market support the report actually shows? Third, do the approaches agree, and if not, is the gap explained? If any answer is no, the cover-page number rests on less than it appears to. So ask the appraiser. A good one will walk you through it.

Selling a Building With No Clean Comps?

PahRoo develops the sales comparison and cost approaches with the support shown, so brokers can price with confidence and lenders can see the evidence.

Scope a Commercial Appraisal

Frequently Asked Questions

When is the cost approach used in commercial appraisal?

It leads on new or nearly new buildings, where depreciation is small and costs are current, and on special-use properties such as schools, churches, and purpose-built plants that have few or no comparable sales. On ordinary income property it usually supports the conclusion and serves as a feasibility check against the income approach.

How does the sales comparison approach work for commercial property?

The appraiser locates sales of similar properties, confirms the terms of each sale, and adjusts for differences in location, size, age, condition, lease status, and market conditions. Because commercial sales are scarce, the search often covers a wider area and a longer time period, and the unit of comparison changes by property type.

Why is the cost approach used for special-use property?

Special-use properties rarely sell and rarely rent, so the sales comparison and income approaches have little evidence to work with. The cost approach can still be developed from land sales, current construction costs, and a supported estimate of depreciation, which makes it the most credible path to value for those properties.

How is depreciation measured in a commercial appraisal?

Appraisal depreciation is the gap between cost new and the building’s current contribution to value. It includes physical deterioration, functional obsolescence, and external obsolescence. Appraisers estimate it through the age-life method, market extraction from actual sales, or a breakdown of each form, and the estimate should be supported in the report.

Are there enough comps for commercial property?

Often not many. A submarket may produce only a handful of relevant sales over two years. Appraisers widen the geography, extend the time window, and adjust for market conditions to compensate. When comparable sales are too thin to support a conclusion, the report should say so and lean on the cost or income approach instead.

Sales, Cost, and Income Analysis From One Appraisal Team

PahRoo Appraisal & Consultancy develops all three approaches to value on commercial assignments across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, from single-tenant industrial to special-use facilities. Our commercial appraisal services page covers scope and property types, our guide to net operating income explains the income side, and you can contact our team or call 773-388-0003 to discuss a specific property.

What Drives the Value of an Office Building

An office building appraisal comes down to one question: how reliably will this building produce income, and for how long? Everything the appraiser examines feeds that answer. So when owners ask why two similar-looking buildings carry very different values, the explanation almost always sits in the leases, the tenants, and the submarket rather than the architecture.

By the end of this article, you’ll know:

  • The five factors that carry the most weight in office value
  • How leases, rollover, and tenant credit shape the income analysis
  • Why Class A buildings and older stock are moving in opposite directions

What an Office Building Appraisal Weighs Most

Five factors do most of the work in an office valuation:

  • Occupancy and lease terms: how much space is leased, at what rents, and for how long
  • Tenant credit: the financial strength behind each signature on the rent roll
  • Location and submarket: the vacancy, rent, and demand picture on that block, not the metro average
  • Building class and condition: where the property sits in the flight to quality
  • Market cap rates: what buyers currently pay for a dollar of office income

Office buildings are valued mainly through the income approach, because buyers purchase them for their income streams. The appraiser tests each factor above and translates it into the numbers behind the value.

Income Is the Engine: Leases, Rollover, and NOI

The rent roll gets read line by line. Contract rents are compared against market rents. Expirations are mapped across the holding period, because a building with 40 percent of its leases rolling in two years carries more risk than one with staggered ten-year terms. Rent steps, expense reimbursements, tenant improvement obligations, and leasing commissions all shape the projection.

Those inputs flow into net operating income, and we covered how that number gets built in our guide to net operating income in commercial real estate. For office specifically, the vacancy assumption does heavy lifting. Actual occupancy, submarket vacancy, and realistic downtime between tenants all get weighed rather than assumed away.

Tenant Credit: The Rent Roll Behind the Rent Roll

A lease is only as good as the tenant paying it. Ten years of income from an investment-grade company is worth more than the same rent from a startup, so appraisers consider tenant quality when weighing the durability of income. Concentration matters too. A single-tenant building lives or dies with one renewal decision, while a diversified roster spreads that risk across many decisions.

This is why two buildings with identical NOI can appraise differently. The income may match today, but the probability of it continuing does not, and buyers price that difference.

Building Class, Condition, and the Flight to Quality

The office market is splitting by quality. According to the CBRE Q1 2026 U.S. office market report, overall vacancy stood at 18.6 percent while prime buildings ran at 12.7 percent, and asking rents grew at their fastest pace in six years. Tenants are concentrating in the best space and abandoning the rest.

For the appraisal, class is not a label but a set of measurable traits: systems, amenities, floor plates, energy performance, and the capital spending needed to stay competitive. An older Class B building may need substantial investment just to hold its tenancy, and that cost comes out of value. In some cases, highest and best use analysis even asks whether the building should remain an office at all.

Why Office Values Fell, and How an Appraisal Reads the Recovery

Office values dropped for two stacked reasons. Hybrid work cut demand for space, which pushed vacancy up and rents down in weaker buildings. Then higher interest rates pushed cap rates up, which cut the price of every dollar of income. National vacancy has now edged past its peak and demand has turned positive, but the recovery is uneven across markets and building classes.

That unevenness is exactly why office work demands submarket-level analysis. A metro average tells you little when one corridor is tightening and the next is emptying. Our commercial appraisal services build the value from the property’s actual leases and its actual submarket, so the conclusion reflects your building rather than the headlines.

What is your office building actually worth right now?

In a market moving this unevenly, last year’s number is stale. PahRoo appraises office property from the rent roll up, with submarket evidence a buyer or lender can verify.

Request a Commercial Appraisal Quote

Frequently Asked Questions

What drives the value of an office building?

Occupancy and lease terms, tenant credit, submarket conditions, building class and condition, and market cap rates. These determine how much income the building produces, how durable that income is, and what buyers will pay for it.

How are office buildings appraised?

Mainly through the income approach. The appraiser analyzes the rent roll, compares contract rents to market rents, applies vacancy and expense assumptions, and converts the resulting net operating income into value using market-derived rates, checked against comparable sales.

Why have office building values fallen?

Hybrid work reduced demand for space, which raised vacancy and weakened rents, while higher interest rates pushed cap rates up. Both forces cut value at once. The decline has been uneven, hitting older buildings much harder than prime space.

What is a Class A office building?

The highest-quality tier in a market: modern systems, strong locations, competitive amenities, and creditworthy tenants. Class B and C buildings are older or less competitive. Class is relative to the local market rather than a fixed national standard.

How does vacancy affect office value?

Vacant space produces no income but still incurs expenses, so vacancy reduces net operating income directly. Appraisers also weigh submarket vacancy, because it sets how long re-leasing will take and what rent the space can realistically achieve.

Office Valuation Built From the Rent Roll Up

PahRoo Appraisal & Consultancy appraises office and other commercial property across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, for owners, investors, and lenders. Start with our Chicago appraisal services page, or review our appraisal consulting FAQ for scope and timing questions.

Commercial real estate appraisal of a multi-tenant office building in Chicago
Commercial Real Estate Appraisal: When You Need One

A commercial real estate appraisal puts a defensible value on a property when real money rides on the number. Banks want one before they lend. The IRS wants one when an owner dies. Buyers, sellers, and partners heading for a split want one too. The work follows federal standards, and the report holds up under scrutiny because of it.

By the end of this article, you’ll know:

  • What a commercial appraisal measures, and how appraisers actually arrive at a value
  • Why the property type changes the whole analysis
  • The situations that call for one, from lender financing to a Cook County tax appeal
  • What drives the cost and turnaround, so you can plan around it

What a Commercial Real Estate Appraisal Measures

A commercial real estate appraisal is an independent opinion of value, prepared by a state-certified general appraiser under the Uniform Standards of Professional Appraisal Practice (USPAP). The appraiser inspects the property, studies the market, and supports the value conclusion with evidence.

This is not a home inspection. It also is not a broker’s price opinion, which a real estate agent can hand you for free. An appraisal carries more evidentiary weight, so courts, lenders, and tax authorities accept it. Residential appraisals lean mostly on recent home sales nearby. Commercial work runs deeper, because income, leases, and tenant quality all move the value.

The Three Ways Appraisers Reach a Value

An appraiser develops up to three approaches to value, then reconciles them into a single conclusion. For commercial property, one approach usually carries most of the weight.

The income approach estimates value from the rent a property produces. The appraiser starts with net operating income, which is gross rent minus vacancy and operating expenses. Then the appraiser divides that income by a capitalization rate pulled from comparable sales. A building with $200,000 in net operating income and a 7% cap rate points to a value near $2.86 million. A lower cap rate signals a lower-risk, higher-value asset. This method drives value for most income-producing property.

The sales comparison approach weighs recent sales of similar buildings, with adjustments for size, location, and condition. The cost approach estimates what it would take to rebuild, minus depreciation, plus the land value. It matters most for special-purpose or newly built property, where comparable sales are thin.

Why the Property Type Changes the Whole Analysis

The property type decides which data the appraiser leans on. A warehouse and a hotel do not get valued the same way, even at the same price point.

Office and retail values hinge on the leases. Lease length, rent levels, and the credit quality of the tenants all feed the income approach. A retail center anchored by a strong national tenant reads very differently from one with month-to-month locals.

Industrial and warehouse values turn on ceiling height, loading access, and proximity to highways and rail. Multifamily property with seven or more units gets treated as commercial, so the appraiser studies the rent roll and the unit mix. Hotels, gas stations, and self-storage are special-purpose properties. They often carry a business value on top of the real estate, and they need an appraiser who knows the category. So the right question is not just “what is it worth,” but “who is qualified to value this kind of asset.”

Appraisal or Evaluation: What Your Lender Actually Needs

An appraisal and an evaluation are not the same document, and the difference can change your timeline. Financing is the most common reason a commercial appraisal gets ordered.

Federal rules under FIRREA require an appraisal for most federally related transactions. For commercial property, the threshold sits at $500,000, raised from $250,000 in 2018. You can read the regulation itself in 12 CFR Part 323. Below that line, a bank can rely on a lighter “evaluation” instead. An evaluation costs less and turns around faster, but it does not meet USPAP and carries less weight.

There is also a business-loan carve-out. A loan of $1 million or less can skip the appraisal if the real estate is not the primary source of repayment. SBA financing usually calls for a full appraisal once the deal clears the program’s own limit. So if you are borrowing against commercial property above these thresholds, expect the lender to order one. Our commercial valuation work often starts with exactly this kind of request.

When You Need One Without a Bank in the Room

Plenty of appraisals have nothing to do with a loan. Any time a value carries legal or financial consequences, a USPAP appraisal earns its place.

Estate and gift tax. When an owner dies, the IRS wants a value as of the date of death. A qualified appraisal protects the estate if the return gets questioned later, and it supports a stepped-up basis for the heirs.

Divorce and partnership splits. When co-owners separate, someone has to value the real estate fairly. A neutral appraisal keeps the split from turning into a fight over numbers.

Litigation and financial reporting. Bankruptcy, eminent domain, and partner disputes all rely on a credible value. Companies also need appraisals to carry property correctly on their books.

Using an Appraisal in a Cook County Tax Appeal

A current appraisal is some of the strongest evidence you can bring to a commercial property tax appeal. In Cook County, the stakes are higher for commercial owners by design.

The county assesses most commercial and industrial property at 25% of fair market value, against 10% for homes (see the Cook County Assessor). So an inflated value hits a commercial owner harder than a homeowner. The county reassesses on a triennial cycle, split into three districts: the City of Chicago, the north suburbs, and the south and west suburbs. Each one gets reassessed every three years.

Timing matters here. A reduction you win in a reassessment year holds for the full three-year cycle, so that year is the one to watch. There are three levels of appeal: the Assessor’s Office, the Cook County Board of Review, and then the Illinois Property Tax Appeal Board or the Circuit Court. An appraisal is accepted evidence at each level.

At the Board of Review, a corporation has to be represented by an attorney. So commercial appeals usually pair a tax attorney with an independent appraisal. A well-supported appraisal shifts the discussion from opinion to documented analysis, and a documented value is harder for the county to wave off. Our Cook County reassessment work is built around exactly that.

What the Report Looks Like and What It Costs

USPAP allows two report formats, and the cost tracks the complexity of the property. An Appraisal Report lays out the full analysis. A Restricted Appraisal Report is shorter and meant for the client alone, so it works only when no third party will rely on it.

A small retail building might take a week or two. A complex mixed-use site with many tenants takes longer and costs more, because the analysis goes further and the data takes longer to gather. Ask for the report type and the timeline up front, so the appraisal fits your deadline rather than blowing past it.

How to Tell If You Really Need One

Use a simple test. If money, taxes, or a legal outcome turns on the value of a commercial property, get a USPAP appraisal rather than a rough estimate. A broker’s opinion can guide a listing price. It will not hold up in front of a judge, an assessor, or the IRS. When the number has to defend itself, the appraisal is what does the defending.

Put a Defensible Number on Your Property

PahRoo prepares commercial appraisals across the Chicago and Dallas markets for financing, tax appeals, estates, and disputes. Tell us the property and the purpose, and we will scope it for you.

Request a Commercial Appraisal

Frequently Asked Questions

How much does a commercial real estate appraisal cost?

Cost depends on the property type, size, and complexity. A simple building runs lower, while a multi-tenant or special-purpose property costs more because the analysis takes longer. Ask for a quote tied to your specific property and its intended use.

How long does a commercial appraisal take?

A straightforward property often takes one to two weeks. Larger or more complex assignments take longer, since the appraiser has to gather lease data, income records, and comparable sales before reaching a conclusion.

What is the difference between a commercial appraisal and a broker price opinion?

A broker price opinion is an agent’s informal estimate, often free, and it carries little evidentiary weight. A commercial appraisal follows USPAP and comes from a state-certified general appraiser, so lenders, courts, and tax authorities accept it.

Do I need a commercial appraisal for a property tax appeal in Cook County?

You do not always need one, but a current appraisal is strong evidence at the Board of Review or the Illinois PTAB. It gives you an independent value to counter the assessor’s figure, which can improve your odds on a commercial parcel. Note that a corporation must be represented by an attorney at the Board of Review.

Who is qualified to perform a commercial real estate appraisal?

A state-certified general appraiser is qualified to value commercial property. This is the highest appraisal credential, and federally related transactions require it. Make sure your appraiser holds the general certification rather than a residential license.

Need an Independent Appraisal?

PahRoo Appraisal & Consultancy provides commercial valuations along with estate, divorce, and property tax appeal appraisals in the Chicago and Dallas markets. Reach out when you need a value that stands up to scrutiny.


cost segregation appraisal process showing property analysis, component breakdown, and IRS-compliant reporting
Cost Segregation Appraisal: Avoid Costly Mistakes

A cost segregation appraisal is only as valuable as the evidence behind it. Done well, it accelerates depreciation and improves cash flow on a commercial property. Done cheaply, it can unravel the moment the IRS, a lender, or a client’s attorney asks for support. For the professionals who rely on these studies, quality matters far more than the price on the invoice.

By the end of this article, you’ll know:

  • Why a bargain study can cost more than it saves
  • What the IRS looks for when it reviews a study
  • Where an independent appraiser fits into the process

What a Cost Segregation Appraisal Really Involves

Cost segregation is a tax strategy, not a valuation on its own. A study breaks a building into its components. Then it assigns each one to the right depreciation class, so the owner can recover cost faster. The IRS treats this as an engineering-based analysis. Its Cost Segregation Audit Techniques Guide spells out what a quality study should contain.

Here is where an appraiser earns a seat at the table. Before components can be classified, someone has to establish the property’s value. That means allocating the purchase price across land, building, and improvements. That allocation is a valuation question, and it is the foundation the rest of the study stands on. Get it wrong, and every number downstream inherits the error. Our commercial appraisal work often supports exactly this kind of foundation. The engineering and tax professionals then complete the study.

Why Defensibility Matters More Than Price

Two studies can look identical on paper. Both list components, assign useful lives, and project a depreciation benefit. The real test comes later, when someone challenges the numbers.

A defensible study answers three questions cleanly. Is the methodology documented and consistent with IRS guidance? Is each classification supported by real analysis rather than assumption? Can the conclusions survive an audit? Cheaper studies often cut corners in ways that stay invisible until an examiner starts reading closely. The IRS guide is blunt on this point. Preparer qualifications and documentation quality separate a study that holds from one that collapses.

What a Weak Study Can Cost You

When a study fails, the damage is financial and it lands on real people. An owner can face disallowed deductions, audit adjustments, amended returns, and penalties. The savings that looked so attractive get clawed back, often with interest.

The exposure is not limited to the taxpayer. For the attorney, accountant, or banker who recommended the work, a study that falls apart becomes a credibility problem. Protecting a client’s position and your own reputation is reason enough to care about how the study was built.

Red Flags in a Cost Segregation Study

You do not need to be an engineer to spot a questionable study. A few warning signs tend to show up together.

Watch for aggressive classifications with no supporting detail, thin documentation, and templates that treat every property the same. Be wary of pricing that seems disconnected from the scope of work. The IRS specifically flags contingency-fee arrangements and rule-of-thumb allocations, because both create pressure to overstate short-life property. When the report reads like it was built for speed, that is usually what you are getting.

How to Choose Work That Holds Up

Change the question you ask. Instead of who can do this cheapest, ask what protects the position if it is challenged. That reframe points you toward qualified preparers, thorough documentation, and a sound valuation underneath it all.

An independent appraisal is part of that protection. It grounds the study in a defensible opinion of value. The depreciation classifications then rest on solid footing rather than guesswork. When real money and professional reputations are on the line, that footing is worth paying for.

High-Stakes Property? Start With a Defensible Valuation.

PahRoo provides the independent commercial appraisal that a sound cost segregation study is built on. It rests on real analysis and thorough documentation. Talk to us before the numbers get tested.

Speak With Our Team

Frequently Asked Questions

What is a cost segregation appraisal?

It is the independent valuation work that supports a cost segregation study. The study reclassifies building components for faster depreciation. The appraisal establishes the underlying property value and cost allocation it relies on.

Who should perform a cost segregation study?

The IRS expects preparers with expertise in construction, engineering, and tax law. A quality study identifies its preparers and their credentials, which is one reason qualified professional involvement matters.

What makes a cost segregation study defensible to the IRS?

Clear methodology, detailed asset classification supported by analysis, and documentation tied to IRS guidance. The IRS Cost Segregation Audit Techniques Guide describes the elements of a quality study.

What are the risks of a low-quality study?

Disallowed depreciation deductions, IRS audit adjustments, amended returns, and penalties. For advisors who recommended the work, a failed study can also damage professional credibility.

How does an appraiser support cost segregation?

An appraiser provides the independent opinion of value and purchase price allocation that a study is built on. That valuation foundation helps the depreciation classifications rest on defensible ground.

Need a Defensible Commercial Valuation?

PahRoo Appraisal & Consultancy delivers independent, USPAP-compliant valuations for commercial and investment property, led by Michael Hobbs. A cost segregation study, a lender, or a legal matter can all depend on a credible number. Our commercial appraisal team provides that foundation. Explore our full range of appraisal services, or reach us through our contact page to talk through your situation.


Estate planning and probate appraisal for commercial real estate valuation
From Comps to Code in Today’s Commercial Appraisals

For decades, commercial real estate appraisal relied on a familiar foundation: comparable sales, income analysis, and professional judgment informed by local market knowledge. That framework still matters, but it’s no longer the full story.

Across jurisdictions like Cook County, assessment offices are moving away from purely comp-driven reasoning and toward valuation systems built on large datasets, statistical modeling, and automated analysis. The shift is subtle, but its impact is significant.

In today’s environment, commercial appraisals are increasingly evaluated not just on what value they conclude, but on how that value was produced.

Why “Comps” Alone Are Losing Influence

Comparable sales have long been the backbone of commercial property appraisal. They remain essential, but assessors now view them as just one input among many.

Offices such as the Cook County Assessor’s Office are increasingly integrating broader datasets, including federal appraisal and housing data from the Federal Housing Finance Agency (FHFA).

These datasets support:

      • Regression-based valuation models
      • Automated valuation models (AVMs)
      • Market-wide consistency testing
      • Equity and regressivity analysis

When assessments are defended using these tools, appeals based solely on narrative adjustments or limited comps can struggle to gain traction.

What “Code” Really Means in Modern Appraisal

“Code” doesn’t replace appraisal judgment, but it does change how that judgment is scrutinized.

Modern commercial appraisals are increasingly assessed against:

      • Data relevance and scale
      • Transparency of methodology
      • Replicability of conclusions
      • Consistency across property classes

For professionals involved in commercial real estate appraisal for tax appeals, this means valuation credibility now hinges on explaining methodology as clearly as market behavior.

In other words, the appraiser’s role has expanded from market interpreter to valuation explainer.

The New Battleground in Property Tax Appeals

In a data-driven assessment environment, appeals are less about debating opinion and more about evaluating process.

Effective challenges increasingly focus on:

      • Whether model inputs accurately reflect the subject property
      • Whether income assumptions align with real operating realities
      • Whether classification or use errors skew the data
      • Whether equity claims hold up at the property level

This shift doesn’t eliminate comps, it reframes them. Comparable sales now support or challenge model assumptions rather than serving as the sole basis for value.

Why This Shift Extends Beyond Tax Appeals

The move from comps to code isn’t limited to assessment disputes. The same expectations are influencing appraisals used in legal and advisory contexts.

Attorneys working in:

      • Estate planning appraisal
      • Probate real estate appraisal
      • Date-of-death property appraisal
      • Litigation support appraisal

are increasingly focused on whether an appraisal can withstand scrutiny, not just whether it reaches a reasonable number.

For probate attorneys, especially those handling income-producing or mixed-use commercial properties, valuation clarity and defensibility are essential.

Commercial Appraisals in Probate and Estate Planning

Commercial properties involved in estates present layered appraisal challenges: income history, tenancy changes, market conditions at a specific date, and regulatory expectations.

A credible probate appraisal for real estate must:

      • Address the correct valuation date
      • Clearly document data sources and assumptions
      • Explain methodology in plain, defensible terms
      • Align with IRS, court, and professional standards

As data-driven appraisal becomes more common, courts and counsel are less tolerant of appraisals that rely on surface-level analysis without methodological support.

What Attorneys Should Expect from Modern Appraisals

For tax attorneys, probate attorneys, and real estate counsel, today’s commercial appraisals should provide more than a conclusion—they should provide insight.

Key expectations now include:

      • Transparent explanation of valuation methods
      • Clear articulation of data limitations
      • Logical reconciliation of comps and models
      • Defensible reasoning under cross-examination

This is especially critical in expert witness appraisal services, where the ability to explain both market behavior and data-driven analysis can determine credibility.

Why the Shift Will Continue

Assessment offices face increasing pressure to demonstrate fairness, consistency, and accountability. Large datasets and automated models help meet those expectations.

As these tools become standard, commercial appraisals that fail to engage with methodology, not just market value—will feel outdated.

For firms like PahRoo, this evolution reinforces the value of disciplined, well-documented commercial appraisal work across tax appeals, estate planning, and probate matters.

Commercial appraisal hasn’t abandoned comps, but it has moved beyond them.

In today’s environment, the most credible valuations are those that connect market evidence with data-driven reasoning and clearly explain how conclusions are reached.

For property owners, attorneys, and fiduciaries navigating tax appeals or estate-related matters, working with appraisers who understand both sides of that equation—comps and code—is no longer optional. It’s the standard.

Let’s Talk Before the Numbers Are Challenged for You

If your assessment, appeal, or estate valuation is being defended with data models instead of comps, it’s worth a conversation.
Speak with our commercial appraisal team to understand how today’s valuation methods affect your case and how to respond with confidence.


Schedule a Strategy Call

Post-Pandemic Commercial Real Estate Six Years On

Post-pandemic commercial real estate did not return to normal. It repriced. Six years after the 2020 shock, the market has settled into a new equilibrium with different winners and different cap rates. It also left a pile of 2021 and 2022 transaction data that can badly mislead anyone who treats it as current evidence. This is a look at what the reset actually did to values, written from the appraisal side of the table.

By the end of this article, you’ll know:

  • How the reset split winners from losers across office, industrial, and multifamily
  • Why conversions are a highest and best use question, not just a construction project
  • Why 2021 and 2022 comps need special handling, and what owners should do about values now

The Post-Pandemic Commercial Real Estate Reset

Every major disruption resets which properties the market wants. The pandemic did it faster and harder than most. Demand for space did not disappear; it moved. It left commodity office space and flowed toward logistics, housing, and experience-driven retail.

Values followed the demand, but unevenly and with a lag. That lag is where owners get hurt. A building can carry a pre-reset number in its owner’s head, its loan file, or its tax assessment. It can stay there for years after the market has moved on. Six years in, closing that gap between remembered value and current value is the most common reason commercial clients call us.

Office: Bifurcation, Not Extinction

The office story is not one story. Top-tier buildings with strong amenities and locations have held demand as tenants shrink footprints but upgrade quality. Older commodity buildings have repriced hard, and some have repriced below their debt.

The appraisal implication is strict comp discipline. A Class A tower and an aging Class B building three blocks apart are no longer close substitutes. Blending their sales produces a number that describes neither. This is the same market-analysis rigor from our article on commercial appraisals in a shifting market. Here it applies to the sharpest divide the reset created.

Conversions Are a Highest and Best Use Question

The headline response to empty offices has been conversion: to residential, to healthcare, to storage, occasionally to something stranger. From a valuation standpoint, a conversion is not a construction question first. It is a highest and best use question, one of the core analyses in an MAI-level appraisal.

Highest and best use asks what use of the property is legally permissible, physically possible, financially feasible, and maximally productive. When the answer changes from “office” to “apartments,” the entire valuation framework changes with it. Different buyers, different income analysis, different comparables. Owners weighing a conversion, and lenders financing one, need the value analyzed under both uses before committing. Guessing at feasibility is how conversion projects end up in workout.

Industrial and Multifamily Held the Line

Not every sector needed reinventing. Industrial demand, driven by e-commerce and supply chain reshoring, stayed strong through the whole cycle. Multifamily demand held as housing shortages persisted. Still, higher rates and construction costs squeezed development and put pressure on values bought at peak pricing.

Held value does not mean static value. Both sectors repriced as interest rates rose, because cap rates follow financing costs even when tenant demand is healthy. An industrial building can be full, performing, and still worth less than its 2021 number. The rent roll and the value are related, but they are not the same fact.

Handle 2021 and 2022 Comps With Gloves

Here is the technical problem the reset left behind. The 2021 and 2022 transaction wave closed at historically low rates, in a frenzy that no longer exists. Those sales are real data, but they describe a financing environment that vanished. Use them as direct comparables today and the value comes in wrong, usually high.

A competent appraisal treats that era the way it treats any anomaly. Verify the deal terms, adjust for market conditions between the sale date and the effective date, and lean on current income evidence where the sales record is distorted. This is the date-of-value discipline our guide to real estate market cycles walks through. Value has a date on it, and 2021 is not that date.

What Owners Should Do With the New Numbers

The reset cuts both ways, and both directions reward a current appraisal. If your property’s market value has fallen below its assessed value, you may have grounds for a property tax appeal. The appraisal is the evidence that carries it. If a loan maturity or refinance is coming, get the value before the bank does. Lenders follow the Interagency Appraisal and Evaluation Guidelines on when collateral needs a fresh look, and a stale number rarely survives that review. And if you are weighing a sale or a conversion, start with what the property is worth under today’s conditions, not the ones you bought in.

Our commercial appraisal team works these assignments across all five PahRoo markets. That runs from single-tenant industrial to conversion feasibility on obsolete office stock.

Price the Market You Are In, Not the One You Remember

Six years on, the post-pandemic commercial market is no longer in transition. It is the market. The owners doing well in it share one habit: they retired their pre-reset numbers and re-anchored on current evidence. Get the property valued as it stands today, then make the hold, sell, appeal, or convert decision from that number. The market stopped waiting in 2020. The paperwork should catch up.

Find Out What Your Property Is Worth Now

PahRoo’s MAI designated appraisers value commercial property against today’s market, for refinancing, tax appeals, sales, and conversion decisions across Chicago, Dallas, Philadelphia, Phoenix, and Naples.

Request a Commercial Appraisal

Frequently Asked Questions

Have commercial real estate values recovered since the pandemic?

They have repriced rather than recovered. Industrial and multifamily held demand but adjusted to higher rates. Top-tier office held better than commodity office, and older office stock repriced sharply downward. Recovery is the wrong frame; the market found a new level.

Can appraisers still use 2021 and 2022 sales as comparables?

Only with documented market-conditions adjustments. Those sales closed under financing conditions that no longer exist. Treating them as direct evidence of current value usually overstates it. Verified terms and adjusted analysis are required.

What does highest and best use mean for an office conversion?

It is the appraisal analysis that tests whether converting is legally permissible, physically possible, financially feasible, and maximally productive. If the answer changes the use, the entire valuation changes with it, so the analysis belongs before the construction budget.

My building is fully leased. Can its value still have dropped?

Yes. Value reflects both income and the return investors require. When interest rates push cap rates up, the same income supports a lower price. Occupancy protects the income side, not the pricing side.

If my commercial property is worth less now, can I lower my property taxes?

Possibly. If current market value has fallen below assessed value, an appeal supported by an independent appraisal can make that case. The appraisal must value the property as of the assessment date the appeal covers. That is exactly what a retrospective assignment does.

Appraisers Who Priced the Boom and the Reset

PahRoo Appraisal & Consultancy provides commercial and residential appraisals across Chicago, Dallas, Philadelphia, Phoenix, and Naples. Led by Michael Hobbs, our MAI and SRA designated team has valued property through the boom, the reset, and what followed.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712