Tag: rent roll

Request a quote

Our blog

Latest news
& events

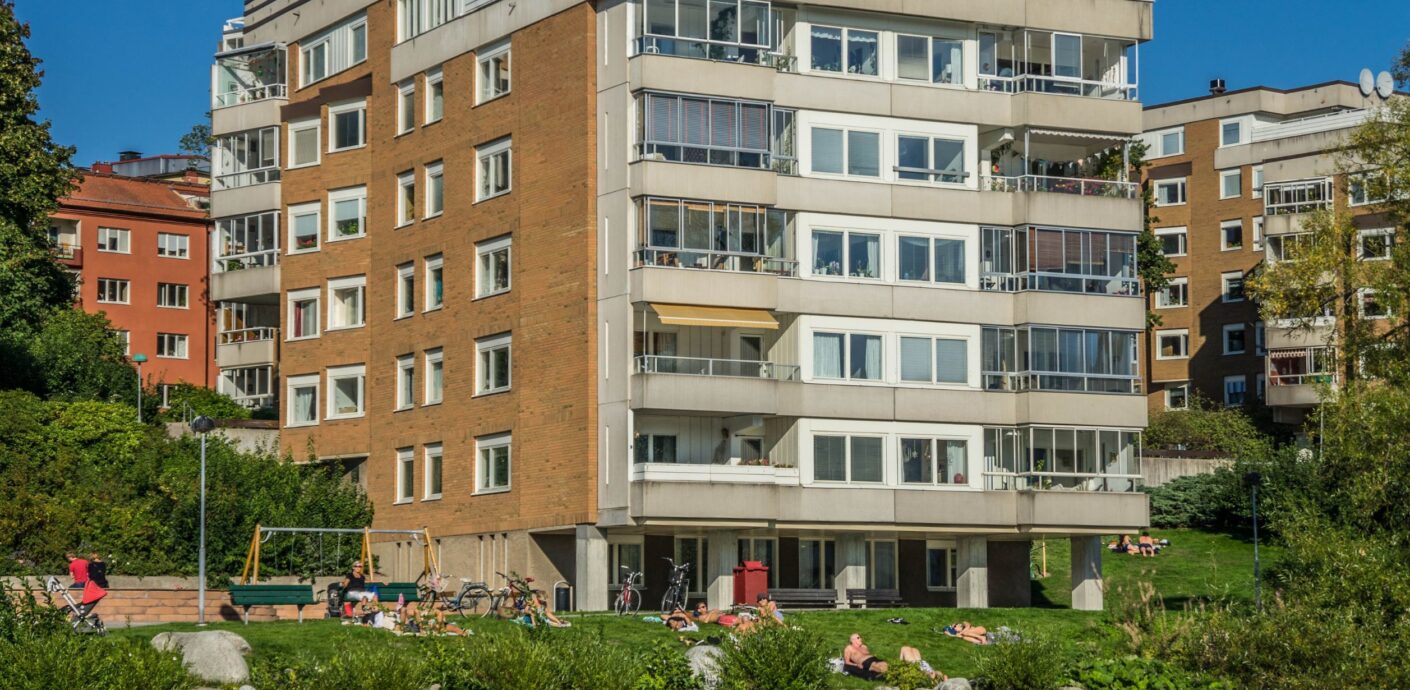
Brick courtyard apartment building in Chicago, the subject of a multifamily appraisal
The Rent Roll Is Where Apartment Value Lives

A multifamily appraisal lands on a lender’s desk with one number on the cover and forty pages behind it. But those pages matter more than the number. An apartment building sells for its rents, so the appraisal stands or falls on the rent roll, the expenses, and the cap rate. If you underwrite apartment loans, those are the pages to read first.

By the end of this article, you’ll know:

  • How a multifamily appraisal turns a rent roll into value.
  • Which rent roll and expense details deserve a second look in the report.
  • What owners can prepare so a refinance appraisal holds up.

How a Multifamily Appraisal Values an Apartment Building

Apartment buildings trade on income, so the income approach carries the most weight. The appraiser estimates what the building should earn in a typical year. Then the cost to run it comes off, and the result converts into value. The sales comparison approach checks that answer against recent apartment sales, usually on a price per unit basis. The cost approach rarely drives the number on an existing building, though it can matter on new construction.

Unit count changes the paperwork too. Under the OCC’s appraisal rule for national banks, a transaction not secured by a single 1-to-4 family residential property counts as a commercial real estate transaction. So a five-unit building falls on the commercial side. The same rule calls for a State certified appraiser on federally related commercial transactions over $500,000. Two- to four-unit buildings still go on the residential Fannie Mae Form 1025, where the income approach is a simple gross rent multiplier. At five units and up, the work usually moves to a full commercial income analysis instead.

The Rent Roll Comes First

The rent roll lists every unit in the building and what each one pays. A usable one shows unit number, unit type, tenant, lease start and end, contract rent, and any concession. It should also flag vacant units, down units, and units set aside for staff. The appraiser checks it against the leases and the trailing twelve months of operating statements. In many assignments, bank deposits get checked too.

Then contract rents get compared to market rents. If in-place rents sit well below market, the building has upside a buyer will pay for, but only with time and turnover. If rents sit above market, that extra income may not survive the next lease cycle. Concessions matter here as well. One free month on a 12-month lease cuts the effective rent by about 8.3 percent, and a rent roll showing only face rent hides that.

From Occupancy to Net Operating Income

Occupancy comes in two versions. Physical occupancy simply counts occupied units. Economic occupancy compares the rent actually collected against the rent the building could earn. A building can be 96 percent physically occupied and still collect far less because of concessions, delinquency, or below-market leases. So the appraiser applies a vacancy and collection loss based on the market and the building’s history, not just today’s snapshot.

Operating expenses get the same scrutiny. Property taxes, insurance, owner-paid utilities, repairs, payroll, management, and replacement reserves all come out before net operating income. Then appraisers usually test each line per unit against comparable buildings. An owner who self-manages still carries a market management fee in the analysis, because a buyer would pay one. We walked through the full build in our guide to net operating income in commercial real estate.

Cap Rate, Price Per Unit, and the Gross Rent Multiplier

Direct capitalization divides one year of stabilized NOI by a market cap rate. That rate should come from confirmed sales of similar apartment buildings, not a national survey. Our explainer on the cap rate in commercial real estate covers where those rates come from. For a building in lease-up or mid-renovation, the appraiser may run a discounted cash flow instead, as our income approach guide explains.

Consider a hypothetical 24-unit building averaging $1,650 a month per unit. That comes to $475,200 a year in potential rent. Add $14,400 in parking and laundry income, then take 5 percent for vacancy and collection loss. Effective gross income lands at $465,120. Subtract $6,800 per unit in expenses, including reserves, and NOI comes to $301,920. At a 6.75 percent cap rate, the indicated value is about $4,470,000, or roughly $186,000 per unit.

Now move the cap rate to 7.25 percent. Same building, same rents, and the value drops to about $4,160,000. Half a point cost more than $300,000. That is why the cap rate support deserves as much attention as the rent roll.

The gross rent multiplier is the quick check. It divides price by gross rent, so it skips expenses entirely. Here, $4,470,000 over $475,200 in annual rent is about 9.4. If similar buildings nearby traded closer to 8 times rent, the appraiser has some explaining to do.

What Lenders Should Check Before Relying on the Number

A lender does not need to redo the appraisal. But a handful of checks catch most problems.

  • Rent roll date. It should sit close to the effective date, and the unit count should match the building.
  • Contract versus market rent. The report should show both and say which one drives the income.
  • Concessions and delinquency. Look for the adjustment, not just the face rents.
  • Expense support. Per-unit expense comparables, a market management fee, and reserves.
  • Cap rate support. Confirmed apartment sales in the same submarket, with the income extracted for each.
  • As is versus as stabilized. If the report gives both, know which one your loan depends on.

The OCC rule also expects appraisals to analyze and report deductions for partially leased buildings and non-market lease terms. That applies directly to a building mid-turnover or full of below-market leases. If the report skips it, ask why.

Where the Apartment Market Sits Right Now

Market data sets the backdrop for those assumptions. CBRE’s Q2 2026 multifamily figures put national vacancy at 4.3 percent, with average rent at $2,257 a month. Net absorption also beat new completions for a second straight quarter. In its release, CBRE said the Midwest led the country in annual rent growth at 2 percent.

Chicago looks tighter than most. Cushman & Wakefield’s Chicago MarketBeat reported 94.9 percent occupancy in Q2 2026, above the 10-year average of 93.8 percent. Effective rents rose 3.2 percent year over year. Still, a metro average does not appraise a 24-unit walk-up in Rogers Park. Instead, the submarket, the building’s condition, and its actual leases decide that.

For Owners: Get the File Ready Before the Appraiser Calls

If you own the building and a refinance is coming, most appraisal delays trace back to missing paperwork. So pull these together before the lender orders the report.

  • A current, dated rent roll with concessions and vacant or down units marked.
  • The trailing 12 months of income and expenses, plus the two prior calendar years.
  • Copies of the leases, or at least a sample, plus any commercial leases in the building.
  • Recent tax bills, the insurance declarations page, and the utility bills you pay.
  • A dated list of capital work, such as roofs, boilers, and unit renovations, with what each cost.

Then reconcile the rent roll to your bank deposits yourself. If they don’t match, the appraiser will find it, and the explanation takes longer later than now. Don’t annualize your best month either. Appraisers work from the trailing twelve months and the market, so an optimistic pro forma won’t carry the value. A clean file won’t raise the number. Still, it keeps an appraiser from discounting the number for uncertainty.

Underwrite the Rent Roll, Not the Offering Memo

An offering memo shows the building at its best. A credible multifamily appraisal shows it the way a typical buyer would see it, with market rents, real expenses, and a cap rate taken from actual sales. So read the rent roll analysis before the value on the cover. If the income holds up there, the number usually does too.

Underwriting an Apartment Loan This Quarter?

PahRoo appraises apartment buildings from the rent roll up, with market rent, expense, and cap rate support your credit team can check line by line.

Request a Multifamily Appraisal Quote

Frequently Asked Questions

How are apartment buildings appraised?

Mainly through the income approach. The appraiser analyzes the rent roll and operating statements, estimates market rent, vacancy, and expenses, and converts net operating income into value with a cap rate drawn from comparable sales. Price per unit and gross rent multiplier comparisons from recent apartment sales serve as a check.

What is a rent roll?

A unit-by-unit list of a building’s tenants and rents. It typically shows unit number and type, tenant, lease start and end dates, contract rent, concessions, and which units are vacant. Appraisers compare it against the leases and operating statements before relying on it.

How does NOI work for multifamily?

Net operating income is effective gross income minus operating expenses. For an apartment building, that means potential rent plus other income such as parking or laundry, less vacancy and collection loss, less taxes, insurance, owner-paid utilities, repairs, payroll, management, and reserves. Debt service is not deducted.

What is a gross rent multiplier?

The ratio of a property’s sale price to its gross rent. Fannie Mae’s Form 1025 for two- to four-unit properties multiplies gross monthly rent by a GRM to indicate value. For larger apartment buildings it works mainly as a quick check on the full income analysis, since it ignores expenses.

How many units make a property commercial?

Under federal bank appraisal rules, a loan secured by anything other than a single one-to-four family residential property counts as a commercial real estate transaction, so five units and up falls on the commercial side. Two- to four-unit properties usually go on residential appraisal forms. Individual lenders may draw their own lines for specific loan programs.

Multifamily Valuation for Lenders and Owners

Every apartment assignment at PahRoo Appraisal & Consultancy starts with the rent roll, across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Our commercial appraisal services page lists the property types we cover. For local scope and timing questions, start with our Chicago appraisal services page.
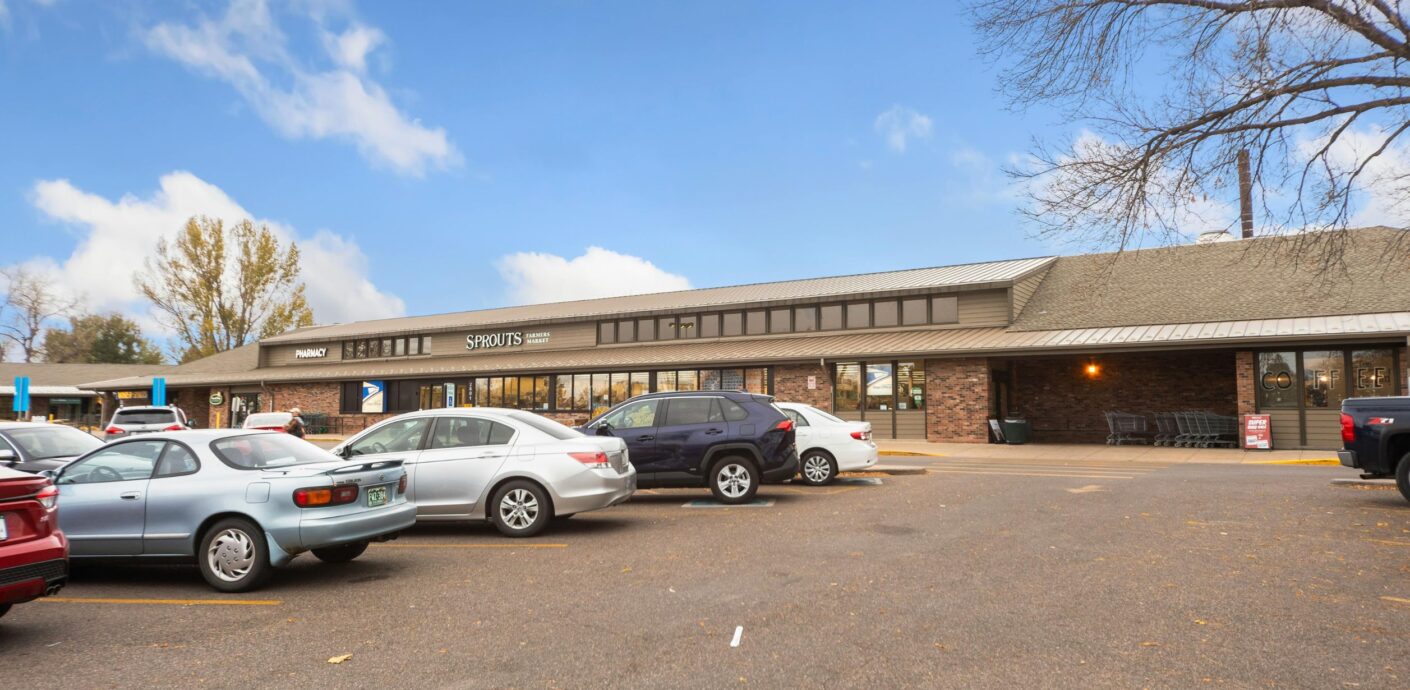
Neighborhood strip center with grocery anchor and inline shops, the subject of a retail property appraisal
Retail Property Appraisal and What Moves the Value

Two strip centers on the same road, same size, same age, same asking price. One is worth 15 percent more than the other, and nothing about the buildings explains why. The leases do. A retail property appraisal spends less time on the roof and the parking lot than brokers expect. It spends far more on who signed the leases, how long they run, and what happens to the rent when they end. So here is how location, tenants, and lease terms each move the number.

By the end of this article, you’ll know:

  • How trade area, access, and co-tenants set the ceiling on retail rent
  • Why tenant credit and tenant category can move a cap rate more than the building does
  • What a rent roll and lease abstract have to show before the appraisal can start

Location Sets the Ceiling

Retail rent is a function of what a tenant can sell from that spot. So the appraiser starts outside the property line. The trade area is the geography a center actually draws from. That may be a one-mile ring for a grocery-anchored neighborhood center, or a 20-minute drive for a destination power center. Population, household income, and daytime employment inside that area tell the appraiser what rent the market can bear. Then traffic counts, visibility, and access decide whether a tenant can capture it.

Co-tenancy matters almost as much as the corner. An inline space next to a strong grocer rents for more than the same space next to a vacant box. The grocer brings the cars. Anchors, shadow anchors across the street, and out-parcel pads all shape the rent an inline tenant will pay. So when the appraiser selects rent comparables, the first filter is not square footage. It is whether the comparable center has the same kind of draw.

Tenants Set the Cap Rate

Once the rent is established, the question shifts to how reliable it is. Two centers with the same net operating income can trade at very different prices. A buyer pays more for income that is likely to arrive. A national credit tenant on a long lease is income a buyer can underwrite. A first-year local operator is a bet. The appraiser reflects that difference in the capitalization rate. In practice, the spread between a credit-anchored center and a local-tenant center can be wider than the spread between a new building and an old one.

Tenant category matters too, and the national numbers show why. The Census Bureau’s July 2026 retail sales release put total retail and food services sales up 5.0 percent from a year earlier. Underneath that headline, nonstore retailers were up 7.7 percent and restaurants and bars were up 5.0 percent. Furniture stores were down 1.2 percent. So a center full of restaurants and service tenants is riding a different current than a center full of furniture showrooms. The appraiser’s vacancy and credit loss assumptions should say so.

Where tenant sales are available, the occupancy cost ratio is the health check. Rent plus recoveries, divided by sales, tells the appraiser whether a tenant can afford its lease. A tenant paying more of its sales than its category can sustain is a renewal risk no matter what the lease says. Most appraisals do not get sales data, though. Then the appraiser leans on category trends and the tenant’s public reporting where it exists.

Lease Terms That Change the Number

This is the section that does the work, and the one most rent rolls are least prepared for. The lease structure comes first. Under a triple net lease, the tenant pays its share of taxes, insurance, and common area maintenance on top of base rent. So the landlord’s net income sits close to the base rent. Under a gross lease, the landlord absorbs those costs, and rising taxes come straight out of net operating income. A modified gross lease splits them. Two centers with identical base rents can have very different net income. That is why our guide to net operating income starts with the recovery structure.

Term and rollover come next. A center where 40 percent of the income expires within 24 months carries costs a fully leased center does not: downtime, tenant improvement allowances, and leasing commissions. The appraiser models those costs in the year they land. So a long-term rent roll and a short-term rent roll with the same current income do not support the same value under the income approach. Renewal options, and whether they are at fixed rent or market, sit inside the same analysis.

Then the clauses that brokers sometimes skip. A co-tenancy clause lets a tenant reduce rent or leave if an anchor goes dark or occupancy drops below a threshold. So one vacancy can cascade. An exclusive-use clause blocks the landlord from leasing to a competing use. That narrows the pool of replacement tenants. Rent escalations, percentage rent breakpoints, and caps on CAM recoveries all change the income stream. None of them show up on a one-page rent roll. All of them show up in value.

What a Retail Property Appraisal Needs From the Rent Roll

A usable rent roll lists every suite with tenant name, square footage, lease start and expiration, and current base rent. It also shows the escalation schedule, recovery structure, renewal options, and any abatement still running. Behind it, the appraiser needs lease abstracts or the leases themselves for anchors and any tenant over about ten percent of the income. Add the last two years of CAM reconciliations and operating statements. Vacant suites need asking rent and the date they went dark.

When that package is complete, the appraisal moves quickly and the conclusions are defensible. When it is missing, the appraiser fills gaps with market assumptions. Market assumptions rarely favor the seller. The same package is what the buyer’s lender will ask for. So assembling it once serves the listing, the appraisal, and the closing.

A Hypothetical Neighborhood Center

Consider a 25,000 square foot center: a 12,000 square foot grocer on a triple net lease with 11 years left, six inline tenants, and one 1,800 square foot vacancy. Net operating income is $504,000. Suppose the inline leases are staggered, with no more than one expiring in any year, and the grocer is a regional credit. An appraiser might support a 7.0 percent cap rate, indicating $7,200,000.

Now change one fact. Four of the six inline leases expire within 18 months, and two tenants are month-to-month. The grocer has a co-tenancy clause tied to inline occupancy. Same building, same income today. An appraiser might now support an 8.0 percent rate, landing near $6,300,000, and deduct lease-up costs on top. The gap is close to $900,000 before those deductions. Every dollar of it lives in the leases.

Where Owners Get Ahead of the Appraisal

For an owner planning a sale or a refinance, the highest-return work happens before the appraiser is engaged. Renew the tenants whose leases expire inside the next two years, even at a modest concession. Term is worth more than the last dollar of rent. Resolve open co-tenancy exposure by backfilling the space that triggers it. Finish the CAM reconciliations so recovery income is documented rather than estimated. And abstract every lease so the rollover schedule, options, and clauses sit in one place. Each step converts an assumption into a fact the appraiser can cite.

Read the Rent Roll Before You Read the Cap Rate

When a retail appraisal lands on your desk, skip the cover value and go to the rent roll analysis. Check that lease structures are identified suite by suite and the rollover schedule is laid out by year. Check that the anchors’ clauses are addressed by name. Then check that the cap rate reflects the tenants actually in the building, not a survey average. If those pieces are there, the value will hold up with the buyer’s lender. If they are not, the number is a guess with a decimal point. Our overview of the three approaches to value shows how the income analysis fits with the others. For retail, it is nearly always the one that decides.

Pricing a Center With Rollover on the Horizon?

PahRoo appraises retail property from the leases up, with rollover modeling and cap rate support a buyer’s lender will accept.

Request a Retail Appraisal Quote

Frequently Asked Questions

How is a retail property appraised?

Primarily through the income approach. The appraiser analyzes the rent roll and leases to establish net operating income, evaluates tenant credit and lease term to select a capitalization rate, and models lease-up costs for expiring or vacant space. Sales comparison serves as a check on the result, and location analysis of the trade area, traffic, and co-tenancy frames the rent the market will bear.

What is a triple net lease and why does it matter to value?

Under a triple net lease the tenant pays its share of property taxes, insurance, and common area maintenance in addition to base rent. The landlord’s net income is close to the base rent and is insulated from rising expenses. Under a gross lease the landlord absorbs those costs, so the same base rent produces lower net operating income and a lower value.

How does tenant credit affect the cap rate?

Buyers pay more for income they are confident will arrive, so a center anchored by a national or regional credit tenant on a long lease supports a lower capitalization rate than a center leased to local operators on short terms. The appraiser reflects that in the rate, and the spread between the two can move value more than the age or condition of the building.

What is a co-tenancy clause?

A lease provision that lets a tenant reduce rent or terminate if a named anchor closes or center occupancy falls below a set level. It means one vacancy can trigger others. An appraiser reads anchor and major tenant leases for these clauses and accounts for the exposure in the vacancy and credit loss analysis.

What does an appraiser need from the rent roll?

Every suite with tenant name, square footage, lease start and expiration, current base rent and escalations, recovery structure, renewal options, and any abatements still running. Behind the rent roll, the appraiser needs lease abstracts or full leases for anchors and major tenants, two years of operating statements, and the CAM reconciliations.

Retail Valuation From the Lease Up

Brokers, owners, and lenders across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples engage PahRoo Appraisal & Consultancy for retail assignments from single-tenant pads to anchored centers. Our commercial appraisal services page lists the property types we cover, and our article on office building value drivers shows the same lease-first method applied to a different asset class. To discuss a retail property, contact our team.

NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712