Tag: Commercial Real Estate

Request a quote

Our blog

Latest news
& events

Partially leased retail strip center being appraised for a commercial refinance
What to Expect From a Commercial Refinance Appraisal

Thinking about refinancing a building you own? Before a lender sets the new loan amount, it needs a supported opinion of what the property is worth today. That is the job of the commercial refinance appraisal, and it shapes how much you can borrow, how much cash you can take out, and sometimes whether the deal works at all.

By the end of this article, you’ll know:

  • How the appraised value sets the size of a refinance loan
  • Who orders the appraisal, and when a new one may not be needed
  • What owners and lenders can do to keep the process moving

How a Commercial Refinance Appraisal Sets Your Loan Amount

Lenders look at two things in a refinance. First, can the property’s income cover the payment? Second, is the building worth enough to secure the loan? According to the Interagency Appraisal and Evaluation Guidelines, the ability to repay comes first. Still, a bank must also consider the value of the real estate behind the loan.

That value usually caps the loan through a loan-to-value limit in the lender’s policy. Consider a hypothetical. A lender caps the loan at 70 percent of value, and your building appraises at $3,000,000. The most it would lend is $2,100,000. If you still owe $2,300,000, you would need to bring $200,000 to closing or find another lender.

So a few percent in value can move real money. That’s why it helps to understand what goes into the number before the appraiser shows up.

Your Lender Orders the Appraisal, Not You

This part surprises a lot of owners. The bank picks and engages the appraiser, and federal guidance says it can’t use a report the borrower ordered. Our article on commercial appraisals for lending covers those independence rules in detail.

For a refinance, the practical point is simple. An appraisal you order yourself can help you decide whether refinancing makes sense before you talk to lenders. It just won’t stand in for the appraisal the bank orders for the loan.

When a Refinance May Not Need a New Appraisal

Some refinances skip the full appraisal. Under the OCC’s appraisal rule at 12 CFR 34.43, an existing loan at the same bank can be refinanced without one in either of two cases. In the first, no new money goes out beyond reasonable closing costs. In the second, nothing obvious and material has changed in the market or the property that threatens the bank’s collateral.

The same rule exempts commercial real estate deals of $500,000 or less. In both cases, though, the bank still needs an evaluation, which is a simpler written estimate of market value. A bank can also order a full appraisal anyway, and the guidelines point that way for higher risk loans.

Two more points matter here. Moving the loan to a new lender takes it outside the existing loan exemption, since that exemption only covers credit already at the lending bank. And a cash-out refinance adds new money, so it qualifies only if the market and the property haven’t materially changed. The FDIC and the Federal Reserve have parallel rules for the banks they supervise, and credit unions follow the NCUA’s version.

What Moves the Value of a Leased Building

For most income property, the appraiser leans hard on the income. Our guide to the income approach shows how rent turns into value. Our explainers on net operating income and cap rates cover the two numbers that drive it.

Leases count too. The federal guidelines require lending appraisals to analyze deductions and discounts for partially leased buildings and non-market lease terms. So a half-empty building, or a big tenant paying well under market rent, will show up in the number.

Time plays a part as well. The guidelines list factors that can make an older appraisal stale, including the passage of time, changes in financing terms, lack of maintenance, and shifts in cap rates and lease terms. In other words, what your building was worth at purchase may not be what a refinance lender sees today.

Who occupies the building matters too. If your own company fills the space, our piece on owner-occupied and investment property appraisals explains why the two get valued differently.

How Owners Can Prepare for the Appraisal

You can’t pick the appraiser, but you can make the work go smoother. Have a current rent roll, every lease with its amendments, recent operating statements, and a list of capital improvements ready before the inspection. Our lending article above has a fuller checklist.

A refinance adds one more step. Find your last appraisal and write down what has changed since. A new roof, a lease renewal at a higher rent, or a tenant who moved out are exactly the facts that decide whether the old value still holds. So hand them to your lender early, before anyone has to ask.

One thing to leave out is a target value. The guidelines tell lenders not to give an appraiser a predetermined value, a loan amount, or a target loan-to-value ratio. For what happens next, see what goes into a commercial appraisal report and how long a commercial appraisal takes.

For Lenders, Set Up the Refinance Assignment Right

Bankers already know the ordering rules, and our lending article covers them. A refinance adds two decisions of its own.

First, decide whether the existing appraisal still holds. The guidelines let a bank use an existing appraisal for a later transaction. However, the credit file should show the facts and analysis behind that call, weighed against the staleness factors listed above. So document the check, even on a renewal with no new money that is exempt from a new appraisal.

Second, match the value premise to the new loan. If cash-out proceeds fund a renovation or a lease-up, the guidelines say a bank would generally ask for the as-is value. As applicable, it would also ask for a prospective value upon completion or stabilization.

If the building sits outside Cook County, our Dallas, Philadelphia, Phoenix, and Naples teams take commercial assignments in those markets. In Cook County, our Chicago appraisal team handles the work.

Planning a Refinance on a Building You Own?

Your lender orders the appraisal behind the loan. If you want a supported value first, to plan or before you talk to lenders, PahRoo can prepare one. Bankers can engage us for refinance assignments too.

Request a Commercial Appraisal Quote

Frequently Asked Questions

What is a commercial refinance appraisal?

It is an appraisal a lender uses to decide how much it will lend on a new loan secured by income-producing or business property. The appraised value usually caps the loan through the lender’s loan-to-value limit.

Can my bank reuse the appraisal from when I bought the building?

Sometimes. A bank can rely on an existing appraisal for a later loan if it documents why the value still holds. The passage of time, lease changes, or a shift in cap rates can make an older value stale.

Does every commercial refinance need a new appraisal?

No. For an existing loan at the same bank, federal rules may allow an evaluation instead when no new money goes out or when the market and property haven’t materially changed. The bank decides which it needs.

What should I have ready for a commercial refinance appraisal?

A current rent roll, every lease and amendment, recent operating statements, and a list of capital improvements. Plan for access to the whole building, including vacant space.

Does a cash-out refinance need a new appraisal?

Not always. At the same bank, a cash-out refinance can skip a new appraisal only if nothing obvious and material has changed in the market or the property. Otherwise it generally needs one, or an evaluation for smaller loans.

Refinance Appraisals That Hold Up in Credit Review

When a lender needs a value it can underwrite, PahRoo Appraisal & Consultancy prepares commercial appraisals for banks, investors, and owners in Chicago and Cook County, Dallas, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, signs our Illinois reports. See our commercial appraisal services for the property types we cover.

Loan officer reviewing a commercial appraisal for lending at a bank office desk.
Commercial Appraisals for Lending and What Banks Require

When a credit officer orders a commercial appraisal for lending, the report has two jobs. It has to support the loan decision, and it has to hold up when an examiner pulls the file. Most of what banks require comes from one set of federal rules and the guidance built on them. So it pays to know where loan files usually come up short.

By the end of this article, you’ll know:

  • When a federally regulated lender needs a full appraisal, and when an evaluation will do.
  • What appraisal independence means for who orders the report and who talks to the appraiser.
  • What credit review should check before the appraisal goes to committee.

What a Commercial Appraisal for Lending Has to Meet

The rules trace back to Title XI of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989, better known as FIRREA. Title XI requires each federal banking agency to set appraisal standards for the institutions it oversees. So when a banker asks for a FIRREA appraisal, they mean a report that meets those agency rules.

Each agency publishes its own version. The OCC’s sits in 12 CFR Part 34, Subpart C, and it sets a clear minimum. The appraisal must follow USPAP, unless safe and sound banking calls for a stricter standard. It must be in writing, with enough analysis to support the decision to make the loan. It must also use the regulation’s definition of market value.

The same rule asks for deductions and discounts where they apply. That covers proposed construction or renovation, partially leased buildings, and leases written below market. Finally, a state licensed or certified appraiser has to do the work. But a credential alone does not prove competency, according to the rule. Experience with the property type counts too.

When an Evaluation Will Do and When It Won’t

Not every loan needs a full appraisal. The rule exempts several kinds of transactions, and three thresholds come up most often.

  • Commercial real estate transactions with a transaction value of $500,000 or less.
  • Business loans of $1 million or less, if repayment does not depend mainly on real estate sales or rental income.
  • Residential transactions with a transaction value of $400,000 or less.

For a loan, transaction value means the loan amount, not the property’s value. And an exempt loan still needs an evaluation of the collateral. The agencies raised the commercial threshold from $250,000 to $500,000 in 2018. Keep that in mind, because the interagency guidance still quotes the older figure.

There is a line on the other end, too. Once the transaction value reaches $1 million, the rule calls for a state certified appraiser.

Consider two hypothetical loans. A $450,000 loan on a small retail building falls under the commercial threshold, so an evaluation would satisfy the rule. A $1.2 million loan on the same kind of building needs a full appraisal by a certified appraiser. Still, an exemption only sets the minimum. The guidance says lenders should consider an appraisal for higher-risk deals even when an exemption applies.

An evaluation still needs substance. The guidance expects it to describe the property and its use, estimate market value as of an effective date, and explain how condition was confirmed. It should also name its sources and, when a person prepares it, identify that person.

Appraisal Independence Starts With Who Orders the Report

The lender or its agent has to engage a fee appraiser directly. The appraiser can have no interest in the property or the deal. Staff appraisers, in turn, have to stay independent of lending, investment, and collection.

The Interagency Appraisal and Evaluation Guidelines go further. If a bank uses an appraisal the borrower ordered or provided, it violates the agencies’ rules. Independence also suffers when the borrower recommends the appraiser, or when loan production staff pick one for a deal.

That does not mean the appraiser works in silence. A lender may share the sales contract on a purchase. It may also ask the appraiser to consider more information about the property or the comps, and to fix factual errors. What it can’t do is push the appraiser, directly or indirectly, toward a number.

Engagement letters belong in the same conversation. The guidance says lenders should use written engagement letters, and work should not start until the appraiser is engaged. A good letter states the intended use and the property interest. It also says whether you need an as is value alone, or prospective values upon completion or stabilization as well.

Using an Appraisal Another Bank Ordered

Participations and loan transfers raise a common question. Can you rely on an appraisal another lender ordered? Under the rule, yes, if another financial services institution engaged the appraiser directly. The appraiser also must have had no interest in the property or the transaction.

Even then, the receiving bank has to review the report as closely as it would its own and document that review. It should also confirm the original lender, not the borrower, ordered it. And it must not accept a report altered to hide the original client.

What Credit Review Should Check Before Committee

Every appraisal used for lending needs a review for USPAP compliance. Reviewers should be independent of the transaction and shielded from loan production staff. A reviewer cannot change the value the original appraiser reached. But a qualified reviewer can develop a second opinion of market value through a USPAP review. In practice, these are the points worth checking first.

  • The approaches. The appraisal has to include each approach that applies and explain any it leaves out. Our guide to the three approaches to value shows how each one works.
  • The income support. On income property, trace the net operating income back to the rent roll and the cap rate back to market evidence.
  • The value premise. For construction loans, banks generally ask for the as is value, plus prospective values if the deal calls for them. Those should rest on current and reasonably expected market conditions.
  • The leases. Vacancy in a partially leased building and leases below market should show up as deductions where they apply.

Those details feed straight into loan sizing. Take a hypothetical building appraised at $2.8 million from $196,000 of net operating income at a 7 percent cap rate. A $1.96 million loan sits at 70 percent loan-to-value. If the market supports 8 percent instead, the same income points to $2.45 million. Then that loan runs at 80 percent of value.

What Borrowers Can Do to Keep the Appraisal Moving

If you own the property or are buying it, you can’t hire the bank’s appraiser. But you can make the assignment faster and cleaner.

  • Tell your lender early if a recent appraisal exists. The guidance lets a borrower point the bank to it, so the bank can request it directly from the lender that ordered it.
  • Have current leases, a rent roll, and two or three years of operating statements ready before the inspection.
  • Pull together the survey, any environmental reports, and a list of recent capital work with costs.
  • Plan for access to tenant spaces, the roof, and mechanical rooms.

Questions about value should go through your loan officer, not to the appraiser. Also ask the lender early about timing and whether you will get a copy of the report. Practices vary from bank to bank, and knowing up front keeps the closing date realistic.

Most Lending Appraisal Problems Start at the Order

A borrower-supplied report or a vague engagement letter causes more trouble than any single comp. Get the order right, and the review tends to go faster. This article summarizes the federal rules in plain terms. How your institution applies them is a question for your compliance team and counsel.

Have a CRE Loan Heading to Credit Committee?

PahRoo prepares USPAP-compliant commercial appraisals with the support a reviewer looks for, from the rent roll to the cap rate.

Request a Commercial Quote

Frequently Asked Questions

What appraisal do banks require for a commercial loan?

A federally regulated bank generally needs a written, USPAP-compliant appraisal from a state licensed or certified appraiser the bank engages directly. Commercial real estate loans of $500,000 or less, and certain business loans up to $1 million, can use an evaluation instead. At $1 million and above, the appraiser must be state certified.

What is a FIRREA appraisal?

It is an appraisal that meets the rules the federal banking agencies adopted under Title XI of the Financial Institutions Reform, Recovery, and Enforcement Act of 1989. Those rules require USPAP compliance, a written report with enough analysis to support the loan decision, the regulation’s definition of market value, and an independent appraiser.

Can a borrower order the bank’s appraisal?

No. Interagency guidance says a lender’s use of a borrower-ordered or borrower-provided appraisal violates the agencies’ appraisal regulations. A borrower can tell the lender that an appraisal already exists, and the lender can then request it directly from the institution that ordered it.

What is the difference between an evaluation and an appraisal?

An evaluation is an estimate of market value allowed for transactions exempt from the appraisal requirement, such as commercial real estate loans of $500,000 or less. It does not have to meet professional appraisal standards or be prepared by a licensed or certified appraiser. An appraisal must meet both.

What is appraisal independence?

It means the appraiser’s judgment stays separate from the lending side of the deal. The lender or its agent engages the appraiser directly, the appraiser has no interest in the property, loan production staff do not pick the appraiser, and no one pressures the appraiser toward a value.

Commercial Appraisals Built for Credit Review

Lenders, owners, and their advisors bring commercial assignments to PahRoo Appraisal & Consultancy across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Our commercial appraisal services page lists the property types we cover. For Chicago-area loans, our Chicago appraisal services page explains how to place an order.


Former church building on a residential block, a common subject of a special use property appraisal
When There Are No Comps for a Mixed-Use or Special Use Building

What do you tell a client who asks what a former church is worth? Or a bowling alley, or a storefront with four apartments upstairs? A special use property appraisal starts where the usual shortcuts stop. There may be no recent sales of anything like it, and no rental market to borrow from. So the report has to show more of its reasoning, and counsel should know where to look.

By the end of this article, you’ll know:

  • What makes a property special use or mixed-use, and why comparable sales fall short.
  • How highest and best use and the cost approach carry the analysis.
  • Which value, interest, and use questions to settle before the engagement letter goes out.

Why a Special Use Property Appraisal Takes More Work

A special use property is a building designed around one purpose. Its layout, structure, or equipment fits that use and little else. Think of a house of worship, a school, a theater, a car wash, a gas station, or a bowling alley. Appraisal texts usually call it special purpose property, but the idea is the same.

The trouble starts with the market. Few buyers want a building they would have to gut, so these properties sell rarely. When one does sell, the price often reflects a conversion or a teardown. Because of that, the sale may say little about what the building is worth in its current use.

So the appraiser widens the search. Sales from other counties or other states may come in, along with older ones. Each needs more adjustment and more explanation. The income approach has limits too, because many of these buildings have no rental market to speak of. Our guide to the three approaches to value explains how each one works on ordinary commercial property.

Highest and Best Use Comes Before Any Number

Every appraisal rests on a use. Highest and best use is the use that passes four tests. It has to be legally permissible, physically possible, financially feasible, and maximally productive. On a special use building, that analysis can decide the whole assignment.

Take a closed church on a residential block. It may be worth the most to another congregation. Or a developer may pay more to convert it to housing, if zoning allows. Sometimes the land is worth more with the building gone. Those are three different values for the same parcel.

The first test is where your work and ours meet. Zoning, a special use permit, legal nonconforming status, deed restrictions, and easements all shape what a buyer can do. The appraiser reports what the analysis relied on. But if the legal status is in doubt, that call belongs to counsel, not to us. In that case the report should state the assumption plainly, so any reader knows what the value depends on.

Federal bank guidance takes the same view. Under the Interagency Appraisal and Evaluation Guidelines, market value should reflect the property’s actual physical condition, use, and zoning as of the effective date. If the highest and best use is redevelopment, demolition and site preparation costs also belong in the analysis.

Where the Cost Approach Earns Its Place

When sales and rents are thin, the cost approach often carries the most weight. It adds land value to the cost of building the improvements new, then subtracts depreciation. On a special use building, depreciation is the hard part.

Physical wear is easy enough to see, but functional obsolescence takes more judgment. A 600-seat sanctuary or a 40-lane bowling center may cost far more to build than the market would pay for it today. That gap has to come off the cost, and the report should say how the appraiser measured it.

Consider a hypothetical single-purpose building. Say the land is worth $600,000 and the improvements would cost $3,200,000 to replace. Physical depreciation of 35 percent takes off $1,120,000. Functional obsolescence then takes off another $480,000. So the improvements contribute $1,600,000, and the cost approach indicates $2,200,000.

In a dispute, that $480,000 line is the one the other side will test. The same goes for the land value, which still comes from sales. The interagency guidelines also expect the appraiser to explain any approach left out. If the report skips sales comparison, it should say why.

Mixed-Use Property Is Several Buildings in One

Mixed-use property has the opposite problem. There is plenty of market evidence, but it belongs to different markets. A building with retail at grade and apartments above answers to retail rents and apartment rents at once. Each part has its own vacancy pattern, expense load, and lease structure.

So the income approach gets built one component at a time. The appraiser estimates net operating income for the retail and for the apartments, then asks who buys the building as a whole. The cap rate should come from sales of buildings with a similar mix. If it can’t, the report should explain how the appraiser blended the rate.

Leases need a close read as well. The interagency guidelines note that a long lease below market rent can make the leased fee worth less than the fee simple. For that reason, the report must state which interest it values.

In Cook County, the mix also drives the tax line. Under the Assessor’s class definitions, revised in December 2024, a mixed-use building with six or fewer units and under 20,000 square feet is Class 2-12. That class sits at a 10 percent level of assessment, while commercial classes sit at 25 percent. Larger buildings can end up split between the two. The Assessor makes that call, but the appraisal still has to model the taxes a buyer would expect.

The Real Estate Is Not the Business

Some special use properties sell as operating businesses. A car wash or a hotel changes hands with its equipment and its customer base. That total is going concern value, and it is not the value of the real estate.

The distinction matters for lending. The same federal guidelines say going concern value, value in use, and value to a specific user may not stand in for market value in a federally related transaction. An appraisal can report them, but only as separate opinions with clear labels.

SBA lending went a step further. In a 2015 notice, SBA said going concern appraisals of special purpose property must allocate separate values to land, building, equipment, and intangible assets. SBA has revised its procedures since then, so confirm the current rule with the lender.

Still, the allocation question comes up in purchase agreements, collateral descriptions, and ownership disputes too. How those pieces get characterized legally is your call. Our job is to support each number.

What Owners and Investors Should Hand the Appraiser

If you own or are buying one of these buildings, the file you hand over shapes the report. So pull these together first.

  • Every commercial lease, plus a rent roll that separates commercial space from apartments.
  • Three years of income and expenses, with shared costs such as taxes and insurance split by component where you can.
  • The certificate of occupancy and any special use permit, variance, or zoning letter.
  • For a single-purpose building, the construction costs or recent contractor bids.
  • A list showing which equipment stays with the building and which belongs to the business.

If your own company occupies the building, put a written lease in place at a rent you can support. Then the appraiser has something to analyze besides your word. Also, before you buy a special use building, price the exit. Ask a contractor what conversion would cost, because the next buyer will ask the same thing.

Settle Four Questions Before the Engagement Letter Goes Out

Most trouble with these appraisals starts before anyone hires the appraiser. So settle four points up front and put them in the engagement letter.

  • Start with the value, whether market value of the real estate, value in use, or going concern.
  • Then name the interest, fee simple or leased fee.
  • Next comes the use, as the property stands today or under a stated zoning or conversion assumption.
  • Finally, fix the date, either today or a past date the matter turns on.

A special use property appraisal that answers those four on page one is far easier to defend. It is also easier to compare when the other side produces its own report.

Drafting Around a Hard-to-Value Building?

PahRoo lays out the highest and best use, the approaches, and any allocation step by step, so counsel can follow how the value was reached.

Discuss Your Commercial Assignment

Frequently Asked Questions

What counts as special use property?

A property built for one purpose, with a design or layout that suits that use and little else. Common examples are houses of worship, schools, theaters, car washes, gas stations, and bowling alleys. Appraisers often call it special purpose property. Because few buyers want such a building as it stands, sales are scarce.

How do you appraise a church or school?

Usually with the cost approach in the lead. The appraiser values the land from sales, estimates the cost to build the improvements new, then subtracts physical wear and functional obsolescence. Sales of similar buildings, often from a wider area, serve as a check. Highest and best use analysis comes first, since conversion or redevelopment may be worth more than continued use.

How is mixed-use property valued?

Mostly through the income approach, built one component at a time. Retail, office, and apartment space each get their own market rent, vacancy, and expense analysis. The appraiser then applies a cap rate supported by sales of buildings with a similar mix, and checks the result against those sales directly.

What is a going concern in appraisal?

It is the value of an operating business together with its real estate, equipment, and intangible assets. Federal bank guidance says going concern value may not be used as market value for a federally related transaction, though an appraisal may report it as a separate, clearly identified opinion.

Why are special use properties hard to value?

They rarely sell, and many have no rental market, so two of the three approaches have little data. The cost approach fills the gap, but it depends on a judgment about how much value the specialized design has lost. That judgment needs clear support in the report.

Appraisals for Buildings That Don’t Fit a Template

Odd buildings are regular work at PahRoo Appraisal & Consultancy. Our MAI and SRA designated team serves Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. See our commercial appraisal services for the property types we cover, mixed-use and special purpose assignments included. Or start with our Chicago appraisal services page for local scope questions.


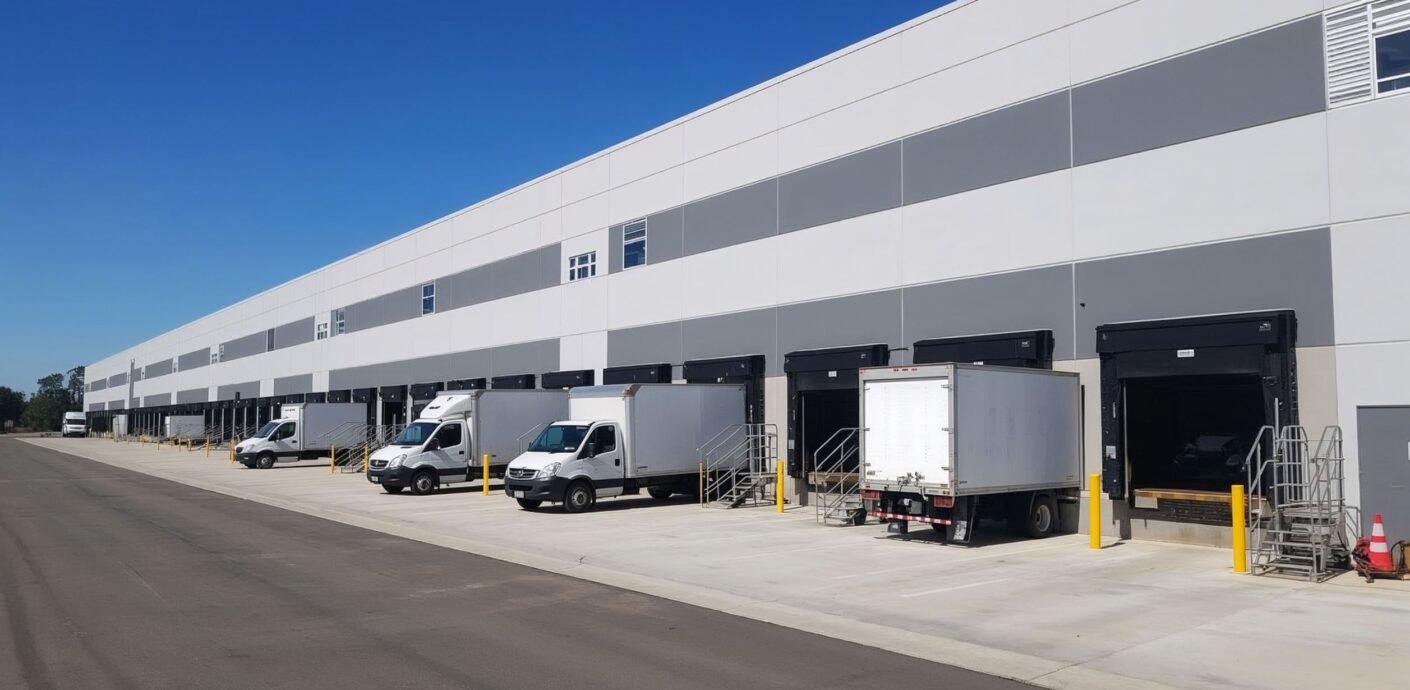
Modern distribution center with loading docks, subject of an industrial property appraisal
What Your Warehouse’s Walls Are Really Hiding

An industrial property appraisal comes down to a simple question. How fast can product move through this building, and how much space does it hold while doing it? Curb appeal barely matters here. A plain concrete box with the right clear height and enough dock doors can out-value a prettier building down the street. Instead, the reason sits in the numbers behind the walls.

By the end of this article, you’ll know:

  • The five factors that carry the most weight in an industrial valuation.
  • Why clear height and dock ratios move value more than square footage alone.
  • What is fueling warehouse and logistics demand right now, and what it means for your number.

What an Industrial Property Appraisal Weighs Most

Five factors do most of the work in an industrial valuation.

  • Location inside the logistics network. Proximity to highways, intermodal rail, and the labor pool that staffs the building.
  • Clear height and functional layout. How much usable cubic space the building offers, not just its footprint.
  • Loading and circulation. Dock door count, trailer parking, and truck court depth relative to building size.
  • Tenant credit and lease structure. Who is paying rent, on what terms, and for how long.
  • Building age and systems. Power capacity, sprinkler class, and the capital needed to bring the space current.

Most industrial buildings, in practice, get valued through a blend of two approaches. Leased distribution centers and multi-tenant parks lean on the income approach. A buyer there is purchasing the rent stream, not just the shell. Owner-user buildings lean harder on the sales comparison approach instead. Appraisers weigh those sales against similar buildings in the same size and height class. The cost approach plays a supporting role too, mostly on newer or purpose-built facilities. Our commercial appraisal services also cover all three, across office, retail, and industrial property.

Income, NOI, and the Cap Rate Behind the Number

For leased industrial, the rent roll gets read closely. Contract rents get compared against market rents. Expirations then get mapped across the holding period, and the reimbursement structure gets checked line by line. Industrial leases run triple net far more often than office leases do. The tenant typically covers taxes, insurance, and most maintenance instead of the landlord. So that keeps the landlord’s expense load lighter, and the income more predictable. That predictability is part of why industrial has held cap rates tighter than office through the same rate cycle. We walked through how that income figure gets built in our guide to net operating income in commercial real estate. The same mechanics apply here. Tenant concentration still matters too. A single-tenant distribution building lives or dies with one renewal decision. So appraisers weigh that risk against the size of the rent check.

Clear Height, Docks, and the Physical Specs That Move Value

Clear height matters more than almost any other industrial spec. It is the unobstructed vertical space from the floor to the lowest hanging obstruction. That obstruction could be a joist, a light, or a sprinkler head. Still, older buildings across the Chicago market commonly top out around 24 to 28 feet. Modern Class A distribution space runs 32 to 36 feet instead. Large e-commerce fulfillment buildings increasingly push past 40 feet to support automated storage systems. That gap is not cosmetic. Moving from a 30-foot to a 36-foot clear height can add 10 to 25 percent of usable storage capacity. It does that without adding a single square foot to the building’s footprint. So appraisers price that extra cubic space directly into value.

Dock doors, trailer parking ratio, and column spacing round out the physical picture. A building with too few docks for its size creates a bottleneck. That bottleneck shows up as functional obsolescence in the appraisal. It happens even when the square footage checks every box on paper. Brokers advising an owner ahead of a listing can get ahead of this instead of explaining it after the fact. Pull the actual clear height and dock count before setting an asking price. Then anchor the comp set to buildings in the same height class, not the metro average. An appraisal that lands under the listing price on an older building usually traces back to a spec gap, not a market swing. So flagging it early keeps the deal from stalling at the lender’s desk.

Why Logistics and E-commerce Demand Is Driving Industrial Value

Industrial has been a standout sector for years. The current data backs that up. According to CBRE’s Chicago Industrial Figures for the second quarter of 2026, the metro’s industrial availability rate fell to 8.6 percent. That is down 30 basis points from the prior quarter. Net average asking rents climbed to $9.30 per square foot, up 7.4 percent year over year. Net absorption jumped to 6.1 million square feet in the quarter. That is well ahead of the 1.1 million square feet absorbed in the first quarter. Another 11.8 million square feet remained under construction, split evenly between speculative and build-to-suit projects.

Nationally, CBRE’s second-quarter research reported the first decline in industrial vacancy since 2022. Demand broadened beyond third-party logistics providers too, as manufacturers picked up a larger share of leasing activity. E-commerce fulfillment, manufacturing reshoring, and tighter big-box supply are feeding the same story from different directions. For an appraisal, that shows up as stronger market rent growth assumptions. In many submarkets, cap rates have also held firmer than other property types through the same financing environment.

The Number Should Match the Building, Not the Market Average

A market average is only a backdrop. Still, it does not appraise your specific building. Two distribution centers half a mile apart can carry very different values. Clear height, dock ratio, and lease structure decide that, not the address. Before a sale, refinance, or partnership buyout, get a number built from the building’s actual specs and tenants instead. After all, a market headline is not a substitute.

Ready to Put a Real Number on Your Industrial Building?

PahRoo appraises warehouses, distribution centers, and manufacturing buildings across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples.

Request a Commercial Appraisal Quote

Frequently Asked Questions

How is industrial property appraised?

Most industrial buildings are valued through a blend of the income approach and the sales comparison approach. Leased distribution centers rely mainly on income, built from the rent roll, market rents, and expenses. Owner-user buildings lean more on comparable sales of similar buildings in the same size and clear height class. The cost approach plays a supporting role, particularly on newer or purpose-built facilities.

What is clear height in a warehouse?

Clear height is the unobstructed vertical space from the floor to the lowest hanging obstruction. Common examples are a joist, a light, or a sprinkler head. Older industrial buildings often run 24 to 28 feet. Modern Class A distribution space commonly runs 32 to 36 feet, and large e-commerce fulfillment buildings increasingly reach 40 feet or more to support automated storage systems.

Why is industrial real estate in such high demand?

E-commerce fulfillment, reshoring of manufacturing, and a slowdown in new construction have kept demand ahead of supply in most markets. CBRE’s second-quarter 2026 research recorded the first national decline in industrial vacancy since 2022. Manufacturers also took a growing share of leasing activity alongside traditional logistics tenants.

What is a distribution center worth?

There is no single number that applies across a market. Value depends on the building’s clear height, dock doors, and trailer parking ratio. It also depends on tenant credit, lease term, and location relative to highways and rail. Two similar-sized buildings in the same submarket can carry very different values once those specs are compared.

How does location affect an industrial appraisal?

Proximity to highway interchanges, intermodal rail, and the local labor pool drives both achievable rent and buyer demand. Submarkets along major logistics corridors typically see tighter vacancy and stronger rent growth than the metro average. Appraisers weigh that submarket-level data rather than a single citywide figure.

Built From the Building, Not the Headlines

PahRoo Appraisal & Consultancy appraises commercial property across five markets. That also includes industrial, office, and retail, for owners, investors, brokers, and lenders. For a similar look at income mechanics in another property type, see our office building breakdown of what drives the value of an office building. Or start with our Chicago appraisal services page for scope and timing questions.

What Drives the Value of an Office Building

An office building appraisal comes down to one question: how reliably will this building produce income, and for how long? Everything the appraiser examines feeds that answer. So when owners ask why two similar-looking buildings carry very different values, the explanation almost always sits in the leases, the tenants, and the submarket rather than the architecture.

By the end of this article, you’ll know:

  • The five factors that carry the most weight in office value
  • How leases, rollover, and tenant credit shape the income analysis
  • Why Class A buildings and older stock are moving in opposite directions

What an Office Building Appraisal Weighs Most

Five factors do most of the work in an office valuation:

  • Occupancy and lease terms: how much space is leased, at what rents, and for how long
  • Tenant credit: the financial strength behind each signature on the rent roll
  • Location and submarket: the vacancy, rent, and demand picture on that block, not the metro average
  • Building class and condition: where the property sits in the flight to quality
  • Market cap rates: what buyers currently pay for a dollar of office income

Office buildings are valued mainly through the income approach, because buyers purchase them for their income streams. The appraiser tests each factor above and translates it into the numbers behind the value.

Income Is the Engine: Leases, Rollover, and NOI

The rent roll gets read line by line. Contract rents are compared against market rents. Expirations are mapped across the holding period, because a building with 40 percent of its leases rolling in two years carries more risk than one with staggered ten-year terms. Rent steps, expense reimbursements, tenant improvement obligations, and leasing commissions all shape the projection.

Those inputs flow into net operating income, and we covered how that number gets built in our guide to net operating income in commercial real estate. For office specifically, the vacancy assumption does heavy lifting. Actual occupancy, submarket vacancy, and realistic downtime between tenants all get weighed rather than assumed away.

Tenant Credit: The Rent Roll Behind the Rent Roll

A lease is only as good as the tenant paying it. Ten years of income from an investment-grade company is worth more than the same rent from a startup, so appraisers consider tenant quality when weighing the durability of income. Concentration matters too. A single-tenant building lives or dies with one renewal decision, while a diversified roster spreads that risk across many decisions.

This is why two buildings with identical NOI can appraise differently. The income may match today, but the probability of it continuing does not, and buyers price that difference.

Building Class, Condition, and the Flight to Quality

The office market is splitting by quality. According to the CBRE Q1 2026 U.S. office market report, overall vacancy stood at 18.6 percent while prime buildings ran at 12.7 percent, and asking rents grew at their fastest pace in six years. Tenants are concentrating in the best space and abandoning the rest.

For the appraisal, class is not a label but a set of measurable traits: systems, amenities, floor plates, energy performance, and the capital spending needed to stay competitive. An older Class B building may need substantial investment just to hold its tenancy, and that cost comes out of value. In some cases, highest and best use analysis even asks whether the building should remain an office at all.

Why Office Values Fell, and How an Appraisal Reads the Recovery

Office values dropped for two stacked reasons. Hybrid work cut demand for space, which pushed vacancy up and rents down in weaker buildings. Then higher interest rates pushed cap rates up, which cut the price of every dollar of income. National vacancy has now edged past its peak and demand has turned positive, but the recovery is uneven across markets and building classes.

That unevenness is exactly why office work demands submarket-level analysis. A metro average tells you little when one corridor is tightening and the next is emptying. Our commercial appraisal services build the value from the property’s actual leases and its actual submarket, so the conclusion reflects your building rather than the headlines.

What is your office building actually worth right now?

In a market moving this unevenly, last year’s number is stale. PahRoo appraises office property from the rent roll up, with submarket evidence a buyer or lender can verify.

Request a Commercial Appraisal Quote

Frequently Asked Questions

What drives the value of an office building?

Occupancy and lease terms, tenant credit, submarket conditions, building class and condition, and market cap rates. These determine how much income the building produces, how durable that income is, and what buyers will pay for it.

How are office buildings appraised?

Mainly through the income approach. The appraiser analyzes the rent roll, compares contract rents to market rents, applies vacancy and expense assumptions, and converts the resulting net operating income into value using market-derived rates, checked against comparable sales.

Why have office building values fallen?

Hybrid work reduced demand for space, which raised vacancy and weakened rents, while higher interest rates pushed cap rates up. Both forces cut value at once. The decline has been uneven, hitting older buildings much harder than prime space.

What is a Class A office building?

The highest-quality tier in a market: modern systems, strong locations, competitive amenities, and creditworthy tenants. Class B and C buildings are older or less competitive. Class is relative to the local market rather than a fixed national standard.

How does vacancy affect office value?

Vacant space produces no income but still incurs expenses, so vacancy reduces net operating income directly. Appraisers also weigh submarket vacancy, because it sets how long re-leasing will take and what rent the space can realistically achieve.

Office Valuation Built From the Rent Roll Up

PahRoo Appraisal & Consultancy appraises office and other commercial property across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, for owners, investors, and lenders. Start with our Chicago appraisal services page, or review our appraisal consulting FAQ for scope and timing questions.

Commercial real estate appraiser in Chicago analyzing Highest and Best Use for property appraisal.
Chicago Commercial Real Estate Appraiser on Redevelopment: Highest & Best Use

An owner calls about a corner building on a Chicago retail strip. The zoning allows five stories. The building is two. The owner wants the appraisal to reflect the three floors that are not there. A commercial real estate appraiser has to answer a narrower question first. Would a buyer pay for them today?

By the end of this article, you’ll know:

  • The four tests behind a highest and best use finding, and why their order decides the answer
  • How a Chicago zoning rule can quietly remove a use an owner assumes is still there
  • What the Cook County Assessor’s commercial model does with use, and where an appraisal pushes back

What a Commercial Real Estate Appraiser Tests Before Pricing Upside

Highest and best use is the reasonably probable use that supports the highest value as of the appraisal date. Four tests get it there, and they run in order.

Legally permissible comes first. Zoning, deed restrictions and other enforceable limits either allow the use or they do not. Physically possible comes second: size, shape, topography, access, utilities.

Financially feasible comes third, and it is the one that does the damage. The use cannot be speculative. Demand has to generate enough income to cover construction and carry the property through its economic life. It also has to deliver a return of the investment and a return on it.

Maximally productive comes last. Among the uses that survive the first three tests, the winner is the one producing the highest residual land value.

Owners usually argue the fourth test while the first three sit unresolved. That is the whole problem. A use has to clear all four, in sequence, before it belongs in an opinion of value.

Chicago Zoning Can Quietly Remove the Use You Think You Have

Plenty of older Chicago buildings run on nonconforming use rights. The use was lawful when it started, the district around it changed, and the use carried on as grandfathered.

Those rights expire. Under Chapter 17-15 of the Chicago Zoning Ordinance, a nonconforming use discontinued for 18 continuous months or more loses its rights. Re-establishing the use is then no longer allowed. Six months is the limit for a nonconforming open use of land. Ceasing operations counts as discontinuance even when the structure and equipment stay put. So does failing to maintain a valid business license.

Expansion gets limited too. A nonconforming business, commercial or manufacturing use in an R district cannot expand without an approved variation. And when a structure holding a nonconforming use suffers intentional damage from causes within the owner’s control, the use does not come back at all.

For valuation that converts a legal question into a money question. A vacant nonconforming building in month 15 is a different asset from the same building in month 19. Before anyone prices a use, somebody should confirm the use still legally exists. Counsel makes that call, not the appraiser, but the appraiser has to ask.

Feasible Means the Numbers Clear, Not That the Zoning Allows It

Zoning that allows five stories grants permission. It does not create demand.

Feasibility asks a harder question. Could a buyer build those floors and still earn a return? That means hard costs and soft costs. It also means the entitlement calendar, carry during construction, lease-up time, and the exit capitalization rate a buyer would underwrite today.

When those numbers do not clear, the extra floors are not value. They are an option nobody is paying to exercise.

This also explains why a use that penciled two years ago may fail now. Construction pricing and financing terms both move, and feasibility moves with them. Buyers pay for what they can finance, so the appraisal follows the financing, not the zoning map.

You Cannot Value the Land One Way and the Building Another

Here is the error that turns up most often in appeal files and broker pro formas. Someone values the site as though it were cleared for redevelopment. Then they add the income the existing building throws off.

Appraisal practice does not permit that. The principle of consistent use requires the site and the improvements to reflect the same use. You get the income of the building standing there. Or you get the land value of a cleared site, less the cost of clearing it. Not both.

The two analyses answer different questions on purpose. One looks at the property as improved. The other looks at the site as if vacant. Demolition becomes the economic answer only when the land value as if vacant exceeds the value of the property as improved.

A transitioning corridor can carry an interim use now and a different ultimate use later. That is a legitimate finding. It is still one use at a time.

How Cook County Values Commercial Property, and Where Use Enters

The Cook County Assessor reviews one third of the county each year. The rotation runs between the City of Chicago, the north suburbs, and the south and west suburbs. Most commercial property goes through a mass-appraisal income model. Market rents, typical vacancy and collection loss, typical operating expenses, then a loaded capitalization rate that carries the tax burden inside the rate instead of in the expense line.

Then the level of assessment applies. Office, industrial and retail typically sit at 25 percent. Multifamily sits at 10 percent. County ordinance sets those levels, so they are not something an appraisal argues about.

Two things follow for anyone weighing an appeal. First, the fight is over market value. A model built from typical rents and typical vacancy can miss a specific building badly. Second, an assessment may appear to carry a redevelopment assumption. Then the appraisal’s job is to show the feasibility work, not to assert that the assumption is wrong.

For counsel, the practical reading is narrow. An appraisal establishes value and documents how it got there. Whether that evidence carries the appeal belongs to the reviewing body and to the lawyers arguing it.

Decide Which Building You Are Actually Selling

Settle three things before you order an appraisal, in this order. Whether the current use is still legally yours. Whether any alternative use clears cost, time and financing. And whether you are asking the market to pay for the building’s income or for the site’s land value.

An appraisal that answers those in sequence survives a review. One that stacks the best answer from each on top of the others does not. Reviewers on the lending side and the tax side both look for exactly that stack.

Is Your Building Priced for a Use That Never Happened?

Send us the property and the story behind it. We will tell you which use the market will actually pay for, and what the file needs to show it.

Get a Commercial Appraisal

Frequently Asked Questions

Does highest and best use always increase property value?

No. Highest and best use is a test, not a premium. It can just as easily support a lower value. A redevelopment scenario that fails the feasibility test carries no weight. In many cases the analysis confirms that the existing use is the highest and best use.

Can the current use be the highest and best use?

Yes, and it often is. If clearing a site and rebuilding costs more than the finished project would return, the building standing there stays the answer. Demolition becomes the economic answer only when land value as if vacant exceeds the property’s value as improved.

What happens to a nonconforming use in Chicago if the building sits empty?

The Chicago Zoning Ordinance treats 18 continuous months of discontinuance as the end of nonconforming use rights. Six months applies to a nonconforming open use of land. Ceasing operations or letting a business license lapse counts as discontinuance. Whether a specific property has crossed that line is a question for a zoning attorney.

Why did my assessment stay high when my building is half empty?

The Cook County Assessor values most commercial property with a mass-appraisal income model. That model uses typical vacancy for similar properties, not a single building’s actual occupancy. Where a property performed worse than typical, that gap is the argument, and it needs documentation rather than assertion.

Does a commercial appraisal help with a Cook County tax appeal?

It gives counsel an independent opinion of market value with the analysis behind it, including the highest and best use finding. What weight it carries in a given appeal depends on the record and the reviewing body. That is your attorney’s territory, not the appraiser’s.

Where PahRoo Fits on a Commercial Assignment

Michael Hobbs, MAI, SRA, signs every PahRoo report. The firm works out of Lincolnwood across Chicago and Cook County. Our commercial appraisal practice covers office, retail, industrial and mixed-use assignments for lending, litigation, estates and tax appeals. There is more on how we approach commercial valuation in a shifting market, and on what our Chicago coverage includes.

Cityscape Overview With Office Buildings And Residential Homes Background
What 2026 Fed Rate Cuts Mean for CRE

Commercial real estate investors, owners, and lenders are paying close attention to interest rate expectations as 2026 comes into view. There’s growing talk about possible Federal Reserve rate cuts, but for CRE, the real issue isn’t simply whether rates go down. It’s whether those cuts will actually make financing meaningfully easier.

That distinction matters. As a recent analysis from Realtor.com points out, lower Fed rates don’t automatically translate into cheaper commercial loans. Even if the Fed eases policy in 2026, mortgage rates, especially on the commercial side, may stay higher than many borrowers expect.

For anyone buying, refinancing, or planning an exit, understanding how Fed decisions actually filter through capital markets can make the difference between a smart move and an expensive misstep.

The 2026 Fed Rate Cut Outlook

Right now, markets are betting on one or two rate cuts in 2026, largely based on expectations that inflation continues to cool and economic growth slows. Those expectations show up in futures markets and investor positioning, but they aren’t guarantees.

It’s also worth remembering that the Fed sets short-term rates. Most commercial real estate loans, especially fixed-rate debt, are priced off longer-term benchmarks. That gap between policy and pricing is where a lot of confusion comes from.

Why Fed Rate Cuts Don’t Automatically Lower CRE Loan Rates

One of the most common misunderstandings in commercial real estate is assuming that Fed cuts lead directly to cheaper loans. In practice, CRE borrowing costs are influenced by several other factors, including:

  • 10-year Treasury yields, which anchor many fixed-rate loans
  • Credit spreads, which widen or tighten based on perceived risk
  • Lender balance sheets and risk tolerance
  • Property-level fundamentals, like occupancy, cash flow, and lease rollover

Even if the Fed cuts rates, lenders may keep spreads wide if uncertainty remains, especially for properties that are transitional, underperforming, or tied to weaker sectors.

Commercial Real Estate Sectors Most Impacted

Office Properties

Office continues to face the most pressure. Higher vacancies, shorter leases, and refinancing risk mean that rate cuts alone aren’t likely to reset values. Lenders are expected to stay cautious, with tighter underwriting and lower loan-to-value ratios.

Multifamily

Multifamily may see more direct benefits from improving rate conditions, particularly for stabilized assets in supply-constrained markets. That said, new deliveries in some areas could limit how much relief lower rates actually provide.

Retail and Industrial

Retail and industrial properties with strong tenants and long-term leases are generally in the best position. For these assets, any improvement from rate cuts is more likely to show up gradually, rather than through a sudden drop in cap rates.

What This Means for CRE Appraisal in 2026

Rates matter, but they’re only part of the picture. In 2026, values will still hinge on fundamentals such as:

  • Stability of net operating income
  • Lease rollover exposure
  • Asset quality and location
  • Lender appetite and available capital

Lower benchmark rates may take some pressure off, but properties with weak fundamentals will continue to face valuation challenges.

Strategic Considerations for CRE Owners and Investors

Why this matters: understanding the gap between Fed policy and real-world lending can help you avoid poor timing decisions.

  • Don’t assume refinancing gets easier just because rates are “supposed” to fall
  • Start planning early for loan maturities in 2026–2027
  • Run conservative scenarios when underwriting or refinancing
  • Use credible, well-supported appraisals when talking to lenders

In this cycle, preparation tends to matter more than predictions.

The outlook for 2026 points to measured optimism, not a rate-driven turnaround. Even if the Fed begins cutting rates, commercial real estate financing will remain selective and highly asset-specific.

For CRE owners and investors, success will depend less on headlines and more on fundamentals, realistic valuations, and proactive planning.

If you’re thinking about refinancing, selling, or approaching a loan maturity, understanding your property’s current market value is critical, especially in a shifting rate environment.

Get clarity before conditions change.

Commercial real estate trends for 2026 translated into appraisal and valuation impact
2026 Real Estate Trends and What They Mean for Your Appraisal

Every January brings a stack of outlook pieces, and most of them stop at the forecast. This one goes a step further. The real estate trends 2026 conversation is anchored by PwC and the Urban Land Institute’s Emerging Trends in Real Estate 2026, the 47th edition of the industry’s benchmark survey, built on input from more than 1,700 investors, developers, lenders, and advisors. The findings are useful. What they mean for your property’s value is more useful, so here is each trend with its appraisal consequence attached.

By the end of this article, you’ll know:

  • The report’s actual findings, with the source linked.
  • How a split market changes what a defensible valuation requires.
  • Where owners should get a number before 2026 decides one for them.

Real Estate Trends 2026 Start With the Office Split

The report describes offices as a divided market. Top-tier buildings in major cities are reaching record rents, while lower-quality and less central properties carry high vacancy, with valuations still well below pre-pandemic peaks. For appraisal work, that split is the whole story. A comp from the wrong tier is not a small error anymore. It points at a different market entirely. So valuations in 2026 live or die on tier discipline: which buildings a subject actually competes with, proven rather than assumed. We walked through the Chicago version of this in our downtown office breakdown, where the same split drives tax appeals.

What does tier discipline look like on paper? Rent rolls and concession data from true peers, not neighbors. Vacancy compared within the tier, not against a citywide average. Then the adjustments get grounded in sales between buildings of the same class. For example, a Class B tower priced against trophy-building rents will look undervalued right up until the loan or the appeal reads the fine print. So the split rewards appraisers who prove the peer group before they price it.

Selective Capital Means Scrutinized Numbers

Respondents expect further rate cuts, and the report frames the mood as cautious optimism while financing costs stay elevated. Meanwhile, recovery is expected to be selective by property class and geography. Translate that into practice. Capital is available but picky, so every deal’s numbers get read harder: by lenders, by investment committees, and by the review bodies that tax the asset afterward. A valuation built on realistic assumptions is now the price of admission, and an optimistic one is a delay generator. For owners whose assessments still reflect a stronger market than their building sees, the appeal process is where that same evidence earns money back.

The practical sequence for owners follows from that. First, test the refinance math on today’s income, not the pro forma. Then compare the assessment to the value the trends imply for your tier and metro. Also, keep the evidence file current, because selective markets punish stale numbers twice: once at the bank and once at the tax bill.

The Hot Niches Are Appraisal-Hard by Design

The report’s growth stories concentrate in specialty assets. Data center vacancy sits below 2%, with most facilities pre-leased before completion. Senior housing reaches record occupancy as the first baby boomers turn 80 in 2026. Self-storage keeps evolving, including storage-condo subsegments. Notice what these have in common: thin comp sets, specialized income streams, and buyers who underwrite operations rather than square footage. So valuing them is income-approach work with documentation behind every assumption. The hotter the niche, the fewer the comps, and the more the value depends on analysis a reviewer can follow. So owners entering these niches should budget for valuation work accordingly. A thin-comp asset without an income file is simply unpriced, and unpriced assets borrow badly, sell slowly, and appeal weakly. The documentation is the asset’s passport into every one of those rooms.

Dallas Tops the List, and the Map Matters

The survey’s markets-to-watch ranking put Dallas-Fort Worth at No. 1 for the second straight year. That is worth a local note, because geography is doing more work in this cycle than usual. Selective recovery means the same building concept performs differently city by city, so portfolio owners need values per market, not a national average. PahRoo values property across its home Chicago market and in Dallas, Philadelphia, Phoenix, and Naples, which makes the cross-market comparison a practical exercise instead of a spreadsheet guess.

Trade the Forecast for a Number You Can Defend

The 2026 trends reward owners who act on specifics. So convert the report’s themes into questions about your own assets. Which tier does the building actually compete in? What do its real income and expenses support? Does the assessment still match the market the trends describe? A documented commercial appraisal answers those questions once, and the answer works everywhere: the refinance, the disposition decision, and the appeal. Forecasts age fast. Evidence holds.

The market split in two. Did your valuation?

Get a 2026 read on your property from appraisers who document which market it actually competes in.

Get My 2026 Number

Frequently Asked Questions

What is Emerging Trends in Real Estate 2026?

The industry’s benchmark annual outlook, published by PwC and the Urban Land Institute. The 2026 edition is the 47th, built on input from more than 1,700 investors, developers, lenders, and advisors across the US and Canada. It was released in November 2025.

Why does the office market split matter for appraisals?

Because top-tier and lower-tier buildings now trade in effectively different markets. A comparable from the wrong tier points the value at the wrong market, so tier selection has become the decisive judgment in office valuation, and in the appeals built on it.

What does cautious optimism mean for property values?

Per the report, respondents expect further rate cuts while financing costs stay elevated and recovery stays selective. In valuation terms, numbers face more scrutiny, not less. Lenders and reviewers reward documented assumptions and discount hopeful ones.

Which sectors does the report highlight for growth?

Data centers, with vacancy below 2% and most facilities pre-leased; senior housing, with record occupancy as the first boomers turn 80 in 2026; and self-storage, including emerging storage-condo formats. All three are specialty assets where valuation runs on income analysis rather than easy comps.

How should an owner act on the 2026 trends?

Turn the themes into asset-level questions: the building’s true competitive tier, the value its real income supports, and whether its tax assessment still matches the market. An independent appraisal answers those once, and the same evidence serves financing, sale decisions, and appeals.

Valuation Across the Markets That Matter

PahRoo Appraisal & Consultancy has valued commercial and residential property for over two decades, from its Chicago home base across Dallas, Philadelphia, Phoenix, and Naples. An appraiser holding both MAI and SRA designations leads the firm. Maybe your 2026 plan needs one asset valued before a refinance. Maybe a portfolio calls for broader appraisal services across markets, or a dispute needs litigation-ready work. Either way, the trends become numbers, and the numbers come documented.


Chicago commercial corridor eligible for Cook County tax incentives
What Cook County Incentives From Class 7 to 8 MICRO Actually Offer

Cook County tax incentives get described in vague superlatives, so here is the actual arithmetic. Most incentive classes assess a property at 10% of market value instead of the standard 25%, which removes 60% of the assessed base for a decade or longer. Also, those are the county’s own published terms, not a sales pitch. The programs cover more ground than most advisors use: commercial projects large and small, grocery stores in food deserts, five south suburban townships, and one 30-year lane most people have never read correctly.

By the end of this article, you’ll know:

  • The real terms of Class 7a through 7d and Class 8, from county sources.
  • What Class 8 MICRO actually covers, which is not what its name suggests.
  • Where the hardship lanes fit, and where valuation work enters.

The Cook County Tax Incentives Map

Per the county’s property tax incentives page, the commercial classes share one schedule: 10% assessment for 10 years, 15% in year 11, 20% in year 12, and all of them are renewable. Class 7a covers commercial projects under $2 million. Then Class 7b covers projects over $2 million. Class 7d covers grocery stores in designated food deserts. Class 8 covers industrial and commercial property in Bloom, Bremen, Calumet, Rich, and Thornton Townships.

Also, two variations round out the map. Class 7c, aimed at newly constructed commercial buildings, runs a shorter clock: 10% for three years, 15% in year four, 20% in year five, renewable. Meanwhile, industrial property has its own lane in the Class 6b, which we covered in detail in our 6b renewal guide. Different doors, same engine: a 60% cut to the assessed base while the incentive holds.

Translate that into one deal to feel the weight. Say a $3 million retail project qualifies for Class 7b. At the standard 25% level, its assessed value is $750,000. At 10%, it is $300,000. So the same levy math that builds every Cook County bill now starts from less than half the base. For example, a lender modeling debt service on the incentive column sees a different project than one modeling the default. That is why the eligibility check belongs in diligence, not after closing.

Class 8 MICRO Is Not What the Name Suggests

The newest class gets misdescribed constantly, so let the county speak. Per the county’s September 2024 release, Class 8 MICRO covers manufacturers of semiconductors, microchips, and associated components, in areas certified as needing substantial revitalization. Also, the terms are striking: a 10% assessment level for 30 years. Still, two caveats matter. It is district-bound, and it is not renewable. So MICRO is a site-selection tool for a specific industry, not a general small-business break, whatever the name implies.

Class 7d Puts Grocery Stores on the Map

The 7d is the county’s food-desert answer, and its terms are the full commercial schedule: 10% for 10 years, then the 15% and 20% steps, renewable. For a grocery operator, that moves store-level economics in a category famous for thin margins. Meanwhile, for a developer, it can turn a marginal site into a fundable one. For the surrounding neighborhood, it is the difference between a vacant box and a produce aisle. So deals like these are where an early eligibility read earns its keep, because the site, the operator, and the municipality all have to line up.

The Hardship Lanes, SER and CEERM

The county’s current list also includes two retention programs. SER, the Sustainable Emergency Relief lane, serves long-term industrial tenants with at least 10 years at the site, documented hardship, and facility age. Meanwhile, CEERM, the Critical Emergency Employee Retention Modification, requires no purchase for value, at least three continuous months of vacancy, and at least 250 jobs at the site. Both exist to keep employers in buildings they might otherwise leave. The eligibility walls are specific, so pull the current forms from the Assessor’s incentives page before assuming a fit.

What Every Class Has in Common

Three threads run through all of these programs. First, municipal support: the resolutions behind these incentives come from village boards and councils, so the political calendar is part of the filing calendar. Then documentation: eligibility runs on records, and the counties audit what they subsidize. Finally, market value: every percentage above applies to a value someone must support. That is where valuation work enters. A documented commercial appraisal anchors the incentive math, and a preliminary review sorts a portfolio before anyone commits. For properties without an incentive, the appeal process remains the other lever on the same bill.

Sixty Percent Is Hiding in Plain Sight

None of these programs are hidden in any real sense. They sit on county webpages with published terms and downloadable applications. Instead, what hides them is habit: advisors quote the standard 25% level because that is the default, and deals get modeled without the incentive column. So run the check early on every qualifying acquisition, development, or retention problem. After all, the classes above move more money than most line items an advisor will ever touch.

Modeling a deal at 25% that could run at 10%?

Get the market value documented before the incentive math, the resolution, or the hearing needs it.

Run My Numbers

Frequently Asked Questions

How much do Cook County incentives cut an assessment?

The main classes assess at 10% of market value instead of the standard 25%, which removes 60% of the assessed base. The level steps to 15% in year 11 and 20% in year 12 on the standard schedule before renewal.

What is Class 8 MICRO?

A 2024 incentive for manufacturers of semiconductors, microchips, and associated components in areas certified as needing substantial revitalization. It holds a 10% assessment level for 30 years and is not renewable. It is industry-specific, not a general small-business program.

What is Class 7d?

The county’s incentive for grocery stores in designated food deserts. It carries the standard commercial schedule: 10% assessment for 10 years, 15% in year 11, 20% in year 12, and it is renewable.

Are the incentives renewable?

Most are. Classes 7a, 7b, 7c, 7d, and 8 are listed as renewable on the county’s incentives page. Class 8 MICRO is the exception: 30 years, one time. Renewals run through the same municipal-resolution machinery as the original filing.

Does the municipality have to support the application?

Yes. These incentives run on resolutions or ordinances from the local government, so municipal support is part of every timeline. Start that conversation early, because a board meeting calendar moves slower than any form.

Valuation Behind the Incentive Math

PahRoo Appraisal & Consultancy has valued Cook County commercial and industrial property for over two decades. An appraiser holding both MAI and SRA designations leads the firm. Maybe an acquisition needs its value documented before the incentive model gets built. Maybe a dispute or estate calls for broader appraisal services, or a hearing needs testimony behind the number. Either way, the value arrives with evidence attached, because every incentive percentage applies to it.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712