Tag: Real Estate Appraisal Insights

Request a quote

Our blog

Latest news
& events

Rows of similar Chicago homes valued together in a Cook County mass appraisal model
Mass Appraisal vs Single Property Appraisal and Why the Numbers Diverge

Every fall, property tax attorneys hear some version of the same question. How can the assessor’s number and the client’s own sense of the property be so far apart? The gap usually comes down to mass appraisal vs single property appraisal, two different methods built for two different jobs. Knowing where they diverge often decides whether an appeal holds up.

By the end of this article, you’ll know:

  • How the Cook County Assessor’s mass appraisal model actually works.
  • Where that model tends to miss a specific property’s true condition or income.
  • When the gap between the assessor’s number and an individual appraisal is worth building into an appeal.

Mass Appraisal vs Single Property Appraisal: What Actually Differs

Mass appraisal and single property appraisal answer different questions. Both aim at market value, but they solve it differently. The International Association of Assessing Officers defines mass appraisal as valuing a group of properties on a single date. The method relies on common data, standardized procedures, and statistical testing across the whole group. It’s built for scale. A single property appraisal is built for one address.

USPAP, the standards that govern the appraisal profession, treats the two as separate disciplines. Standards 1 and 2 cover the development and reporting of a single real property appraisal. Standards 5 and 6 cover mass appraisal instead, with rules of their own for building and testing valuation models. Same governing body, same profession, but two different scopes of work.

In Cook County, that mass appraisal takes the form of a Computer Assisted Mass Appraisal, or CAMA, system. According to the Cook County Assessor’s Office, the model draws on years of sales data. It tests hundreds of model variations against actual sale prices. Then it applies the best performer to every home in the area, sold recently or not. An independent appraisal works the other way. It starts with one property, one inspection, and comparables chosen for that property alone.

How the Assessor Actually Builds Your Number

Cook County reassesses about a third of its townships every year. The cycle rolls on a three-year rotation. Inside each township, the CAMA system groups homes by neighborhood. It pulls in characteristics like square footage, age, land, and construction type. It compares those characteristics against recent sales nearby. Homes that are more similar, or closer geographically, carry more weight in the calculation.

The models started as regression analysis, the traditional mass appraisal tool. They’ve since moved further. The Assessor’s own published code shows the residential and condo models now use a machine learning method called gradient boosting. That method can pick up non-linear patterns a simple regression line would miss. Either way, the code tests hundreds of model versions against actual sale prices before picking a winner. Then it applies that model across the township. Analysts still review the results neighborhood by neighborhood and adjust individual assessments before the notices go out.

Where the Model Runs Out of Room

A mass appraisal model works from what’s on file, and from nearby sales. It can’t see inside a client’s kitchen. Deferred maintenance, an outdated system, or a chopped-up layout usually won’t show up in the model. Storm damage that hasn’t been repaired often goes unreported too. The same goes for the upside. A model built on neighborhood averages can also miss a property that’s actually built or finished better than its comparables.

Commercial property adds another layer. Mass appraisal for income-producing property still leans on area-level income and expense assumptions, vacancy rates, and capitalization rates. A single property appraisal instead works from the subject’s actual rent roll, expenses, and vacancy. That can land in a very different place than the area norm.

CPAs run into this gap from a different angle. If a client’s accountant is using the assessed value for anything beyond the tax bill, look closer. Common examples include a cost segregation study, a basis calculation, or an estate filing. The assessed value is a mass appraisal output, not an opinion of that specific property’s fair market value. Treating it as one can carry the model’s blind spots into a return or a filing where they don’t belong. When that number does more than pay the tax bill, ask whether an independent appraisal should back it up.

What This Means When You’re Building an Appeal

None of this makes the assessor’s number wrong. Mass appraisal is a recognized, widely used method. Cook County publishes self-evaluation reports using measures the International Association of Assessing Officers developed. That means the office holds itself to an outside standard. Still, a mass appraisal output and a single property appraisal are different kinds of evidence. The Board of Review treats them differently, especially given the record filing volumes the office has handled in recent seasons.

Consider a two-flat in a pocket of a neighborhood where the recent comparable sales were newly rehabbed units. The CAMA model might value the subject as though it shares those upgrades, landing at $420,000. A single property appraisal, developed from the property’s actual, unrehabbed condition, might instead support something closer to $340,000. That’s a gap of roughly 19 percent. It’s worth building a case around, not because the model is broken, but because the subject fell outside the model’s view.

The assessed value itself is a useful first filter for whether that gap is worth an appraisal’s cost. If it lines up with what you’d expect from recent sales in that pocket, the model probably did its job. If it doesn’t, that’s usually where mass appraisal’s blind spots and the client’s actual situation intersect. It’s worth documenting before the township’s filing window closes.

Deciding When the Gap Is Worth Documenting

The question isn’t whether mass appraisal is accurate in general. It usually is, since that’s what the method is designed for at scale. The real question is whether it’s accurate for one property, this year, given its condition and its actual comparables. Sometimes the answer is specific to the property, not the neighborhood. That’s the moment for an independent appraisal built to USPAP Standards 1 and 2. The assessor’s own number instead follows township-wide standards. Get that documentation before the appeal window closes, not after.

Test the Assessor’s Number

Sometimes the model’s number and the real property don’t match. An independent appraisal gives you a number built for that property alone.

Get an Independent Value

Frequently Asked Questions

How does the Cook County Assessor value my property?

The Assessor’s Office uses a Computer Assisted Mass Appraisal system. It applies statistical models built from years of sales data and property characteristics. Those models run across every home in a township at once. Analysts then review the results neighborhood by neighborhood.

Why is my assessment higher than what my property would actually sell for?

Mass appraisal relies on recent sales nearby and characteristics on file, not a walk-through of your specific property. Deferred maintenance, an outdated layout, or damage that hasn’t been repaired usually doesn’t show up unless someone reports it.

Is the assessor’s number an appraisal?

No. It’s a mass appraisal estimate, governed by USPAP Standards 5 and 6. A single property appraisal is a separate discipline under USPAP Standards 1 and 2. It’s built around one property’s own inspection and comparables.

How accurate are Cook County assessments?

The Assessor’s Office publishes self-evaluation reports using measures the International Association of Assessing Officers developed. The Illinois Department of Revenue also runs its own sales ratio studies to check assessment levels. Both are aggregate measures, so they can look solid countywide while still missing the mark on one property.

What’s the real difference between mass appraisal and a single property appraisal?

Mass appraisal values many properties at once using shared data and statistical models. A single property appraisal values one property using its own inspection, condition, and comparables. Both aim at market value, but they start from opposite directions.

Property-Specific Work for Property Tax Attorneys and CPAs

PahRoo has built Cook County appeal valuations for over two decades. Each report starts from the subject property’s own condition and comparables, not a countywide model. Michael Hobbs and the appraisal team hold MAI and SRA credentials. They prepare reports to USPAP Standards 1 and 2 for both residential and commercial property. For more on how that documentation supports a filing, see our Board of Review appeal guide. You can also explore PahRoo’s full appraisal services.
Charging Bull sculpture on Wall Street framed by summer sunlight with a slight sun flare, symbolizing market momentum.
Wall Street Summer Sizzle: Navigating the Season’s Market Trends
Summer Slowdowns: What’s Really Happening on Wall Street?

Markets Climb, Trade Tensions Ease, and Blockbuster Deals Lead the Headlines

Wall Street has seen another exciting day, and there are no indications that the markets will slow down anytime soon. U.S. stocks are still rising steadily; SPY is up 0.2%, QQQ is up 0.4%, and IWM is up 0.5%. U.S. Treasury yields are also declining, with the 10-year leveling off at 4.38% and the 2-year at 3.9%. With commodities on a tear—gold up 0.3%, copper up 0.2%, crude oil up 0.6%, and natural gas up an impressive 5.5%—it appears that investors are more than willing to take on a little risk.

As everyone awaits tomorrow’s crucial FOMC meeting, the US dollar (DXY Index) is up 0.4% in the currency market. Bitcoin, meanwhile, is still near its all-time high of $118.8K.

It appears that the controversy surrounding tariffs is finally subsiding on the international scene. Talks with India have been given more time, and today was the second day in a row that the United States has been in Stockholm for trade talks with China. The so-called “tariff hysteria” may finally be waning, according to U.S. Trade Representative Greer. The economic advantages of completed trade agreements and pledges for domestic investment may soon be the focus of attention.

Volatility, Seasonality, and Investor Behavior

Not to be overlooked is earnings season, which never fails to provide enjoyable surprises. As of right now, 32% of S&P 500 companies have released their Q2 earnings; an astounding 77% of them have exceeded consensus EPS estimates, which is significantly higher than the 73% average over the previous four quarters. Additionally, revenues are surpassing projections: 75% of businesses are exceeding estimates, up from 60% in the previous year. Particularly noteworthy are industries like financials, consumer discretionary, and industrials.

Acquisitions and mergers have been booming. Baker Hughes outbid Flowserve with a daring $13.6 billion bid for Chart Industries. Another big story: Union Pacific recently agreed to pay $85 billion in cash and stock to acquire Norfolk Southern. Larger, billion-dollar-plus deals drove a 26% increase in deal value in the first half of 2025, despite a 12% decline in the number of U.S. deals compared to the same period last year. That’s encouraging because it shows that businesses are still self-assured and willing to take calculated risks.

The IPO pipeline is still robust, as if all of that weren’t enough. As they prepare to go public, Stripe and Databricks, two of the most anticipated offerings, are both aiming for valuations above $50 billion.

Overall, as we enter the peak of summer trading, investors have a lot to be hopeful about, including strong equity gains, a calming of trade fears, blockbuster deals, and an IPO calendar to keep an eye on.

Final Thoughts: Riding the Summer Sizzle with Strategy

While Wall Street’s summer movements may seem unpredictable, understanding the trends and the forces behind them can offer a strategic edge. Whether you’re a seasoned investor or just keeping an eye on market rhythms, staying informed is key. If you’re particularly interested in how broader economic shifts are influencing local real estate trends, check out our ongoing Chicago Real Estate Market Insights for in-depth updates.

For a deeper dive into historical summer trading patterns and expert seasonal strategies, we recommend this comprehensive analysis from CNBC’s Market Trends section, a trusted source for up-to-the-minute financial news.

As always, markets may heat up, but smart investing stays cool.

Property Updates That Add Value According to an Appraiser

In Chicago, a new kitchen can come with two bills: the contractor’s and the assessor’s. That second bill surprises people, and so does the four-year tax break that can soften it. Between the city’s century-old housing stock and Cook County’s permit-driven assessment system, the renovations that add value in Chicago follow different rules than the national lists suggest. Here is how an appraiser reads them.

By the end of this article, you’ll know:

  • Which projects pay off in bungalows, two-flats, and greystones specifically
  • How your building permit reaches the assessor, and why 2027 matters
  • How the Home Improvement Exemption shields up to $75,000 of added value for four years

The Renovations That Add Value in Chicago’s Housing Stock

National remodeling lists assume a generic suburban house. Chicago is not that. Much of the city is brick bungalows, two-flats, and greystones built about a century ago, and that stock rewards specific moves.

In the bungalow belt, the money hides above and below the main floor. A dormered attic or a finished basement adds living area to a footprint that cannot grow sideways on a standard city lot. Buyers pay for that space, and appraisers count it when it is permitted and finished to code. In two-flats, the highest-value project is often not cosmetic at all. Bringing a second unit up to legal rental condition adds income the market capitalizes into price.

Age moves systems up the priority list too. In housing this old, updated electrical, plumbing, and roofing carry more weight than they would in a 1990s subdivision, because buyers here price in the risk of hundred-year-old infrastructure. A renovated kitchen sitting on knob-and-tube wiring impresses no one who reads an inspection report. So the national rule holds, only more strongly: function first, then finishes. One more Chicago habit worth keeping: check your own block before budgeting. Values shift street by street here, and the ceiling on a block of frame workers cottages differs from the greystone block two streets over.

The 2026 market raises the stakes on getting this right. Realtor.com’s Market Clock analysis places Chicago among the strongest seller markets in the country this year, with tight inventory across the Midwest. Renovated homes in that environment can command real premiums. But a hot market tempts owners into overbuilding, because everything seems to sell. The block’s ceiling still exists. It just hides better when demand runs high.

Your Permit Is Also a Postcard to the Assessor

Here is the part generic articles skip. In Cook County, building permits flow to the Assessor’s Office, which field-checks the improvement and updates the property’s records. Your renovation reaches the tax roll through the same paperwork that makes it legal. And the timing right now is worth knowing: the City of Chicago is reassessed in 2027 under the county’s triennial cycle, so work finished in 2026 will be on the books when those notices mail.

The wrong lesson to draw is to skip permits. Unpermitted work can be excluded from your home’s finished living area in an appraisal, complicates any sale, and creates exactly the inspection-report risk Chicago buyers already fear. The permit costs you far less than the value it protects. Better to permit the work and use the tax relief the county actually offers.

The $75,000 Tax Break Most Chicago Owners Miss

Cook County’s Home Improvement Exemption lets an owner-occupant improve their home without being taxed on up to $75,000 of the added value for up to four years. No application is required. When the Assessor’s Office receives the building permit and completes its field check, it applies the exemption to eligible properties and mails the owner a notice.

The assessor’s own example makes the math plain. A $100,000 home expands, and the estimated market value rises to $175,000. The added $75,000 is exempt, so the home is assessed as if still worth $100,000 for up to four years. Routine maintenance does not qualify, and the property must be an owner-occupied Class 2 residence. After the exemption period, the added value joins your taxable base. Questions about your specific eligibility belong to the Assessor’s Office or your tax advisor; our lane is the value itself. But every Chicago owner planning a major project should know this program exists before the first wall comes down.

Plan the Project Like an Appraiser Would

Put it together and the Chicago playbook looks like this. Fix the old systems first, because this housing stock punishes deferred maintenance at sale. Add permitted, code-compliant space where your building type rewards it: the attic, the basement, the second unit. Pull the permit, take the exemption, and keep every receipt and sign-off. Then, before committing real money, find out what renovated homes on blocks like yours actually sell for.

A pre-renovation appraisal answers that last question with evidence. It tells you your home’s current value and how much room your block leaves for improvement, so the budget matches what the market will return. In a city where the answer changes every few streets, that is not a luxury. It is the difference between an investment and an expensive surprise.

Renovating a bungalow, two-flat, or greystone?

Find out what your block actually pays for the project you’re planning, from an appraisal firm that has valued Chicago housing stock for over two decades.

Price Your Project’s Payoff

Frequently Asked Questions

Will remodeling increase my property taxes in Chicago?

It can. Building permits in Cook County flow to the Assessor’s Office, which field-checks improvements and updates the property’s assessed value. The Home Improvement Exemption softens this for owner-occupants by exempting up to $75,000 of added value for up to four years, after which the added value becomes taxable.

What is the Cook County Home Improvement Exemption?

It is a program that lets owner-occupants of Class 2 residential property improve their homes without being taxed on up to $75,000 of the added value for up to four years. The Assessor’s Office applies it automatically after receiving the building permit and field-checking the work, so no application is needed.

Should I skip permits to avoid a higher assessment?

No. Unpermitted work may be excluded from your home’s finished living area in an appraisal, creates problems at sale, and raises red flags on inspection reports. Permitting the work and using the Home Improvement Exemption protects far more value than avoiding the assessor ever could.

Which renovations add the most value in Chicago?

In Chicago’s older stock, updated systems come first, since buyers discount homes with century-old wiring, plumbing, or roofs. After that, permitted space additions suit the building type: dormered attics and finished basements in bungalows, and legal second units in two-flats. Value varies block by block, so local comparable sales should guide the budget.

Should I get an appraisal before renovating my Chicago home?

For a major project, yes. A pre-renovation appraisal establishes your current value and shows what renovated homes on similar blocks sell for, so you can size the budget to your street’s actual ceiling before construction starts.

Two Decades of Valuing Chicago’s Bungalows and Two-Flats

PahRoo Appraisal & Consultancy has appraised Chicago-area homes for more than twenty years, led by an appraiser holding both MAI and SRA designations. For the national picture on which projects recover their cost, read our companion piece on property updates that add value, or request a residential appraisal before your next project breaks ground.


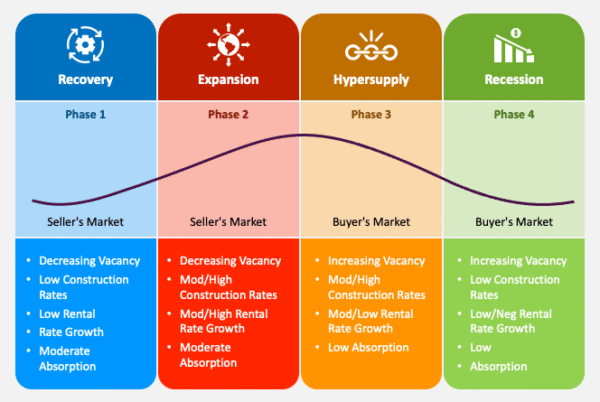
our phases of the real estate market cycle: recovery, expansion, hyper supply, and recession
Real Estate Cycles Explained: The Insider’s Guide to Buying or Selling at the Perfect Time

Real estate does not move in a straight line. It moves through a real estate market cycle, four repeating phases that shape when homes sell fast, when they sit, and when prices swing in your favor. If you are planning a purchase, a sale, or a refinance in Cook County or one of the other markets we serve, knowing where your local market sits in that cycle changes your timing and your negotiating position.

By the end of this article, you’ll know:

  • The four phases of the real estate market cycle and what drives each one
  • Where current data puts the national market, and how Chicago compares
  • Why an appraiser factors cycle position into a defensible valuation

Understanding the Real Estate Market Cycle

Property markets move in patterns of supply and demand, not random swings. Dr. Glenn Mueller at the University of Denver’s Burns School of Real Estate has tracked this pattern across more than 50 U.S. metro areas for decades through his Cycle Monitor research. His work breaks the real estate market cycle into four phases: recovery, expansion, hypersupply, and recession. Every metro area moves through these phases at its own pace, but the sequence itself rarely changes. That consistency is what makes the cycle useful for planning, even though no two markets hit each phase on the same calendar.

The Four Phases and What Each One Means for Your Timing

Recovery

Vacancy is falling from a high point, but rents and prices have not caught up yet. Headlines still sound cautious. This is usually where the best long-term purchases happen, because pricing has not reflected the improving fundamentals. If you can hold a property for several years, recovery rewards patience.

Expansion

Confidence returns. New construction picks up, competition among buyers increases, and prices climb at a steady pace. If you bought during recovery, expansion is often the strongest window to sell or refinance, since demand is outpacing new supply.

Hypersupply

Construction catches up to demand and then overshoots it. Listings sit longer, price growth slows, and the first soft spots appear in specific neighborhoods or property types before they show up in national averages. Sellers should move with realistic pricing here. Buyers should confirm the deal holds up on its own merits, not just on the assumption that values keep rising.

Recession

Demand falls below the level supply can absorb. Prices soften and negative headlines dominate coverage. This phase is uncomfortable to sit through, but it also sets up the next recovery. Buyers with cash and a long time horizon often find their best opportunities here.

Where the Market Sits Right Now

National data from the National Association of REALTORS shows existing home sales still running below pre-pandemic norms in 2026, with inventory improving but not yet back to a balanced five to six months of supply nationally. That points to a market transitioning out of hypersupply in some regions while staying tighter than average in others. Illinois has landed on the tighter side, with home prices up close to 5% year over year even as several Sun Belt states post outright declines. That divergence matters. A market that looks like early hypersupply in Phoenix or Naples can still behave like expansion in parts of Cook County. Our recent look at the Chicago condo market in mid-2026 found the cooling concentrated in the suburbs while the city core held firmer, which is exactly the kind of local divergence a national headline will miss.

If you are weighing a move in Chicago, Dallas, Philadelphia, Phoenix, or Naples, the national cycle position is a starting point, not an answer. Your neighborhood, property type, and price band each carry their own timing.

How Cycle Position Shows Up in an Appraisal

An appraiser does not guess at cycle position from headlines. We track absorption rates, days on market, and the direction of recent comparable sales for the specific property type and price range in question. That data point, not a general sense of “the market is hot,” is what supports a defensible opinion of value under USPAP.

Cycle position also affects Cook County property tax strategy. A property assessed during a hypersupply or recession phase, when comparable sales are softening, often has stronger grounds for a reduction than one assessed at the peak of expansion. If your reassessment notice landed during a cooling window, it is worth reviewing whether the assessed value still reflects current market conditions. Our 2026 Cook County reassessment guide walks through how that evidence gets built into an appeal.

Know Your Local Phase Before You Move

National forecasts are a decent starting point, but they will not tell you what is happening on your block. Before you list, buy, or refinance, get an opinion of value grounded in your specific neighborhood’s cycle position, not a national average. That is the difference between a decision based on data and one based on a headline.

Get a Cycle-Informed Valuation Before You List or Buy

PahRoo appraisers track local absorption and comparable sales trends across Chicago, Dallas, Philadelphia, Phoenix, and Naples, so your valuation reflects where your market actually stands, not a national headline.

Request Your Appraisal

Frequently Asked Questions

What are the four phases of the real estate market cycle?

Recovery, expansion, hypersupply, and recession. Recovery is the trough where vacancy is falling but prices lag. Expansion brings rising demand and new construction. Hypersupply is when new supply overshoots demand and listings linger. Recession is when demand falls below what supply can absorb and prices soften.

How can I tell what phase my local market is in right now?

Look at absorption rate, days on market, and the direction of recent comparable sales for your specific property type and neighborhood. National data sets the broad backdrop, but local trends can run a full phase ahead of or behind the national picture.

Is 2026 a buyer’s market or a seller’s market?

It depends heavily on location. National inventory is still below pre-pandemic norms, but Sun Belt states like Florida and Arizona are seeing price declines while Illinois and parts of the Midwest are still posting price gains near 5% annually. Ask about your specific submarket rather than relying on the national average.

Does an appraiser account for market cycle position in a valuation?

Yes. A USPAP-compliant appraisal weighs absorption trends and recent comparable sales for the property’s specific type and price range, which reflects where that submarket sits in the cycle rather than relying on general market sentiment.

Does market cycle timing matter for a Cook County property tax appeal?

It can. A property assessed near the peak of expansion may carry a higher value than current comparable sales support if the market has since cooled toward hypersupply or recession. A current, well-documented appraisal helps show whether the assessed value still matches market conditions.

Need an Independent Appraisal?

Whether you are timing a sale in residential real estate, weighing a commercial acquisition, or reviewing a Cook County reassessment notice, PahRoo Appraisal & Consultancy can give you a valuation grounded in current, local market data. Contact us to talk through your specific situation.

Luxury home interior representing a luxury real estate appraisal assignment
Luxury Real Estate Appraisal as the Buyer Pool Changes

Walk into a high-end open house today and the buyers look different than they did a decade ago. Younger, more often women buying on their own, and asking about smart systems instead of formal dining rooms. That shift changes more than marketing. It changes what a luxury real estate appraisal has to measure, and it is about to make documented values matter more than ever, because the largest wealth transfer in history is moving property along with the money.

By the end of this article, you’ll know:

  • Who the new luxury buyers are, and how much wealth is heading their way
  • Why high-end homes are the hardest properties to value, and where online estimates fail
  • Why the wealth transfer itself creates appraisal needs for estates, gifts, and trusts

The Buyers Are Changing, and So Is Luxury Real Estate Appraisal

For years, the top of the market belonged to Baby Boomers and Gen X. That is ending. Roughly $124 trillion in assets is projected to change hands through 2048, with about $106 trillion going to heirs, mostly Gen X, Millennials, and Gen Z, according to Cerulli Associates research summarized by Merrill and Bank of America Private Bank. Some of that inheritance arrives as cash that buys homes. A lot of it arrives as the homes themselves.

For a luxury real estate appraisal, the buyer pool is not trivia. Value is what the probable buyer would pay, so when the probable buyer changes, the analysis has to follow. An appraiser who still assumes a 1998 buyer profile will misread what today’s market rewards and what it ignores.

Why Luxury Homes Are the Hardest to Value

High-end properties break the tools that work everywhere else. Automated estimates lean on volume and similarity, and luxury homes offer neither. Sales are few, features are custom, and no two properties match. A $400,000 house might have a dozen recent comps within a mile. A $4 million house might have three loosely similar sales in a year, spread across neighborhoods.

So the appraiser has to work harder. That means widening the search area with care, verifying the terms behind each sale, adjusting for one-of-a-kind features with market support, and accounting for longer exposure times at the top of the market. This is the segment where designations and experience separate a defensible residential appraisal from an expensive guess.

What the New Buyers Pay For, and What They Do Not

Younger luxury buyers consistently favor smart-home technology, wellness spaces, energy performance, and turnkey condition. Sellers hear that and assume every upgrade returns its cost. The appraisal answers a colder question: what does the market actually pay for the feature?

Some of these amenities now carry real contributory value in the right submarkets. Others read as personal taste that the next buyer will renovate away. The discipline is the same one we described for green property features: cost is not value, and market evidence decides. In luxury, where a single feature can represent six figures, that distinction gets expensive to ignore.

Women Are a Growing Share of the Buyer Pool

The other structural shift is who holds the wealth. Women in the United States are projected to control about $34 trillion in assets by 2030, roughly 38 percent of the total, per McKinsey research. More high-end purchases are made by women buying independently, often through trusts or after a divorce or inheritance.

Those purchase paths share a common need: an independent value nobody can argue with. Trust purchases, divorce settlements, and estate distributions all put the number under scrutiny from trustees, attorneys, or courts. The appraisal is what keeps that scrutiny short.

The Wealth Transfer Is an Appraisal Event

Here is what the trend coverage misses. Every luxury property that passes between generations needs a documented value at the moment it moves. Estates need date-of-death values to set basis and settle fairly among heirs. Gifted property needs a supportable value for the paperwork the family’s CPA will file. Homes placed in trusts need values for funding and accounting. The tax mechanics belong to a CPA, but the value itself is appraisal work, and it has to hold up years later if anyone asks.

Families who handle this well get the appraisal at the time of transfer, not five years later when a dispute or an audit forces a retrospective reconstruction. With this much property set to change hands, the cheapest insurance in estate planning is a current, well-documented value from a qualified appraiser. Our estate planning appraisal work exists for exactly this moment.

Get the Value Documented Before the Asset Moves

If you own, advise on, or expect to inherit high-end property, the order of operations matters. Appraise before the transfer, before the listing, and before the settlement talks, while the facts are fresh and the market data is current. The new luxury market rewards buyers and families who know their number. It punishes the ones who guess.

Put a Defensible Number on a High-Value Property

PahRoo’s MAI and SRA designated appraisers value luxury and estate homes for purchases, trusts, estates, and settlements across Chicago, Dallas, Philadelphia, Phoenix, and Naples.

Request a Luxury Home Appraisal

Frequently Asked Questions

Why is a luxury home harder to appraise than a typical house?

Because comparable sales are scarce and the properties are one of a kind. The appraiser must widen the search, verify each sale’s terms, and support adjustments for custom features, which takes more skill and more market evidence than a standard assignment.

Can I rely on an online estimate for a high-end property?

No. Automated models depend on many similar recent sales, which luxury markets rarely provide. Estimates at the top of the market routinely miss by wide margins, in either direction, and carry no weight with courts, trustees, or the IRS.

Do smart home and wellness features increase appraised value?

Sometimes. The appraiser measures contributory value, meaning what buyers in that submarket actually pay for the feature, which is often less than installation cost. Well-documented, market-supported features fare best.

When does inherited or gifted property need an appraisal?

At the time of transfer. Estates typically need a value as of the date of death, and gifts need a supportable value for the related filings. Getting the appraisal when the property moves avoids a costlier retrospective reconstruction later. The tax treatment itself is a matter for your CPA.

How long does a luxury home appraisal take?

Longer than a standard assignment. The inspection alone can take several hours for a large custom home, and the research and reporting often run one to two weeks depending on how thin the comparable data is. Complex properties reward starting early.

Need an Independent Appraisal?

PahRoo Appraisal & Consultancy values luxury, estate, and unique residential properties across Chicago, Dallas, Philadelphia, Phoenix, and Naples. Led by Michael Hobbs, our MAI and SRA designated team delivers appraisals built to satisfy trustees, attorneys, and courts, not just curiosity.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712