Category: Commercial Appraisals

Request a quote

Our blog

Latest news
& events

Commercial real estate appraisal of a multi-tenant office building in Chicago
Commercial Real Estate Appraisal: When You Need One

A commercial real estate appraisal puts a defensible value on a property when real money rides on the number. Banks want one before they lend. The IRS wants one when an owner dies. Buyers, sellers, and partners heading for a split want one too. The work follows federal standards, and the report holds up under scrutiny because of it.

By the end of this article, you’ll know:

  • What a commercial appraisal measures, and how appraisers actually arrive at a value
  • Why the property type changes the whole analysis
  • The situations that call for one, from lender financing to a Cook County tax appeal
  • What drives the cost and turnaround, so you can plan around it

What a Commercial Real Estate Appraisal Measures

A commercial real estate appraisal is an independent opinion of value, prepared by a state-certified general appraiser under the Uniform Standards of Professional Appraisal Practice (USPAP). The appraiser inspects the property, studies the market, and supports the value conclusion with evidence.

This is not a home inspection. It also is not a broker’s price opinion, which a real estate agent can hand you for free. An appraisal carries more evidentiary weight, so courts, lenders, and tax authorities accept it. Residential appraisals lean mostly on recent home sales nearby. Commercial work runs deeper, because income, leases, and tenant quality all move the value.

The Three Ways Appraisers Reach a Value

An appraiser develops up to three approaches to value, then reconciles them into a single conclusion. For commercial property, one approach usually carries most of the weight.

The income approach estimates value from the rent a property produces. The appraiser starts with net operating income, which is gross rent minus vacancy and operating expenses. Then the appraiser divides that income by a capitalization rate pulled from comparable sales. A building with $200,000 in net operating income and a 7% cap rate points to a value near $2.86 million. A lower cap rate signals a lower-risk, higher-value asset. This method drives value for most income-producing property.

The sales comparison approach weighs recent sales of similar buildings, with adjustments for size, location, and condition. The cost approach estimates what it would take to rebuild, minus depreciation, plus the land value. It matters most for special-purpose or newly built property, where comparable sales are thin.

Why the Property Type Changes the Whole Analysis

The property type decides which data the appraiser leans on. A warehouse and a hotel do not get valued the same way, even at the same price point.

Office and retail values hinge on the leases. Lease length, rent levels, and the credit quality of the tenants all feed the income approach. A retail center anchored by a strong national tenant reads very differently from one with month-to-month locals.

Industrial and warehouse values turn on ceiling height, loading access, and proximity to highways and rail. Multifamily property with seven or more units gets treated as commercial, so the appraiser studies the rent roll and the unit mix. Hotels, gas stations, and self-storage are special-purpose properties. They often carry a business value on top of the real estate, and they need an appraiser who knows the category. So the right question is not just “what is it worth,” but “who is qualified to value this kind of asset.”

Appraisal or Evaluation: What Your Lender Actually Needs

An appraisal and an evaluation are not the same document, and the difference can change your timeline. Financing is the most common reason a commercial appraisal gets ordered.

Federal rules under FIRREA require an appraisal for most federally related transactions. For commercial property, the threshold sits at $500,000, raised from $250,000 in 2018. You can read the regulation itself in 12 CFR Part 323. Below that line, a bank can rely on a lighter “evaluation” instead. An evaluation costs less and turns around faster, but it does not meet USPAP and carries less weight.

There is also a business-loan carve-out. A loan of $1 million or less can skip the appraisal if the real estate is not the primary source of repayment. SBA financing usually calls for a full appraisal once the deal clears the program’s own limit. So if you are borrowing against commercial property above these thresholds, expect the lender to order one. Our commercial valuation work often starts with exactly this kind of request.

When You Need One Without a Bank in the Room

Plenty of appraisals have nothing to do with a loan. Any time a value carries legal or financial consequences, a USPAP appraisal earns its place.

Estate and gift tax. When an owner dies, the IRS wants a value as of the date of death. A qualified appraisal protects the estate if the return gets questioned later, and it supports a stepped-up basis for the heirs.

Divorce and partnership splits. When co-owners separate, someone has to value the real estate fairly. A neutral appraisal keeps the split from turning into a fight over numbers.

Litigation and financial reporting. Bankruptcy, eminent domain, and partner disputes all rely on a credible value. Companies also need appraisals to carry property correctly on their books.

Using an Appraisal in a Cook County Tax Appeal

A current appraisal is some of the strongest evidence you can bring to a commercial property tax appeal. In Cook County, the stakes are higher for commercial owners by design.

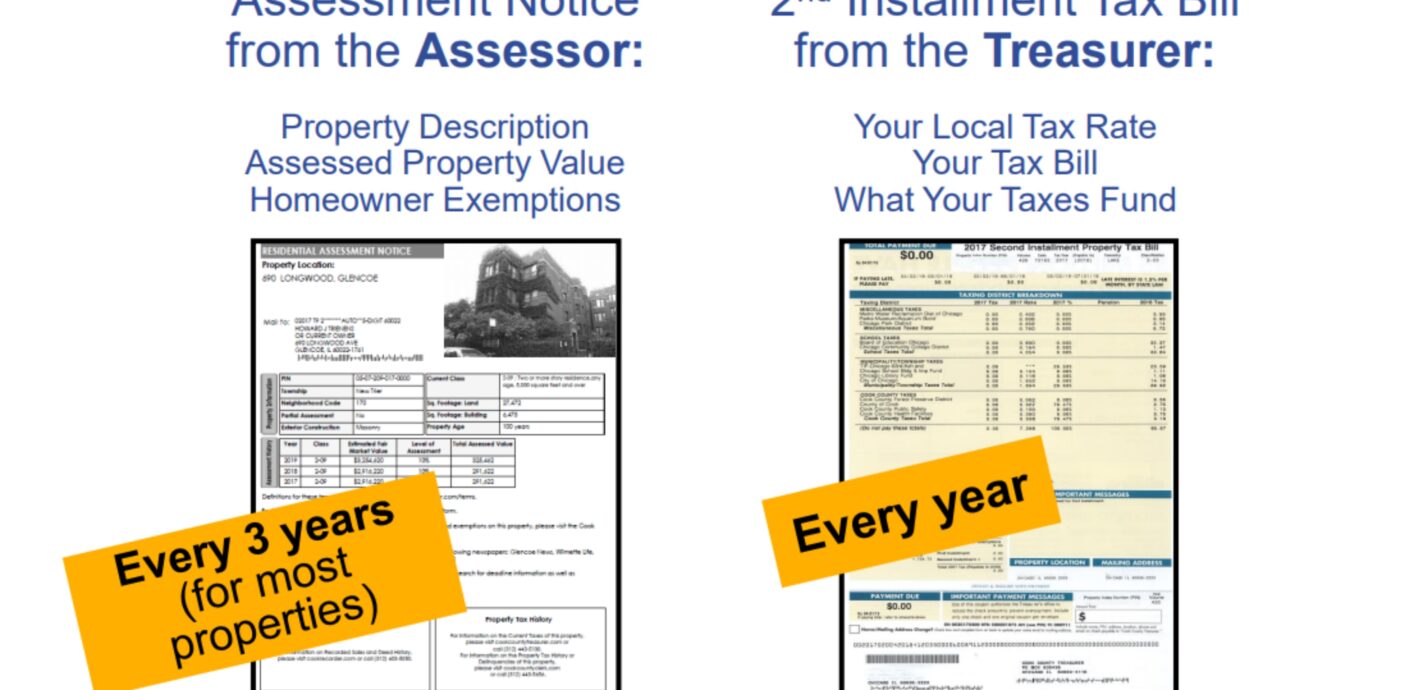
The county assesses most commercial and industrial property at 25% of fair market value, against 10% for homes (see the Cook County Assessor). So an inflated value hits a commercial owner harder than a homeowner. The county reassesses on a triennial cycle, split into three districts: the City of Chicago, the north suburbs, and the south and west suburbs. Each one gets reassessed every three years.

Timing matters here. A reduction you win in a reassessment year holds for the full three-year cycle, so that year is the one to watch. There are three levels of appeal: the Assessor’s Office, the Cook County Board of Review, and then the Illinois Property Tax Appeal Board or the Circuit Court. An appraisal is accepted evidence at each level.

At the Board of Review, a corporation has to be represented by an attorney. So commercial appeals usually pair a tax attorney with an independent appraisal. A well-supported appraisal shifts the discussion from opinion to documented analysis, and a documented value is harder for the county to wave off. Our Cook County reassessment work is built around exactly that.

What the Report Looks Like and What It Costs

USPAP allows two report formats, and the cost tracks the complexity of the property. An Appraisal Report lays out the full analysis. A Restricted Appraisal Report is shorter and meant for the client alone, so it works only when no third party will rely on it.

A small retail building might take a week or two. A complex mixed-use site with many tenants takes longer and costs more, because the analysis goes further and the data takes longer to gather. Ask for the report type and the timeline up front, so the appraisal fits your deadline rather than blowing past it.

How to Tell If You Really Need One

Use a simple test. If money, taxes, or a legal outcome turns on the value of a commercial property, get a USPAP appraisal rather than a rough estimate. A broker’s opinion can guide a listing price. It will not hold up in front of a judge, an assessor, or the IRS. When the number has to defend itself, the appraisal is what does the defending.

Put a Defensible Number on Your Property

PahRoo prepares commercial appraisals across the Chicago and Dallas markets for financing, tax appeals, estates, and disputes. Tell us the property and the purpose, and we will scope it for you.

Request a Commercial Appraisal

Frequently Asked Questions

How much does a commercial real estate appraisal cost?

Cost depends on the property type, size, and complexity. A simple building runs lower, while a multi-tenant or special-purpose property costs more because the analysis takes longer. Ask for a quote tied to your specific property and its intended use.

How long does a commercial appraisal take?

A straightforward property often takes one to two weeks. Larger or more complex assignments take longer, since the appraiser has to gather lease data, income records, and comparable sales before reaching a conclusion.

What is the difference between a commercial appraisal and a broker price opinion?

A broker price opinion is an agent’s informal estimate, often free, and it carries little evidentiary weight. A commercial appraisal follows USPAP and comes from a state-certified general appraiser, so lenders, courts, and tax authorities accept it.

Do I need a commercial appraisal for a property tax appeal in Cook County?

You do not always need one, but a current appraisal is strong evidence at the Board of Review or the Illinois PTAB. It gives you an independent value to counter the assessor’s figure, which can improve your odds on a commercial parcel. Note that a corporation must be represented by an attorney at the Board of Review.

Who is qualified to perform a commercial real estate appraisal?

A state-certified general appraiser is qualified to value commercial property. This is the highest appraisal credential, and federally related transactions require it. Make sure your appraiser holds the general certification rather than a residential license.

Need an Independent Appraisal?

PahRoo Appraisal & Consultancy provides commercial valuations along with estate, divorce, and property tax appeal appraisals in the Chicago and Dallas markets. Reach out when you need a value that stands up to scrutiny.
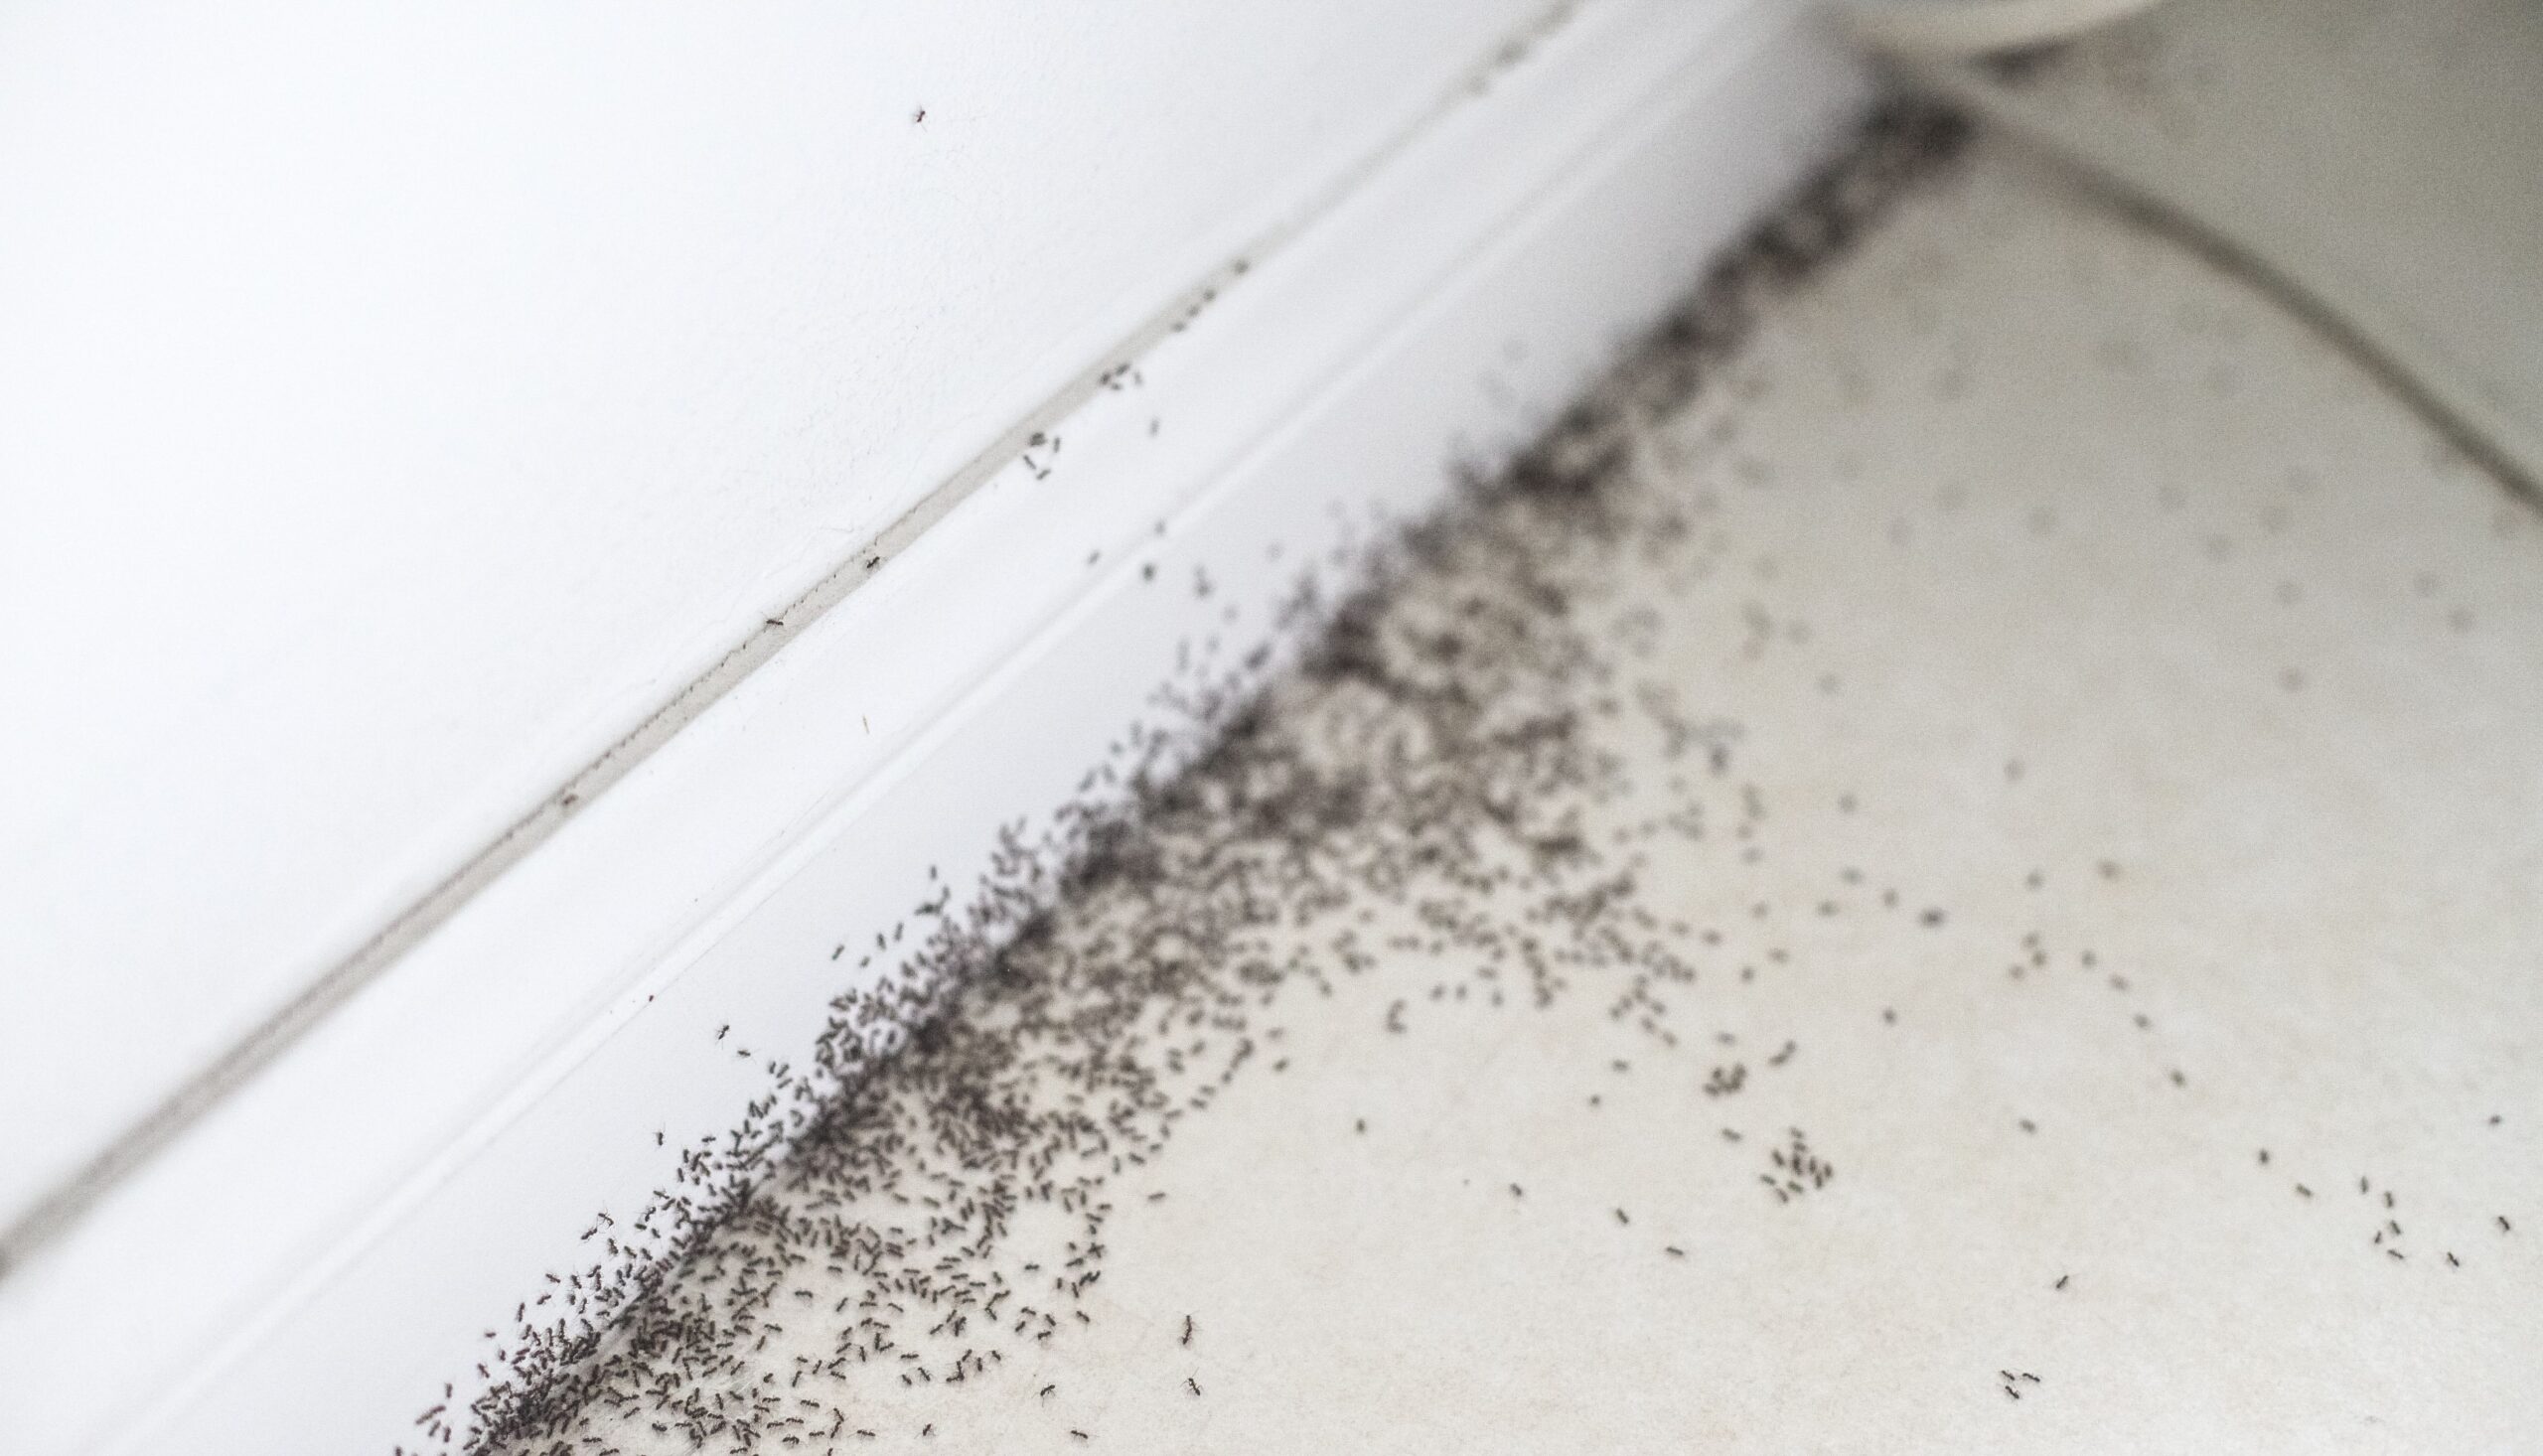
Property condition concerns identified during home appraisal inspection
Pest Infestations and Property Appraisals

Pest Infestations and Property Appraisals: When an Inspection Becomes a Safety Issue

The fleas started jumping almost immediately.

A routine residential appraisal inspection quickly turned into something more serious. As one of our appraisers moved through the home, active fleas were present throughout the property. The appraiser saw cockroaches in multiple areas. The appraiser could not treat the condition as isolated, minor, or easy to ignore.

At that point, the assignment was no longer just about documenting bedrooms, measuring the structure, and observing finishes.

It became a safety issue.

For appraisers, brokers, lenders, attorneys, accountants, and property owners, this type of situation raises an important question: when does a pest infestation become more than a condition concern?

The answer matters because pest infestations can affect safety, marketability, financing, and the timeline of a transaction.

Why Pest Infestations Matter in a Property Appraisal

Appraisers are not pest inspectors. Their role is not to diagnose infestations, determine treatment plans, or certify whether a property is pest-free.

However, an appraiser must observe and report visible property conditions that may affect the assignment.

That distinction is important.

Visible fleas, roaches, rats, or other pests may point to larger concerns during an inspection., the issue may point to larger concerns, including deferred maintenance, moisture problems, sanitation issues, damage, or reduced marketability.

For the client, this matters because visible infestation can create risk before closing. A lender may require additional review. A buyer may hesitate. A broker may face delays. An attorney may need clearer documentation for a legal matter.

When the appraiser identifies the issue early, everyone can respond sooner.

When the Inspection Becomes a Safety Concern

No appraisal assignment is worth risking personal health or safety.

In this case, the appraiser had to make a professional judgment call. Continuing the inspection meant prolonged exposure to active pests. Leaving too soon could limit the available property observations. Ignoring the issue was not an option.

That is where experience matters.

An appraiser must document what is observable, communicate clearly with the client, and avoid making unsupported conclusions. The appraiser should also note any limitations when the condition prevents a full or safe inspection.

For property owners and professionals, this creates an important takeaway: unsafe property conditions can limit the inspection and may affect how the appraisal report is completed.

Property condition concerns identified during home appraisal inspection

Condition Issue or Value Issue?

A pest infestation usually starts as a condition issue.

But depending on severity, it can become a marketability or financing concern.

A minor, isolated issue may have limited impact if it is quickly corrected. A severe infestation may raise questions about habitability, buyer resistance, repair needs, or lender requirements.

That does not mean every pest problem automatically changes the final opinion of value. It means the condition must be considered in context.

The appraiser may need to ask:

      • Does the infestation appear active?
      • Is it widespread?
      • Could it affect health or safety?
      • Did it limit the inspection?
      • Would typical buyers react negatively?
      • Could the lender require treatment or further inspection?

These questions protect the integrity of the appraisal and give the client a clearer picture of risk.

Why Lenders Care About Pest Infestations

Lenders are concerned with collateral risk. If a property has obvious health, safety, or habitability concerns, the lender may need those issues addressed before the loan can move forward. For FHA-related assignments, HUD guidance requires appraisers to consider property conditions connected to safety, security, and soundness, which is why visible infestation concerns may need additional review. See the FHA Single Family Housing Policy Handbook 4000.1.

That can lead to further inspection, treatment documentation, repair requirements, or a subject-to appraisal.

For brokers and borrowers, this matters because unresolved infestations can delay financing. For bankers, it creates a collateral review issue. For attorneys and accountants, it may affect estate, divorce, litigation, or tax-related property decisions.

A credible appraisal helps decision-makers understand what the appraiser observed and why it matters.

When a Subject-To Appraisal May Be Needed

In some cases, the appraiser may complete the appraisal subject to corrective action.

For pest infestations, this may include professional treatment, repair of related damage, or verification that the condition has been addressed.

This is not about creating unnecessary obstacles. It is about protecting the client, lender, and transaction from avoidable risk.

Clear documentation helps prevent confusion when a property condition could affect safety, habitability, or market acceptance.

What Brokers and Realtors Can Learn From This

Early disclosure helps everyone.

Early disclosure of known pest activity, water intrusion, odor, damage, or other condition concerns can prevent last-minute surprises.

For brokers, this can mean fewer financing delays, better client expectations, and stronger professional credibility.

An appraiser walking into a severe infestation without warning creates unnecessary risk. A broker who communicates known issues upfront helps the process move with fewer disruptions.

What Attorneys, Accountants, and Bankers Should Know

For professional decision-makers, pest infestations are not just a property nuisance.

They can affect the reliability of assumptions, the timing of reports, the need for additional documentation, and the usefulness of the appraisal in financial or legal decisions.

In divorce, estate, tax appeal, lending, or litigation matters, property condition can materially affect how a property is understood.

A well-supported appraisal gives you clearer documentation, stronger decision support, and fewer surprises.

The Professional Takeaway

The lesson from this inspection is simple: appraisers must know when a routine assignment has become a risk issue.

Appraisers should document pest infestations carefully, communicate them professionally, and handle them with sound judgment. The appraiser should not overstep into pest inspection work, but should never ignore visible conditions.

For clients, the benefit is clarity.

You gain a better understanding of how property condition may affect financing, timing, marketability, and risk. You also gain professional documentation that supports smarter decisions before a transaction, dispute, or financial review moves forward.

When property conditions create uncertainty, the right appraisal can bring the issue into focus.

Don’t Let Property Conditions Derail Your Transaction

Whether you’re dealing with a lending decision, estate settlement, divorce proceeding, tax appeal, litigation matter, or pre-sale planning, unexpected property conditions can create significant risk if they are not properly documented and understood.

A credible appraisal provides more than a number. It provides the independent analysis, market insight, and professional documentation needed to make confident decisions and avoid costly surprises.

If you need a residential appraisal and want experienced professionals who understand both the property and the risks behind it, PahRoo is ready to help.

Discuss your situation with an experienced appraiser and receive the guidance you need before making an important real estate, financial, or legal decision.

Frequently Asked Questions About Pest Infestations and Property Appraisals
Question: Can a pest infestation affect a home appraisal?

Answer: A pest infestation can affect a property appraisal when it raises concerns about safety, habitability, 
deferred maintenance, or marketability. While appraisers do not diagnose pest problems, they must report 
observable conditions that could influence a lender's decision, a buyer's perception, or the overall 
appraisal assignment.

Question: Will a lender require pest treatment before closing?

Answer: It depends on the severity of the infestation and the loan program. 
Significant pest activity may prompt a lender to request additional inspections, treatment documentation, 
or repairs before the loan can move forward. Addressing known issues early can help reduce delays 
during underwriting.
Question: What should property owners do before an appraisal if they know there is a pest problem?

Answer: Property owners should address active infestations whenever possible and disclose any 
condition issues that may affect the property. Early treatment and transparency can help prevent 
surprises, reduce transaction delays, and provide a clearer understanding of the property's condition during 
the appraisal process.
Commercial real estate appraiser in Chicago analyzing Highest and Best Use for property appraisal.
Commercial Real Estate Appraiser Chicago: Highest & Best Use

When hiring a commercial real estate appraiser in Chicago, one of the most important factors affecting value is a property’s Highest and Best Use.

Many property owners assume that a Highest and Best Use analysis automatically increases value. In reality, market evidence often tells a different story. In some cases, a property’s Highest and Best Use can actually support a lower value conclusion, particularly when market conditions, redevelopment potential, or economic feasibility do not align with expectations.

For property owners, attorneys, accountants, bankers, and brokers, understanding how Highest and Best Use influences an appraisal can be critical during tax appeals, estate settlements, litigation matters, financing decisions, and investment planning.

A qualified commercial real estate appraiser in Chicago evaluates not only what a property could become, but what informed buyers would realistically pay for it in today’s market. That distinction can have a significant impact on value.

What Is Highest and Best Use in Commercial Real Estate?

Highest and Best Use is one of the fundamental principles of real estate appraisal. It represents the reasonably probable use of a property that is:

      • Legally permissible
        • Physically possible
      • Financially feasible
      • Maximally productive

A commercial real estate appraiser in Chicago must analyze all four criteria before determining a property’s Highest and Best Use.

Importantly, Highest and Best Use is not based on speculation. It must be supported by market evidence, economic realities, and buyer behavior. Just because a property could be developed differently does not mean that alternative use creates additional value.

How a Commercial Real Estate Appraiser in Chicago Determines Highest and Best Use

Every commercial property is unique. A professional appraisal examines numerous factors that influence value, including:

      1. Current zoning regulations
      2. Market demand
      3. Location characteristics
      4. Existing improvements
      5. Development costs
      6. Financing conditions
      7. Neighborhood trends

For example, a property owner may believe a vacant parcel is worth more because it could accommodate a larger development. However, if market demand does not support that development, the proposed use may not be financially feasible.

In these situations, the property’s current use may remain its Highest and Best Use.

This analysis helps ensure that value conclusions reflect market realities rather than theoretical possibilities.

Why Development Potential Does Not Always Increase Value

One of the most common misconceptions in commercial real estate is that development potential automatically increases value.

While a property may have favorable zoning, buyers ultimately determine value based on what they can realistically achieve and profit from.

Several factors can limit redevelopment potential:

      1. Rising construction costs
      2. Higher interest rates
      3. Weak tenant demand
      4. Lengthy entitlement processes
      5. Environmental concerns
      6. Utility limitations

A commercial property appraiser in Chicago must consider these factors when evaluating whether redevelopment is financially feasible.

If redevelopment is not economically justified, buyers may not pay a premium for future potential. As a result, the property’s value may be lower than expected.

How Chicago Market Conditions Affect Highest and Best Use

Commercial real estate markets are constantly evolving.

In Chicago, market conditions can vary significantly by property type, neighborhood, and economic cycle. Office, industrial, retail, and mixed-use properties may all experience different demand patterns.

For example:

      • An office building may face elevated vacancy rates.
      • A retail property may struggle with changing consumer habits.
      • An industrial facility may benefit from increased logistics demand.
      • A mixed-use project may face financing challenges.

Because market conditions directly influence financial feasibility, they also influence Highest and Best Use conclusions.

A commercial real estate appraiser in Chicago analyzes local market data to determine whether an alternative use reflects current buyer behavior and investment trends.

Why Highest and Best Use Matters in Property Tax Appeals

Highest and Best Use frequently becomes a key issue during property tax appeals.

Assessments are sometimes based on assumptions regarding redevelopment potential or future use. Property owners can review assessment information through the Cook County Assessor’s Office. However, if those assumptions are not supported by market evidence, the resulting assessment may exceed market value.

An independent appraisal can help answer critical questions:

      • Would a typical buyer pursue the assessor’s assumed use?
      • Is redevelopment financially feasible?
      • Does current market demand support the alternative use?
      • Are there legal or physical limitations affecting the property?

When market evidence indicates that a less intensive use is more realistic, the resulting appraisal may support a lower assessed value.

For many property owners, this analysis becomes one of the most persuasive components of a successful tax appeal.

When Commercial Property Owners Should Obtain an Independent Appraisal

There are several situations where an independent appraisal can provide valuable insight and support.

Property Tax Appeals

A professionally prepared appraisal can provide objective market evidence when challenging an assessment.

Estate and Trust Administration

Accurate appraisal reports help establish credible market value for estate planning, wealth transfer, and settlement purposes.

Litigation Support

Attorneys frequently rely on appraisal reports to support commercial real estate disputes and expert testimony.

Financing and Refinancing

Lenders require reliable market value conclusions when evaluating collateral and underwriting risk.

Investment Decision-Making

Investors use appraisals to better understand opportunities, risks, and market positioning before making capital commitments.

In each of these situations, a thorough Highest and Best Use analysis helps ensure that value conclusions reflect actual market conditions.

Working with a Commercial Real Estate Appraiser in Chicago

Choosing the right appraiser can make a significant difference in the credibility and reliability of the final analysis. Many commercial real estate professionals pursue education and professional development through organizations such as the Appraisal Institute.

An experienced commercial real estate appraiser in Chicago understands local market conditions, zoning considerations, development trends, and appraisal methodologies that influence commercial property value.

More importantly, an independent appraisal provides objective market evidence that can withstand scrutiny from lenders, attorneys, taxing authorities, investors, and other stakeholders.

Whether you are pursuing a property tax appeal, planning an estate, resolving litigation, refinancing a property, or evaluating an investment opportunity, understanding a property’s Highest and Best Use is often one of the most important steps in determining market value.

FAQ: Does Highest and Best Use always increase property value?

Answer: No. A property's Highest and Best Use does not automatically result in a higher value. 
While redevelopment potential may create additional value in some situations, market conditions, development costs, 
financing availability, zoning restrictions, and buyer demand all influence whether an alternative use is financially 
feasible. In many cases, a commercial real estate appraiser in Chicago may determine that the current use represents 
the property's Highest and Best Use, resulting in a lower value than anticipated.
Final Thoughts

Highest and Best Use does not automatically increase property value. In many cases, a thorough analysis reveals that market realities, financial feasibility, or physical limitations reduce the likelihood of alternative development scenarios.

By focusing on what informed buyers would realistically pay in today’s market, a commercial real estate appraiser in Chicago can provide a well-supported opinion of value that reflects actual market conditions rather than speculation.

For property owners, attorneys, accountants, bankers, and brokers, that distinction can have a meaningful impact on financial decisions, tax appeals, estate administration, litigation outcomes, and long-term investment strategies.

Need a Commercial Real Estate Appraisal in Chicago?

Whether you are preparing for a property tax appeal, estate settlement, financing transaction, litigation matter, or investment decision, obtaining an independent appraisal can provide the objective market evidence needed to move forward with confidence.

cost segregation appraisal process showing property analysis, component breakdown, and IRS-compliant reporting
Cost Segregation Appraisal: Avoid Costly Mistakes

A cost segregation appraisal is only as valuable as the evidence behind it. Done well, it accelerates depreciation and improves cash flow on a commercial property. Done cheaply, it can unravel the moment the IRS, a lender, or a client’s attorney asks for support. For the professionals who rely on these studies, quality matters far more than the price on the invoice.

By the end of this article, you’ll know:

  • Why a bargain study can cost more than it saves
  • What the IRS looks for when it reviews a study
  • Where an independent appraiser fits into the process

What a Cost Segregation Appraisal Really Involves

Cost segregation is a tax strategy, not a valuation on its own. A study breaks a building into its components. Then it assigns each one to the right depreciation class, so the owner can recover cost faster. The IRS treats this as an engineering-based analysis. Its Cost Segregation Audit Techniques Guide spells out what a quality study should contain.

Here is where an appraiser earns a seat at the table. Before components can be classified, someone has to establish the property’s value. That means allocating the purchase price across land, building, and improvements. That allocation is a valuation question, and it is the foundation the rest of the study stands on. Get it wrong, and every number downstream inherits the error. Our commercial appraisal work often supports exactly this kind of foundation. The engineering and tax professionals then complete the study.

Why Defensibility Matters More Than Price

Two studies can look identical on paper. Both list components, assign useful lives, and project a depreciation benefit. The real test comes later, when someone challenges the numbers.

A defensible study answers three questions cleanly. Is the methodology documented and consistent with IRS guidance? Is each classification supported by real analysis rather than assumption? Can the conclusions survive an audit? Cheaper studies often cut corners in ways that stay invisible until an examiner starts reading closely. The IRS guide is blunt on this point. Preparer qualifications and documentation quality separate a study that holds from one that collapses.

What a Weak Study Can Cost You

When a study fails, the damage is financial and it lands on real people. An owner can face disallowed deductions, audit adjustments, amended returns, and penalties. The savings that looked so attractive get clawed back, often with interest.

The exposure is not limited to the taxpayer. For the attorney, accountant, or banker who recommended the work, a study that falls apart becomes a credibility problem. Protecting a client’s position and your own reputation is reason enough to care about how the study was built.

Red Flags in a Cost Segregation Study

You do not need to be an engineer to spot a questionable study. A few warning signs tend to show up together.

Watch for aggressive classifications with no supporting detail, thin documentation, and templates that treat every property the same. Be wary of pricing that seems disconnected from the scope of work. The IRS specifically flags contingency-fee arrangements and rule-of-thumb allocations, because both create pressure to overstate short-life property. When the report reads like it was built for speed, that is usually what you are getting.

How to Choose Work That Holds Up

Change the question you ask. Instead of who can do this cheapest, ask what protects the position if it is challenged. That reframe points you toward qualified preparers, thorough documentation, and a sound valuation underneath it all.

An independent appraisal is part of that protection. It grounds the study in a defensible opinion of value. The depreciation classifications then rest on solid footing rather than guesswork. When real money and professional reputations are on the line, that footing is worth paying for.

High-Stakes Property? Start With a Defensible Valuation.

PahRoo provides the independent commercial appraisal that a sound cost segregation study is built on. It rests on real analysis and thorough documentation. Talk to us before the numbers get tested.

Speak With Our Team

Frequently Asked Questions

What is a cost segregation appraisal?

It is the independent valuation work that supports a cost segregation study. The study reclassifies building components for faster depreciation. The appraisal establishes the underlying property value and cost allocation it relies on.

Who should perform a cost segregation study?

The IRS expects preparers with expertise in construction, engineering, and tax law. A quality study identifies its preparers and their credentials, which is one reason qualified professional involvement matters.

What makes a cost segregation study defensible to the IRS?

Clear methodology, detailed asset classification supported by analysis, and documentation tied to IRS guidance. The IRS Cost Segregation Audit Techniques Guide describes the elements of a quality study.

What are the risks of a low-quality study?

Disallowed depreciation deductions, IRS audit adjustments, amended returns, and penalties. For advisors who recommended the work, a failed study can also damage professional credibility.

How does an appraiser support cost segregation?

An appraiser provides the independent opinion of value and purchase price allocation that a study is built on. That valuation foundation helps the depreciation classifications rest on defensible ground.

Need a Defensible Commercial Valuation?

PahRoo Appraisal & Consultancy delivers independent, USPAP-compliant valuations for commercial and investment property, led by Michael Hobbs. A cost segregation study, a lender, or a legal matter can all depend on a credible number. Our commercial appraisal team provides that foundation. Explore our full range of appraisal services, or reach us through our contact page to talk through your situation.


2026 Cook County reassessment notice used for property tax appeal appraisal
2026 Cook County Reassessment Appraisal: Protect Your Property Taxes

A Cook County reassessment appraisal is an independent, USPAP-compliant opinion of your property’s value, prepared so you can support a property tax appeal when the county’s new number looks too high. The 2026 notices are landing across the county right now. The figure on yours sets the taxable value for the next three years, so it earns a close read before you file it away.

By the end of this article, you’ll know:

  • Why the county’s assessment can miss what your property is really worth
  • Which owners have the strongest reason to appeal
  • How township deadlines work, and what evidence actually moves a decision

What a Cook County Reassessment Appraisal Actually Does

The Assessor’s Office values every parcel in the county, which is an enormous job. To handle that volume, it uses mass appraisal: neighborhood data, historical trends, and statistical models that assign values in bulk. That method is efficient, but it is also blunt. It describes the average property on your block better than it describes yours.

A reassessment appraisal works the other direction. A certified appraiser inspects your specific property and builds an opinion of value from comparable sales, market rents, physical condition, and income, all documented under the Uniform Standards of Professional Appraisal Practice set by the Appraisal Foundation. The result is independent and tied to evidence, not to a countywide model. When you file an appeal, that is what gives your position weight. You can see how we handle these assignments on our real estate appraisal services page.

Where the County’s Mass Appraisal Misses Your Property

Mass models run on assumptions, and assumptions break down at the individual level.

Condition is the common one. Deferred maintenance, an aging roof, or outdated mechanical systems rarely show up in county data, yet they pull real value out of a building.

Income properties get missed too. If your building carries vacancy, below-market leases, or rising operating costs, a statistical model will not feel any of that. It sees square footage and a neighborhood, not a rent roll under pressure.

Timing matters as well. Markets move, cap rates shift, and investor demand changes faster than assessment cycles do. When the county’s data lags the market, your assigned value can sit above what a buyer would actually pay. Then the tax bill climbs even though performance has not.

Who Should Take a Second Look Before the Deadline

Not every notice is worth challenging. Some assessments are fair, and appealing them only wastes time. But a few situations almost always justify a closer review.

Look harder at your reassessment if you own commercial or multi-family property, or if you bought recently at a price below the new assessed value. The same goes if income has slipped, vacancy has risen, or the building needs significant repairs. Owners handling estate, trust, or divorce real estate should pay attention too, because the assessed value can ripple into those proceedings. So should the CPAs and attorneys advising them.

Because the 2026 figure holds for a full three-year cycle, even a modest reduction compounds. On commercial and investment property, that can add up fast, which is why our commercial appraisal clients tend to run the numbers early.

How the Appeal Timeline Works

Each township in Cook County opens and closes on its own schedule, and the deadlines are firm. Once your township’s window shuts, your options for that year are mostly gone.

Most appeals start at the Cook County Board of Review, where you submit evidence supporting a lower value. The Board weighs that evidence and issues a decision. If it does not resolve things, the Illinois Property Tax Appeal Board is the next stop. In both venues, an appeal built on a documented appraisal reads very differently from one built on a homeowner’s hunch. The discussion shifts from opinion to analysis, and analysis is harder to wave off.

Waiting is the quiet mistake. A rushed filing in the final week rarely produces the strongest case. Reviewing your notice early gives you time to decide whether an appeal even makes sense, and to prepare the documentation properly if it does.

What to Do With Your 2026 Notice

Start by reading the assessed value the way a buyer would. Would your property actually sell for that today? If the answer is yes, you can probably let it stand. If it feels high, or if your income numbers no longer support it, that is your signal to get an independent appraisal before your township deadline.

The 2026 reassessment is a proposed value. You have the right to test it, and the evidence to do so is well within reach.

Think Your 2026 Assessment Runs High?

We prepare USPAP-compliant appraisals built to stand up at the Board of Review, tailored to your property and your township’s deadline. Let’s find out whether an appeal makes financial sense.

Request Your Appraisal Quote

Frequently Asked Questions

What is a Cook County reassessment appraisal?

It is an independent, USPAP-compliant opinion of your property’s value, prepared by a certified appraiser so you can support a property tax appeal. It looks at your specific property rather than a countywide model.

Does a higher assessment always mean I should appeal?

No. Some reassessments are accurate, and appealing them is not worth the effort. An appraisal helps you tell the difference before you commit to filing.

What evidence carries the most weight in a property tax appeal?

A documented appraisal supported by comparable sales, market rents, and condition analysis tends to carry the most weight. It moves the discussion from opinion toward verifiable data.

How long do I have to appeal my 2026 reassessment?

Each Cook County township has its own appeal window, and the deadlines are firm. Check your township’s schedule as soon as your notice arrives, because late filings are generally not accepted.

Can an appraisal help with commercial or investment property appeals?

Yes. Commercial and multi-family properties often benefit most, since vacancy, below-market leases, and rising expenses are exactly the factors a mass model overlooks.

Need an Independent Appraisal in Cook County?

PahRoo Appraisal & Consultancy prepares independent, USPAP-compliant valuations across Chicago and Cook County, led by Michael Hobbs. Alongside property tax appeal work, we handle commercial and estate assignments, and you can reach the team any time through our contact page. If your 2026 notice looks off, the earliest review gives you the most room to act.


2026 Commercial Refinancing Cliff showing CRE loan maturities
The 2026 Commercial Refinancing Cliff

The 2026 Commercial Refinancing Cliff is no longer theoretical. It is here.

More than $1.5 trillion in commercial real estate loans are scheduled to mature between now and the end of 2026. Many of those loans were originated in a low-interest-rate environment that no longer exists. What was once inexpensive leverage is now a refinancing challenge.

However, this is not just about higher rates.

It is about tighter underwriting, valuation recalibration, and a new level of scrutiny from lenders. In this environment, a professional commercial appraisal is not a checkbox. It is leverage.

For attorneys, bankers, accountants, and commercial property owners, the question is simple:

What is the property defensibly worth today, not in 2022?

The Reality Behind the $1.5 Trillion Maturity Wave

According to the Mortgage Bankers Association (MBA), more than $1.5 trillion in commercial mortgage debt is scheduled to mature through 2026. Federal Reserve rate policy shifts and capital market tightening have further complicated refinancing assumptions. Data from Trepp’s CRE research reports also shows increased delinquency pressure across certain asset classes, reinforcing why accurate underwriting inputs matter more than ever.

As a result, many properties now face a triple pressure point:

1. Higher Borrowing Costs

Interest rates remain materially above the levels of five to ten years ago. Even stabilized assets may struggle to meet prior debt service metrics.

2. Stricter Underwriting Standards

Debt Service Coverage Ratio (DSCR) thresholds are tighter.
Loan-to-Value (LTV) limits have compressed.
Credit committees are scrutinizing assumptions with far more conservatism.

3. Valuation Volatility

Office usage has shifted. Retail absorption varies by submarket. Insurance costs and operating expenses have risen across multifamily and hospitality. Industrial demand has cooled in certain corridors.

Because of these factors, refinance proceeds may not match the maturing loan balance. That difference is the equity gap.

The 2026 Commercial Refinancing Cliff is not just about rates. It is about value recalibration.

Why the 2026 Commercial Refinancing Cliff Creates Equity Gaps

When a loan matures, the lender evaluates current market value, not historic purchase price or past optimism.

If valuation declines — even modestly — leverage compresses.

For example:

      • A property financed at 75% LTV five years ago may now qualify for only 60–65%.
      • NOI adjustments from higher expenses reduce supportable loan proceeds.
      • Lease rollover risk may materially impact underwriting assumptions.

Without a clear, defensible appraisal, negotiations become reactive instead of strategic.

You do not want to discover the equity gap at the closing table.

You want clarity months in advance.

How a Professional Appraisal Protects Your Refinance

A credible commercial appraisal provides more than a number. It provides positioning.

1. You Gain Realistic Market Intelligence

In a K-shaped recovery, some assets are outperforming while others struggle. A data-driven appraisal clarifies where your property sits within its competitive set.

This is not about optimism.
It is about defensibility.

With credible market analysis, you walk into lender conversations prepared — not guessing.

2. You Reduce Credit Committee Friction

Bankers are under pressure. Regulators are watching. Risk tolerance has narrowed.

A well-supported appraisal:

      • Documents income stability
      • Addresses lease rollover exposure
      • Explains market absorption trends
      • Clarifies capitalization rate positioning

When documentation is thorough, lender objections decrease.

Instead of debating assumptions, the conversation shifts to structure.

That shift matters.

3. You Strengthen Negotiation Leverage

If refinancing falls short, you may need:

      • Additional equity
      • Loan restructuring
      • Capital partner discussions
      • Workout negotiations

An accurate appraisal becomes the anchor for every one of those conversations.

Attorneys negotiating restructuring need defensible value.
Accountants advising clients need realistic asset positioning.
Owners evaluating capital calls need clarity before making commitments.

The 2026 Commercial Refinancing Cliff rewards preparation. It penalizes delay.

What Credit Committees Are Looking for in 2026

Understanding lender psychology improves outcomes.

In 2026, credit committees are prioritizing:

      • Sustainable NOI (not peak-year income)
      • Conservative vacancy assumptions
      • Verified lease terms
      • Expense normalization
      • Realistic exit capitalization rates

Credit committees are stress-testing projections and comparing submarket trends with increased scrutiny. Tenant credit quality is also under deeper review than in prior cycles.

A professional appraisal anticipates those questions before they are asked.

That preparation reduces uncertainty and uncertainty is what stalls approvals.

Asset Class Sensitivity Matters

Not all properties face the refinancing cliff equally.

Office:
Tenant downsizing and hybrid models continue to pressure absorption in many CBD submarkets.

Multifamily:
Higher insurance premiums and operating costs impact net income, particularly in Sunbelt regions.

Retail:
Service-oriented and grocery-anchored centers are outperforming discretionary retail.

Industrial:
Cooling demand in certain logistics corridors has moderated rent growth assumptions.

An appraisal grounded in real-time submarket data distinguishes resilient assets from vulnerable ones.

Generic modeling does not.

The Risk of Waiting

One of the most common mistakes owners make is waiting until 30–60 days before loan maturity to obtain an appraisal.

By then:

      • Negotiating leverage is reduced
      • Alternative lenders may require expedited underwriting
      • Equity partners have limited time for review

Early appraisal provides optionality.

Optionality means:

      • Time to source new capital
      • Time to restructure intelligently
      • Time to adjust strategy

The 2026 Commercial Refinancing Cliff is steep. But it is manageable for those who prepare early.

Why This Matters to You

If you are advising clients — or protecting your own portfolio — uncertainty is the real risk.

A defensible commercial appraisal gives you:

      • Clarity before negotiations begin
      • Credibility in front of lenders
      • Data to support restructuring discussions
      • Strategic positioning instead of reactive decision-making

In this lending environment, numbers unsupported by rigorous analysis will not survive credit review.

Professional documentation will.

Prepare Before the Maturity Date

The refinancing wave is not slowing. It is accelerating toward 2026.

The question is not whether underwriting has tightened.
It has.

The question is whether you enter the refinance discussion prepared.

The 2026 Commercial Refinancing Cliff separates speculative assumptions from defensible analysis.

An early, well-supported commercial appraisal provides the clarity you need to protect equity, strengthen negotiations, and move forward with confidence.

property tax appeal appraisal evidence under board review
Appraisal Evidence Appeals: Are Boards Raising the Bar?

Are Boards of Review Scrutinizing Appraisal Evidence More Closely?

In early 2025, the Cook County Assessor’s Office published a sales-ratio study with a striking finding: commercial appeal appraisals came in at a median of just 62% of actual sale prices. The Assessor’s office has used that figure to argue that some appeal appraisals undershoot market value and that unsupported reductions can shift the tax burden onto other property owners, including homeowners.

That argument has added pressure across the appeals process to support valuation conclusions more thoroughly. In our experience, professionals involved in appeals are noticing a shift in how valuation arguments are received.

A Quiet Shift, But a Real One

No formal policy change has been announced. Still, the emphasis is noticeable. Several property tax attorneys and valuation professionals describe the same underlying theme: expectations around evidence have tightened.

Strong legal arguments have always mattered. Increasingly, though, they work best when paired with clear support for valuation methodology, assumptions, and market data. Conclusions without that backing can draw more questions than they used to.

For appeal filers, that matters.

Why Appraisal Support Matters More Than Before

As appraisal evidence comes under closer review, appeal bodies are under pressure to protect the integrity of the tax base. Income assumptions, comparable sales selection, and adjustment logic all tend to get a closer look. Appraisal quality is no longer a secondary consideration, it is central to appeal success.

In short, strong legal arguments now benefit from equally strong valuation support to achieve the outcomes they once did on their own.

What This Means for the 2026 Appeal Cycle

As we move deeper into the 2026 appeal cycle, the practical implications are clear:

      • Appeals built on limited or dated market support may face more questions
      • Appeal bodies increasingly expect clear reconciliation between approaches
      • Sale-price disconnects tend to draw attention quickly
      • Credibility, not just persuasion, increasingly drives results

If you are already reinforcing your valuation support, you are ahead of the curve. If not, now is a good time to reassess before filings are underway.

How to Strengthen Your Valuation Support Right Now

To stay competitive in this environment, consider:

      • Using sale-supported conclusions wherever possible
      • Clearly explaining any deviations from recent transactions
      • Tightening income and expense assumptions to market norms
      • Ensuring appraisal narratives can withstand close scrutiny

For broader context on appraisal standards and defensible valuation practices, the Appraisal Institute’s guidance on commercial valuation methodology remains a trusted reference and can support credibility in appeals when cited appropriately.

Appeal bodies are paying closer attention. Is your valuation evidence ready?

If you are preparing for the 2026 appeal cycle and want appraisal evidence that holds up under closer scrutiny, now is the time to act.

Request a Valuation Review

Estate planning and probate appraisal for commercial real estate valuation
From Comps to Code in Today’s Commercial Appraisals

For decades, commercial real estate appraisal relied on a familiar foundation: comparable sales, income analysis, and professional judgment informed by local market knowledge. That framework still matters, but it’s no longer the full story.

Across jurisdictions like Cook County, assessment offices are moving away from purely comp-driven reasoning and toward valuation systems built on large datasets, statistical modeling, and automated analysis. The shift is subtle, but its impact is significant.

In today’s environment, commercial appraisals are increasingly evaluated not just on what value they conclude, but on how that value was produced.

Why “Comps” Alone Are Losing Influence

Comparable sales have long been the backbone of commercial property appraisal. They remain essential, but assessors now view them as just one input among many.

Offices such as the Cook County Assessor’s Office are increasingly integrating broader datasets, including federal appraisal and housing data from the Federal Housing Finance Agency (FHFA).

These datasets support:

      • Regression-based valuation models
      • Automated valuation models (AVMs)
      • Market-wide consistency testing
      • Equity and regressivity analysis

When assessments are defended using these tools, appeals based solely on narrative adjustments or limited comps can struggle to gain traction.

What “Code” Really Means in Modern Appraisal

“Code” doesn’t replace appraisal judgment, but it does change how that judgment is scrutinized.

Modern commercial appraisals are increasingly assessed against:

      • Data relevance and scale
      • Transparency of methodology
      • Replicability of conclusions
      • Consistency across property classes

For professionals involved in commercial real estate appraisal for tax appeals, this means valuation credibility now hinges on explaining methodology as clearly as market behavior.

In other words, the appraiser’s role has expanded from market interpreter to valuation explainer.

The New Battleground in Property Tax Appeals

In a data-driven assessment environment, appeals are less about debating opinion and more about evaluating process.

Effective challenges increasingly focus on:

      • Whether model inputs accurately reflect the subject property
      • Whether income assumptions align with real operating realities
      • Whether classification or use errors skew the data
      • Whether equity claims hold up at the property level

This shift doesn’t eliminate comps, it reframes them. Comparable sales now support or challenge model assumptions rather than serving as the sole basis for value.

Why This Shift Extends Beyond Tax Appeals

The move from comps to code isn’t limited to assessment disputes. The same expectations are influencing appraisals used in legal and advisory contexts.

Attorneys working in:

      • Estate planning appraisal
      • Probate real estate appraisal
      • Date-of-death property appraisal
      • Litigation support appraisal

are increasingly focused on whether an appraisal can withstand scrutiny, not just whether it reaches a reasonable number.

For probate attorneys, especially those handling income-producing or mixed-use commercial properties, valuation clarity and defensibility are essential.

Commercial Appraisals in Probate and Estate Planning

Commercial properties involved in estates present layered appraisal challenges: income history, tenancy changes, market conditions at a specific date, and regulatory expectations.

A credible probate appraisal for real estate must:

      • Address the correct valuation date
      • Clearly document data sources and assumptions
      • Explain methodology in plain, defensible terms
      • Align with IRS, court, and professional standards

As data-driven appraisal becomes more common, courts and counsel are less tolerant of appraisals that rely on surface-level analysis without methodological support.

What Attorneys Should Expect from Modern Appraisals

For tax attorneys, probate attorneys, and real estate counsel, today’s commercial appraisals should provide more than a conclusion—they should provide insight.

Key expectations now include:

      • Transparent explanation of valuation methods
      • Clear articulation of data limitations
      • Logical reconciliation of comps and models
      • Defensible reasoning under cross-examination

This is especially critical in expert witness appraisal services, where the ability to explain both market behavior and data-driven analysis can determine credibility.

Why the Shift Will Continue

Assessment offices face increasing pressure to demonstrate fairness, consistency, and accountability. Large datasets and automated models help meet those expectations.

As these tools become standard, commercial appraisals that fail to engage with methodology, not just market value—will feel outdated.

For firms like PahRoo, this evolution reinforces the value of disciplined, well-documented commercial appraisal work across tax appeals, estate planning, and probate matters.

Commercial appraisal hasn’t abandoned comps, but it has moved beyond them.

In today’s environment, the most credible valuations are those that connect market evidence with data-driven reasoning and clearly explain how conclusions are reached.

For property owners, attorneys, and fiduciaries navigating tax appeals or estate-related matters, working with appraisers who understand both sides of that equation—comps and code—is no longer optional. It’s the standard.

Let’s Talk Before the Numbers Are Challenged for You

If your assessment, appeal, or estate valuation is being defended with data models instead of comps, it’s worth a conversation.
Speak with our commercial appraisal team to understand how today’s valuation methods affect your case and how to respond with confidence.


Schedule a Strategy Call

Commercial real estate appraisal in Chicago during the 2025 North Cook reassessment
Chicago Commercial Appraisals: Do These Values Hold Up?

Commercial Real Estate Appraisal Chicago: What the 2025 North Cook Reassessment Is Telling Property Owners

As the 2025 North Cook reassessment cycle comes into focus, many commercial property owners are asking the same question:

Do these values really reflect today’s market?

Early results suggest that in several submarkets, assessed values increased even while fundamentals, occupancy, effective rents, and demand, remain under pressure. For anyone navigating a commercial real estate appraisal in Chicago, these patterns matter more than ever.

Assessment Increases That Don’t Match Market Conditions

Across parts of North Cook County, we’re seeing commercial assessments rise in ways that appear disconnected from on-the-ground realities.

Retail corridors in Evanston and Skokie experienced notable increases despite:

    • Persistent vacancy
    • Slower leasing velocity
    • Pressure on tenant sales and rent growth

Office properties tell a similar story. In several areas, valuations ticked upward even as hybrid work, sublease inventory, and reduced effective income continue to weigh on performance.

If your assessment doesn’t reflect how your property actually performs, you may be carrying an unnecessary tax burden.

A Familiar Pattern for Chicago-Area Property Owners

For owners who went through the 2024 reassessment cycle in Chicago, these trends may feel familiar.

That cycle was marked by:

    • Aggressive income modeling
    • Uneven adjustments between submarkets
    • Valuations that required deeper analysis to reconcile with reality

The 2025 North Cook outcomes suggest a similar approach, one where assumptions matter just as much as numbers. That makes a well-supported commercial real estate appraisal in Chicago an essential tool, not a formality.

Why This Matters Beyond North Cook

Commercial real estate appraisal in Downtown Chicago during the 2025

These reassessment results don’t just affect current tax bills, they offer insight into what may come next.

Patterns emerging in North Cook often influence future methodology, including how the Assessor approaches South Cook reassessment cycles. Understanding how values are being modeled now can help owners prepare earlier, appeal smarter, and avoid surprises later.

Early insight gives you leverage, before deadlines compress and options narrow.

When a Commercial Real Estate Appraisal Becomes Strategic

In reassessment years like this, an appraisal isn’t just about value, it’s about clarity.

A defensible, market-supported appraisal can:

    • Identify mismatches between assessed value and real income
    • Test the assumptions embedded in mass appraisal models
    • Support appeals with data grounded in current market conditions

For Chicago-area owners, this is where commercial real estate appraisal expertise becomes a strategic advantage rather than a compliance exercise.

Capacity for Select New Engagements in 2025

The quieter holiday season was used to streamline internal processes, expand the team, and create capacity for a limited number of new clients in 2025.

For owners facing assessments that don’t align with performance or those planning ahead for upcoming cycles, now is often the right time to evaluate options before appeal windows close.

When valuation models and market reality diverge, who’s pressure-testing the numbers on your behalf?

NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712