Author: Michael Hobbs

Request a quote

Our blog

Latest news
& events

Family law attorney interviewing an appraiser before choosing an expert witness appraiser for a divorce case
12 Questions to Ask Before You Hire an Expert Witness Appraiser

Most family law attorneys meet their appraiser twice. Once on the phone, and again at the deposition. But the deposition is the wrong place to learn who you hired. Choosing expert witness appraisers takes a real interview, not a quote request, because the person who signs the report is the person opposing counsel will cross-examine. Here are the questions worth asking first, and what a good answer sounds like.

By the end of this article, you’ll know:

  • The twelve questions to ask before you retain an appraiser for a contested case.
  • How to verify a license, a designation, and disciplinary history yourself.
  • Which answers should end the interview on the spot.

Choosing Expert Witness Appraisers Before the Disclosure Clock Runs

Timing shapes every other choice. Under Illinois Supreme Court Rule 218, the court sets witness disclosure dates at case management. Those dates must let discovery close at least 60 days before the expected trial date, unless the parties agree otherwise. The committee comment also goes further. It says opinion witnesses should be disclosed early enough to be deposed before that 60-day line. Local rules and the case management order control the details, so check both.

An appraiser retained a month before disclosure has a month to inspect, research, write, and answer your questions. In practice, that rarely goes well. We covered what makes the report itself hold up in our article on what makes an appraisal defensible on the witness stand. This one is about the person behind the report instead.

Credentials and Competency: Questions 1 to 4

  1. What credential do you hold, and in which states? The federal system recognizes three levels: State Licensed, Certified Residential, and Certified General. Trainees, however, don’t appear on the federal registry and can’t independently appraise for federally related work.
  2. Can I confirm that myself? Yes, and you should. The Appraisal Subcommittee’s National Registry is searchable by name and state. It also shows active discipline that limits an appraiser’s work, such as a revocation or suspension. For resolved or older matters, call the state licensing agency.
  3. Do you hold a professional designation? The Appraisal Institute awards the MAI for all property types and the SRA for residential work. Its online directory also lets you confirm a designation by name. A designation isn’t a license, and a license isn’t a designation, so check both.
  4. How many properties like this one have you appraised in this market? A Kenilworth estate, a Pilsen three-flat, and a strip center held in an LLC are three different assignments. So ask for a rough count over the last three years and the price range. A vague answer here matters more than a thin resume.

Testimony and Independence: Questions 5 to 9

  1. How many times have you testified, and where? Separate depositions from trials, and ask which courts and case types. Then request case names, subject to confidentiality, so you can pull transcripts if you want them.
  2. Has any court excluded or limited your testimony? A yes isn’t automatically disqualifying. But a yes the appraiser didn’t volunteer usually is.
  3. Have you worked on this property, or for either spouse, before? A refinance appraisal from two years ago, or a friendship with the other side, becomes a cross-examination theme. You want to hear about it now, not at the deposition.
  4. Who hires you in family cases? An appraiser retained only by one side of the bar hands opposing counsel an easy story about bias. Work for petitioners, respondents, and joint engagements reads as independence instead.
  5. How is your fee set? Expect a fixed report fee plus hourly rates for preparation, deposition, and trial. USPAP’s Ethics Rule bars compensation that depends on the value reached or on a result that favors the client. So any hint of a fee tied to the number ends the conversation.

The Report and the File: Questions 10 to 12

  1. Who inspects the property, and who signs the report? If an associate does the fieldwork, the signer still has to describe the house under oath. Find out how that handoff works before a deposition exposes it.
  2. What report format will you use, and can you value a past date? A lender form limits explanation by design. A narrative report written for litigation, by contrast, walks a judge from the data to the value. So it holds up better when the value is contested. If the court may use a date other than trial, confirm retrospective experience. Our article on the date of value in a divorce appraisal explains why that matters.
  3. Will you produce your workfile on request, and how fast? Opposing counsel will ask for it, often in the first deposition notice. An appraiser who hesitates now will hesitate under subpoena too.

Answers That Should End the Interview

Some answers are dealbreakers on their own. Watch for these, even when the rest of the interview goes well.

  • A value quoted, or hinted at, before anyone has inspected the property.
  • Any fee that depends on the number or on how the case turns out.
  • A license you can’t find on the National Registry, or an active suspension on it.
  • No testimony history, and no interest in preparing for cross.
  • Reluctance to share the workfile or to explain an adjustment in plain English.

That last one deserves a live test, because judges need the plain-English version. Ask the appraiser to walk you through one adjustment from a past report, redacted, as if you were the judge. If you’re lost after two minutes, the judge will be too.

For the CPA Coordinating the Valuation

Forensic accountants often build the appraiser shortlist, or inherit one counsel already picked. Either way, four questions belong in your own interview. First, can the appraiser value the property as of the same date as your business valuation or balance sheet? Second, will the report state its definition of value, so you can reconcile it with the standard you’re using? Third, if the real estate sits inside an entity, will the appraiser value the real property and leave interest-level adjustments to you? Finally, will you get the adjustment grid and comparables in a form you can cite in your schedules?

Then put those answers in the engagement letter. That way the two reports meet at the same date and the same definition, instead of colliding at trial.

Interview the Appraiser the Way Opposing Counsel Will

Opposing counsel will ask most of these questions eventually. Asking them first, before the report is ordered, costs you an hour. Skipping them, though, can cost you the valuation. So verify the credential yourself, test the testimony record, and pin down the fee and the date in writing. Then hire the person you’d be comfortable putting on the stand.

Vetting an Appraiser Before Disclosure?

Put PahRoo through the same twelve questions. Michael Hobbs, MAI, SRA, signs our litigation reports and testifies to them, and we’ll answer every question before you retain us.

Schedule an Expert Consult

Frequently Asked Questions

What should you ask an expert witness appraiser?

Start with credentials: license level and states, any Appraisal Institute designation, and experience with the property type. Then ask about testimony history, any exclusion, prior work for either party, how the fee is set, who inspects and signs, and whether the workfile will be produced on request.

What is an MAI or SRA designation?

Both are awarded by the Appraisal Institute. The MAI covers all property types, including commercial and residential. The SRA covers residential property. Each requires education and experience beyond a state license, and holders agree to the Institute’s ethics and standards.

When should you hire an appraisal expert?

As soon as value is contested. In Illinois, Rule 218 has the court set witness disclosure dates so discovery ends at least 60 days before trial, unless the parties agree otherwise. The appraiser needs time to inspect, research, write, and be deposed inside that window.

How much does an expert witness appraiser cost?

It depends on the property, the report type, and how much testimony the case needs. Most engagements pair a report fee with hourly rates for preparation, deposition, and trial. Get both in writing, and confirm nothing depends on the value reached.

How do I check an appraiser’s license?

Search the Appraisal Subcommittee’s National Registry by name and state. It lists the credential level and any active discipline limiting the appraiser’s work. For past or resolved matters, contact the state licensing agency.

Expert Witness Appraisal for Family Law Counsel

If you’re building a shortlist, start with our residential appraisal services page, which covers divorce work across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, signs PahRoo’s litigation reports and is available for deposition and trial. For a contested estate home, see our guide to appraising luxury homes in high-asset divorce, or contact us with the case caption and the disclosure deadline.
Rows of similar Chicago homes valued together in a Cook County mass appraisal model
Mass Appraisal vs Single Property Appraisal and Why the Numbers Diverge

Every fall, property tax attorneys hear some version of the same question. How can the assessor’s number and the client’s own sense of the property be so far apart? The gap usually comes down to mass appraisal vs single property appraisal, two different methods built for two different jobs. Knowing where they diverge often decides whether an appeal holds up.

By the end of this article, you’ll know:

  • How the Cook County Assessor’s mass appraisal model actually works.
  • Where that model tends to miss a specific property’s true condition or income.
  • When the gap between the assessor’s number and an individual appraisal is worth building into an appeal.

Mass Appraisal vs Single Property Appraisal: What Actually Differs

Mass appraisal and single property appraisal answer different questions. Both aim at market value, but they solve it differently. The International Association of Assessing Officers defines mass appraisal as valuing a group of properties on a single date. The method relies on common data, standardized procedures, and statistical testing across the whole group. It’s built for scale. A single property appraisal is built for one address.

USPAP, the standards that govern the appraisal profession, treats the two as separate disciplines. Standards 1 and 2 cover the development and reporting of a single real property appraisal. Standards 5 and 6 cover mass appraisal instead, with rules of their own for building and testing valuation models. Same governing body, same profession, but two different scopes of work.

In Cook County, that mass appraisal takes the form of a Computer Assisted Mass Appraisal, or CAMA, system. According to the Cook County Assessor’s Office, the model draws on years of sales data. It tests hundreds of model variations against actual sale prices. Then it applies the best performer to every home in the area, sold recently or not. An independent appraisal works the other way. It starts with one property, one inspection, and comparables chosen for that property alone.

How the Assessor Actually Builds Your Number

Cook County reassesses about a third of its townships every year. The cycle rolls on a three-year rotation. Inside each township, the CAMA system groups homes by neighborhood. It pulls in characteristics like square footage, age, land, and construction type. It compares those characteristics against recent sales nearby. Homes that are more similar, or closer geographically, carry more weight in the calculation.

The models started as regression analysis, the traditional mass appraisal tool. They’ve since moved further. The Assessor’s own published code shows the residential and condo models now use a machine learning method called gradient boosting. That method can pick up non-linear patterns a simple regression line would miss. Either way, the code tests hundreds of model versions against actual sale prices before picking a winner. Then it applies that model across the township. Analysts still review the results neighborhood by neighborhood and adjust individual assessments before the notices go out.

Where the Model Runs Out of Room

A mass appraisal model works from what’s on file, and from nearby sales. It can’t see inside a client’s kitchen. Deferred maintenance, an outdated system, or a chopped-up layout usually won’t show up in the model. Storm damage that hasn’t been repaired often goes unreported too. The same goes for the upside. A model built on neighborhood averages can also miss a property that’s actually built or finished better than its comparables.

Commercial property adds another layer. Mass appraisal for income-producing property still leans on area-level income and expense assumptions, vacancy rates, and capitalization rates. A single property appraisal instead works from the subject’s actual rent roll, expenses, and vacancy. That can land in a very different place than the area norm.

CPAs run into this gap from a different angle. If a client’s accountant is using the assessed value for anything beyond the tax bill, look closer. Common examples include a cost segregation study, a basis calculation, or an estate filing. The assessed value is a mass appraisal output, not an opinion of that specific property’s fair market value. Treating it as one can carry the model’s blind spots into a return or a filing where they don’t belong. When that number does more than pay the tax bill, ask whether an independent appraisal should back it up.

What This Means When You’re Building an Appeal

None of this makes the assessor’s number wrong. Mass appraisal is a recognized, widely used method. Cook County publishes self-evaluation reports using measures the International Association of Assessing Officers developed. That means the office holds itself to an outside standard. Still, a mass appraisal output and a single property appraisal are different kinds of evidence. The Board of Review treats them differently, especially given the record filing volumes the office has handled in recent seasons.

Consider a two-flat in a pocket of a neighborhood where the recent comparable sales were newly rehabbed units. The CAMA model might value the subject as though it shares those upgrades, landing at $420,000. A single property appraisal, developed from the property’s actual, unrehabbed condition, might instead support something closer to $340,000. That’s a gap of roughly 19 percent. It’s worth building a case around, not because the model is broken, but because the subject fell outside the model’s view.

The assessed value itself is a useful first filter for whether that gap is worth an appraisal’s cost. If it lines up with what you’d expect from recent sales in that pocket, the model probably did its job. If it doesn’t, that’s usually where mass appraisal’s blind spots and the client’s actual situation intersect. It’s worth documenting before the township’s filing window closes.

Deciding When the Gap Is Worth Documenting

The question isn’t whether mass appraisal is accurate in general. It usually is, since that’s what the method is designed for at scale. The real question is whether it’s accurate for one property, this year, given its condition and its actual comparables. Sometimes the answer is specific to the property, not the neighborhood. That’s the moment for an independent appraisal built to USPAP Standards 1 and 2. The assessor’s own number instead follows township-wide standards. Get that documentation before the appeal window closes, not after.

Test the Assessor’s Number

Sometimes the model’s number and the real property don’t match. An independent appraisal gives you a number built for that property alone.

Get an Independent Value

Frequently Asked Questions

How does the Cook County Assessor value my property?

The Assessor’s Office uses a Computer Assisted Mass Appraisal system. It applies statistical models built from years of sales data and property characteristics. Those models run across every home in a township at once. Analysts then review the results neighborhood by neighborhood.

Why is my assessment higher than what my property would actually sell for?

Mass appraisal relies on recent sales nearby and characteristics on file, not a walk-through of your specific property. Deferred maintenance, an outdated layout, or damage that hasn’t been repaired usually doesn’t show up unless someone reports it.

Is the assessor’s number an appraisal?

No. It’s a mass appraisal estimate, governed by USPAP Standards 5 and 6. A single property appraisal is a separate discipline under USPAP Standards 1 and 2. It’s built around one property’s own inspection and comparables.

How accurate are Cook County assessments?

The Assessor’s Office publishes self-evaluation reports using measures the International Association of Assessing Officers developed. The Illinois Department of Revenue also runs its own sales ratio studies to check assessment levels. Both are aggregate measures, so they can look solid countywide while still missing the mark on one property.

What’s the real difference between mass appraisal and a single property appraisal?

Mass appraisal values many properties at once using shared data and statistical models. A single property appraisal values one property using its own inspection, condition, and comparables. Both aim at market value, but they start from opposite directions.

Property-Specific Work for Property Tax Attorneys and CPAs

PahRoo has built Cook County appeal valuations for over two decades. Each report starts from the subject property’s own condition and comparables, not a countywide model. Michael Hobbs and the appraisal team hold MAI and SRA credentials. They prepare reports to USPAP Standards 1 and 2 for both residential and commercial property. For more on how that documentation supports a filing, see our Board of Review appeal guide. You can also explore PahRoo’s full appraisal services.


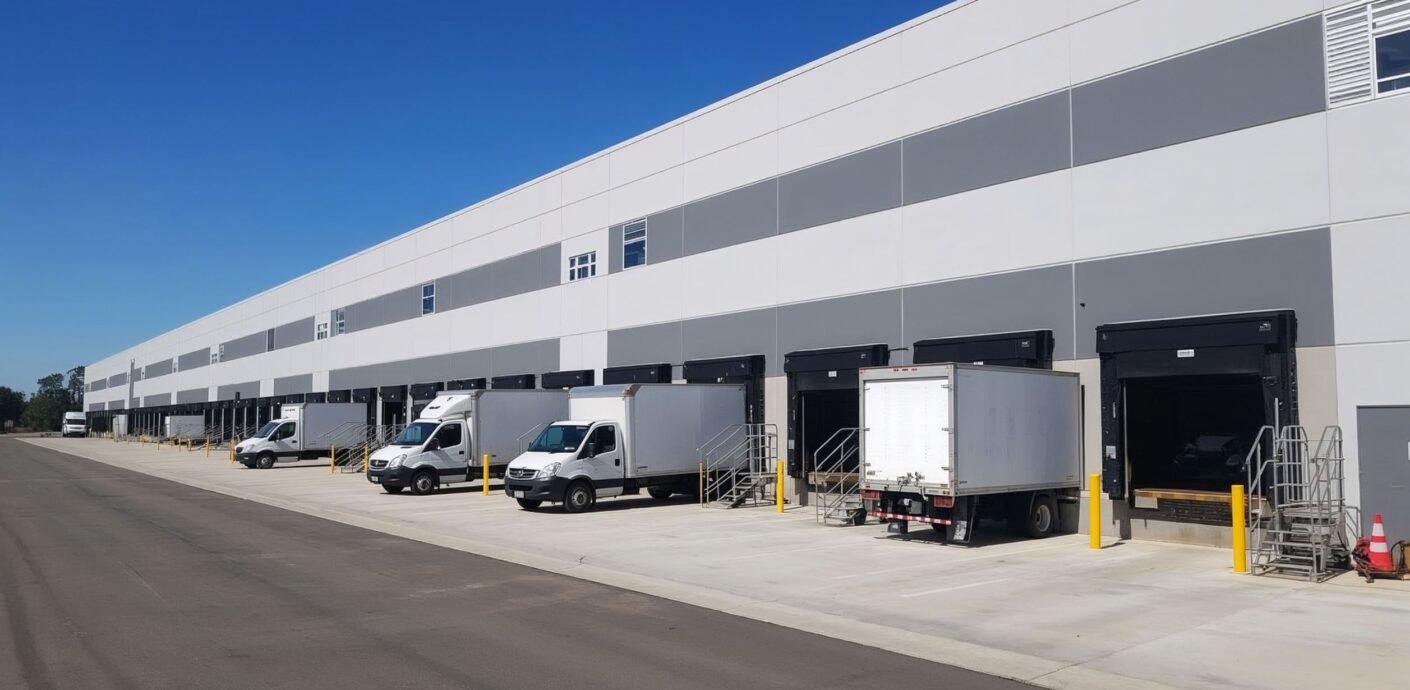
Modern distribution center with loading docks, subject of an industrial property appraisal
What Your Warehouse’s Walls Are Really Hiding

An industrial property appraisal comes down to a simple question. How fast can product move through this building, and how much space does it hold while doing it? Curb appeal barely matters here. A plain concrete box with the right clear height and enough dock doors can out-value a prettier building down the street. Instead, the reason sits in the numbers behind the walls.

By the end of this article, you’ll know:

  • The five factors that carry the most weight in an industrial valuation.
  • Why clear height and dock ratios move value more than square footage alone.
  • What is fueling warehouse and logistics demand right now, and what it means for your number.

What an Industrial Property Appraisal Weighs Most

Five factors do most of the work in an industrial valuation.

  • Location inside the logistics network. Proximity to highways, intermodal rail, and the labor pool that staffs the building.
  • Clear height and functional layout. How much usable cubic space the building offers, not just its footprint.
  • Loading and circulation. Dock door count, trailer parking, and truck court depth relative to building size.
  • Tenant credit and lease structure. Who is paying rent, on what terms, and for how long.
  • Building age and systems. Power capacity, sprinkler class, and the capital needed to bring the space current.

Most industrial buildings, in practice, get valued through a blend of two approaches. Leased distribution centers and multi-tenant parks lean on the income approach. A buyer there is purchasing the rent stream, not just the shell. Owner-user buildings lean harder on the sales comparison approach instead. Appraisers weigh those sales against similar buildings in the same size and height class. The cost approach plays a supporting role too, mostly on newer or purpose-built facilities. Our commercial appraisal services also cover all three, across office, retail, and industrial property.

Income, NOI, and the Cap Rate Behind the Number

For leased industrial, the rent roll gets read closely. Contract rents get compared against market rents. Expirations then get mapped across the holding period, and the reimbursement structure gets checked line by line. Industrial leases run triple net far more often than office leases do. The tenant typically covers taxes, insurance, and most maintenance instead of the landlord. So that keeps the landlord’s expense load lighter, and the income more predictable. That predictability is part of why industrial has held cap rates tighter than office through the same rate cycle. We walked through how that income figure gets built in our guide to net operating income in commercial real estate. The same mechanics apply here. Tenant concentration still matters too. A single-tenant distribution building lives or dies with one renewal decision. So appraisers weigh that risk against the size of the rent check.

Clear Height, Docks, and the Physical Specs That Move Value

Clear height matters more than almost any other industrial spec. It is the unobstructed vertical space from the floor to the lowest hanging obstruction. That obstruction could be a joist, a light, or a sprinkler head. Still, older buildings across the Chicago market commonly top out around 24 to 28 feet. Modern Class A distribution space runs 32 to 36 feet instead. Large e-commerce fulfillment buildings increasingly push past 40 feet to support automated storage systems. That gap is not cosmetic. Moving from a 30-foot to a 36-foot clear height can add 10 to 25 percent of usable storage capacity. It does that without adding a single square foot to the building’s footprint. So appraisers price that extra cubic space directly into value.

Dock doors, trailer parking ratio, and column spacing round out the physical picture. A building with too few docks for its size creates a bottleneck. That bottleneck shows up as functional obsolescence in the appraisal. It happens even when the square footage checks every box on paper. Brokers advising an owner ahead of a listing can get ahead of this instead of explaining it after the fact. Pull the actual clear height and dock count before setting an asking price. Then anchor the comp set to buildings in the same height class, not the metro average. An appraisal that lands under the listing price on an older building usually traces back to a spec gap, not a market swing. So flagging it early keeps the deal from stalling at the lender’s desk.

Why Logistics and E-commerce Demand Is Driving Industrial Value

Industrial has been a standout sector for years. The current data backs that up. According to CBRE’s Chicago Industrial Figures for the second quarter of 2026, the metro’s industrial availability rate fell to 8.6 percent. That is down 30 basis points from the prior quarter. Net average asking rents climbed to $9.30 per square foot, up 7.4 percent year over year. Net absorption jumped to 6.1 million square feet in the quarter. That is well ahead of the 1.1 million square feet absorbed in the first quarter. Another 11.8 million square feet remained under construction, split evenly between speculative and build-to-suit projects.

Nationally, CBRE’s second-quarter research reported the first decline in industrial vacancy since 2022. Demand broadened beyond third-party logistics providers too, as manufacturers picked up a larger share of leasing activity. E-commerce fulfillment, manufacturing reshoring, and tighter big-box supply are feeding the same story from different directions. For an appraisal, that shows up as stronger market rent growth assumptions. In many submarkets, cap rates have also held firmer than other property types through the same financing environment.

The Number Should Match the Building, Not the Market Average

A market average is only a backdrop. Still, it does not appraise your specific building. Two distribution centers half a mile apart can carry very different values. Clear height, dock ratio, and lease structure decide that, not the address. Before a sale, refinance, or partnership buyout, get a number built from the building’s actual specs and tenants instead. After all, a market headline is not a substitute.

Ready to Put a Real Number on Your Industrial Building?

PahRoo appraises warehouses, distribution centers, and manufacturing buildings across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples.

Request a Commercial Appraisal Quote

Frequently Asked Questions

How is industrial property appraised?

Most industrial buildings are valued through a blend of the income approach and the sales comparison approach. Leased distribution centers rely mainly on income, built from the rent roll, market rents, and expenses. Owner-user buildings lean more on comparable sales of similar buildings in the same size and clear height class. The cost approach plays a supporting role, particularly on newer or purpose-built facilities.

What is clear height in a warehouse?

Clear height is the unobstructed vertical space from the floor to the lowest hanging obstruction. Common examples are a joist, a light, or a sprinkler head. Older industrial buildings often run 24 to 28 feet. Modern Class A distribution space commonly runs 32 to 36 feet, and large e-commerce fulfillment buildings increasingly reach 40 feet or more to support automated storage systems.

Why is industrial real estate in such high demand?

E-commerce fulfillment, reshoring of manufacturing, and a slowdown in new construction have kept demand ahead of supply in most markets. CBRE’s second-quarter 2026 research recorded the first national decline in industrial vacancy since 2022. Manufacturers also took a growing share of leasing activity alongside traditional logistics tenants.

What is a distribution center worth?

There is no single number that applies across a market. Value depends on the building’s clear height, dock doors, and trailer parking ratio. It also depends on tenant credit, lease term, and location relative to highways and rail. Two similar-sized buildings in the same submarket can carry very different values once those specs are compared.

How does location affect an industrial appraisal?

Proximity to highway interchanges, intermodal rail, and the local labor pool drives both achievable rent and buyer demand. Submarkets along major logistics corridors typically see tighter vacancy and stronger rent growth than the metro average. Appraisers weigh that submarket-level data rather than a single citywide figure.

Built From the Building, Not the Headlines

PahRoo Appraisal & Consultancy appraises commercial property across five markets. That also includes industrial, office, and retail, for owners, investors, brokers, and lenders. For a similar look at income mechanics in another property type, see our office building breakdown of what drives the value of an office building. Or start with our Chicago appraisal services page for scope and timing questions.

Divorce attorney and expert witness appraiser reviewing a defensible appraisal report before trial
What Makes an Appraisal Defensible on the Witness Stand

Consider a hypothetical Oak Park two-flat in a contested divorce. One appraiser says $1,150,000. The other says $960,000. The judge has to pick, and in Illinois the judge has to explain the pick in writing. What decides it is rarely the number. It is which appraiser can still explain the number after an hour of cross-examination. That is what a defensible appraisal expert witness delivers. It is a different product from a lender appraisal.

By the end of this article, you’ll know:

  • What Illinois and federal courts test when an appraiser takes the stand
  • Where reports break under cross-examination, and how to spot weak ones early
  • What to check before you retain, and what the CPA on the case needs

What Defensible Appraisal Expert Witness Testimony Rests On

Under Illinois Rule of Evidence 702, an expert may testify when specialized knowledge will assist the trier of fact. The rule’s committee comment confirms Illinois is a Frye state. But the general-acceptance burden only applies when the opinion rests on a new or novel scientific methodology. The sales comparison, cost, and income approaches are not novel. So in a Cook County divorce, the fight over an appraiser is rarely about admissibility. It is about weight and credibility.

Federal court is stricter on paper. Under Federal Rule of Evidence 702, the proponent must show four things are more likely than not. The testimony helps the court, rests on sufficient facts or data, uses reliable methods, and applies them reliably. That is the Daubert framework. The committee notes add that valuation opinions get judged by the standards of the appraisal field itself. In practice, opposing counsel in state court borrows the same four questions on cross. Was the appraiser qualified? Is the data sufficient? Does the method have standing in the field? Did the appraiser apply it correctly?

Which standard governs is counsel’s call. What an appraiser controls is whether the report answers all four before anyone asks. Our overview of appraisals in divorce proceedings covers the basics. Below is what changes when testimony is likely.

Where Appraisal Reports Break Under Cross-Examination

The attacks are predictable, because they work. The first is the date. A refinance appraisal carries the lender’s effective date and intended use. In a divorce it answers a question the court did not ask. Under 750 ILCS 5/503, the court applies fair market value as of the trial date or another date it sets. The wrong date sinks a report before the comparables come up. Our article on the date of value in a divorce appraisal explains how that date gets chosen.

The second is verification. Did the appraiser confirm each sale, or lift it from the MLS? Did anyone drive past the comps? An appraiser who cannot describe the confirmation loses that comparable in front of the judge.

The third is adjustment support, and this is where most reports fail. The Colorado Division of Real Estate names four: boilerplate that claims paired sales or regression support but shows no analysis, predetermined adjustments reused from file to file, cost figures treated as market reaction, and averages standing in for real comparisons. Each is one question from collapsing on the stand.

The fourth is the file. USPAP requires a workfile holding all data behind the conclusions, including data considered and not used, plus summaries or transcripts of any testimony. Illinois Rule of Evidence 705 lets cross-examining counsel demand the underlying facts. A thin workfile means a thin opinion, and everyone in the room finds out at once.

Then comes the appraiser. An expert who argues the client’s side, moves the number after a phone call, or forgets a prior report on the same property has written the other side’s closing. Independence, after all, is the whole basis for weight.

What a Defensible Report Looks Like on the Page

USPAP, published by The Appraisal Foundation and authorized by Congress in 1989, is the recognized standard for U.S. appraisers. It requires the appraiser to identify the problem before solving it. That means naming the client and intended users, the intended use, the type and definition of value, the effective date, the property’s relevant characteristics, and any assignment conditions. A court-ready report states each on its first pages, and each matches the case.

From there, the report shows its work. Every adjustment ties back to evidence the reader can check: a paired sale, a bracketed range, a documented buyer interview, or a regression. The reconciliation then says which approach carried the weight and why. Extraordinary assumptions, such as an interior the appraiser could not access, appear up front. And the report discloses what research the appraiser did and did not do, as USPAP’s reporting standard requires.

Format matters too. A lender form limits explanation by design. A narrative report written for litigation walks a judge from the data to the number. It is one reason a divorce appraisal and a price opinion land so differently in court.

What Attorneys Should Check Before the Report Is Ordered

Disclosure shapes the retention. Under Illinois Supreme Court Rule 213(f)(3), a retained appraiser is a controlled expert. On interrogatory you must disclose the subject matter, the opinions and their bases, the qualifications, and any reports. Rule 213(g) then limits direct examination to those disclosures. So the report becomes an exhibit the day the appraiser signs it, and the number cannot drift at trial. Retain early, then, not late.

Vet the witness first. Ask how many times the appraiser has testified at deposition and at trial. Find out whether any court has excluded or limited that testimony. Ask whether they have worked for both husbands and wives, because a one-sided record is a cross-examination theme. Designations matter too; the MAI and SRA require experience beyond a state license. And ask whether they will produce the workfile without a fight.

Then scope the engagement in writing. Name the effective date, or two dates if the case needs a current and a retrospective value, as a quitclaim transfer mid-case often does. State the intended use as the dissolution proceeding. If the appraisal is joint, name both counsel as intended users. Confirm a fixed fee with no tie to the outcome. Confirm a full inspection, which matters most on an estate home with custom features. Our guide to disputed property value in an Illinois divorce lists the records to gather first.

The statute adds one more path. Under 503(l), the court may consult its own financial expert, who is subject to examination and cross-examination too.

For the CPA on the Case

Accountants in a divorce carry the real estate value into the marital balance sheet, the tracing schedule, or a business valuation. If the appraisal falls, those schedules fall with it. Four checks protect your work.

First, match the effective dates. If the business valuation is as of December 31 and the house is as of a May inspection, the balance sheet mixes two markets. So get the appraisal to the same date, or document the bridge. Second, match the definition of value. Section 503(k) calls for fair market value. A lender’s market value definition, or a fair value standard in a business valuation, may not line up. Third, check the arithmetic in the adjustment grid before the number lands in your schedule. The appraiser’s addition error becomes your error on the exhibit. Fourth, if rental property sits inside a business you are valuing, agree with the appraiser in writing on who values the real estate and who values the enterprise. Otherwise the same rent counts twice or not at all.

Keep the appraisal in your permanent file too. The Supreme Court’s standard matrimonial interrogatories ask each party about appraisals from the prior three years and about any net worth statements prepared for them. Whatever you build on the appraisal gets disclosed, so read the report first.

Retain the Witness Before You Order the Report

Sequence is what makes the report defensible. Choose the appraiser you would put on the stand, then order the report from that person. Fix the effective date and intended use in the engagement letter. Get the report early enough to read it, question it, and let the appraiser fix anything that will not hold. A report produced the week before disclosure draws the hardest cross. One built for testimony from the first page usually settles the value question before anyone reaches the courtroom.

Is Your Appraiser Ready for Cross-Examination?

PahRoo prepares litigation appraisals built for Rule 213 disclosure, deposition, and trial. Michael Hobbs, MAI, SRA, signs the report and takes the stand to defend it in Cook County and across our other markets.

Retain an Appraisal Expert Witness

Frequently Asked Questions

What makes an appraisal defensible in court?

It states an effective date, intended use, and definition of value that match the case, uses comparable sales the appraiser verified, supports every adjustment with market evidence, explains which approach carried the weight, and rests on a complete workfile. Then the appraiser explains each choice under cross-examination without changing the number.

Can an appraiser be an expert witness?

Yes. Under Illinois and federal Rule 702, a witness qualified by knowledge, skill, experience, training, or education may give opinion testimony that helps the court. A licensed appraiser with experience in the property type and market generally qualifies. Weight depends on the method and the support behind it.

What happens during appraiser cross-examination?

Opposing counsel tests the effective date and intended use, comparable verification, the evidence behind every adjustment, the workfile, the appraiser’s qualifications and testimony history, and any prior reports on the property. Illinois Rule of Evidence 705 lets counsel demand the underlying facts and data.

What is a Frye or Daubert challenge?

Both ask a judge to exclude expert testimony. Illinois follows Frye, which requires general acceptance only when an opinion rests on a new or novel scientific methodology. Federal courts follow Daubert, which requires sufficient data and reliable, reliably applied methods. Standard appraisal methods are rarely excluded, so most challenges go to weight.

How do you choose an expert appraiser for a divorce?

Look for experience with the property type and price tier, deposition and trial testimony that no court has excluded, work for both sides of prior disputes, an Appraisal Institute designation such as the MAI or SRA, and a willingness to produce the workfile. Then fix the effective date, intended use, and fee in the engagement letter.

Litigation Appraisal and Testimony From One Appraiser

Family law attorneys and forensic accountants across Cook County and the wider Chicago area, along with Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, bring PahRoo Appraisal & Consultancy into contested cases. Since 1999 the firm has prepared appraisals for dissolution, estate, and tax matters, and Michael Hobbs, MAI, SRA, signs every report and is available for deposition and trial. See our residential appraisal services, or contact us with the case caption and the disclosure deadline.

Appraisal report and numbered exhibits prepared as VAB hearing evidence for a Florida special magistrate
VAB Hearing Evidence That Holds Up in Florida

Collier County’s window to petition the Value Adjustment Board closes today, September 11, at 5 PM in the Clerk’s office and 11:59 PM online. If your client filed, the deadline is no longer the problem. The hearing is. From here on, VAB hearing evidence decides the case. A special magistrate weighs it, and that magistrate is a certified appraiser who has already read the property appraiser’s file. So here is what the evidence has to show, when to exchange it, and where petitions fall apart.

By the end of this article, you’ll know:

  • Who the special magistrate is and what the recommendation has to contain
  • What the statute makes you prove, and what the appraisal has to say
  • The 15-day exchange, Collier’s upload rules, and the hearing-day mechanics

Who Is Sitting Across the Table

In Collier County, the five-member board does not hear petitions itself. Florida requires larger counties to appoint special magistrates. A magistrate who hears real estate valuation must be a state certified appraiser with at least five years of experience. The magistrate takes testimony, then writes a recommendation with proposed findings of fact, conclusions of law, and reasons. The board may then adopt it without another hearing.

Two more facts shape the room. A magistrate may not represent anyone before that board in a year of service. And the board may not accept an appraisal in any year its author serves as a magistrate there. So check your appraiser’s name against the current magistrate list before you exchange evidence. If they overlap, the report is out.

What VAB Hearing Evidence Has to Prove

Section 194.301 of the Florida Statutes sets the contest. The property appraiser earns a presumption of correctness by showing, more likely than not, that the assessment followed section 193.011 and accepted appraisal practice. Then the burden shifts. The petitioner has to show, more likely than not, that the assessed value does not represent just value. The old “every reasonable hypothesis” test no longer applies. So the petitioner need not prove the assessment indefensible. Only that it is more likely wrong than right.

If the petitioner clears that bar, the board sets the value itself. But only if the record holds competent, substantial evidence of value under section 193.011. Otherwise the matter goes back to the property appraiser with directions. A petition can win the argument and still lose the number, because nobody put a supportable value in the record. The appraisal fills that gap.

The evidence has to track the eight factors in section 193.011. Those are present cash value in an arm’s-length sale, highest and best use, location, size, cost and replacement value, condition, income, and net proceeds of sale. A magistrate who appraises for a living reads the report against that list. Skip highest and best use, or treat a distressed sale as arm’s length, and the report hands the property appraiser its rebuttal.

The 15-Day Exchange and Collier’s Upload Rules

At least 15 days before the hearing, the petitioner must give the property appraiser three things: an evidence list, copies of every document the board will see, and a summary of witness testimony. The property appraiser owes the same package, plus the property record card, on the same 15-day clock. Miss it, and the Clerk reschedules the hearing. One more rule matters. If the property appraiser asked for a document in writing and the petitioner refused, the magistrate may not accept it later. Withholding a rent roll in September can bar it in November.

Collier layers its own procedure on top. Under the Clerk’s evidence procedures, petitioner evidence goes into the Axia portal as a PDF under 60 MB, every page numbered, at least 15 calendar days before the hearing. Uploading to Axia does not start the statutory exchange by itself. The package still has to reach the property appraiser. A petitioner who will not attend can still have evidence considered. But it must be uploaded before the hearing, or delivered in two paper copies to the Clerk by 9:00 a.m. at least two workdays ahead.

What the Appraisal Itself Must Show

The effective date is January 1 of the tax year. Everything in the report has to anchor there: the sales, the condition of the property, the market it describes. A magistrate will discount a report that leans on sales closed after that date, or on a condition that changed in the spring.

The sales grid usually decides the case. Each comparable needs a closing date before January 1, confirmation of an arm’s-length sale, and adjustments a reader can follow. In Naples, the usual ones are condition, size, location, and waterfront or golf frontage. The eighth factor, net proceeds after usual costs of sale, is a Florida-specific point. A certified magistrate expects to see it addressed, not assumed. So is highest and best use, especially for older homes where the land carries most of the value.

Then the report should engage the property appraiser’s evidence directly. The property record card sits in the exchange package, and it lists the characteristics the mass appraisal model used. If the card gets the square footage, effective age, or a long-gone pool wrong, say so with a dated photograph and a measurement. The statute also lets the board consider assessments of comparable properties in the same neighborhood. Whether to press that angle is a call for counsel. The appraiser’s job is to make the sales evidence stand alone.

Hearing-Day Mechanics

The Clerk must send the hearing notice at least 25 calendar days ahead. Hearings often run in blocks. A petitioner cannot be made to wait more than two hours past the start. If that happens, the petitioner may leave and be rescheduled at no cost. Each side also gets one reschedule for good cause. To appear by video or phone, ask in writing at least 10 calendar days before the hearing.

Either party can require testimony under oath, and cross-examination is a right. A report that reads well loses ground fast when its author cannot explain a $40,000 location adjustment from memory. The written decision follows within 20 calendar days after the board’s last session day.

For Owners: The Weeks Between Filing and the Hearing

If you own the property and your attorney filed, four things are yours to do. First, pay the tax bill on time and in the right amount. A petitioner contesting value must pay all non-ad valorem assessments and at least 75 percent of the ad valorem taxes, less any early-payment discount, before they go delinquent. Otherwise the board denies the petition by April 20. Second, order the appraisal now, not when the hearing notice arrives. The report has to be finished, reviewed, and exchanged 15 days before the hearing.

Third, decide whether you will attend. You do not have to. Your attorney, a licensed appraiser, a licensed broker, a CPA, or someone with your written authorization can represent you. Collier will also consider uploaded evidence in your absence. Fourth, if the property appraiser sends a written request for a document, answer it. Refusing can keep that document out of your own case.

Owners of second homes in Naples and Collier County tend to miss one more thing. The appraiser needs access to the property, and the effective date is last January 1. If the house was mid-renovation or mid-repair on that date, gather the photos and contractor invoices now. They show condition on the only date that matters.

Download the VAB Hearing Prep Sheet

Two pages: every deadline and exchange rule with its statute section, and the evidence checklist to finish before the 15-day exchange.

Get the Prep Sheet

Build the Record Before You Argue the Number

A VAB petition turns on the record, and the evidence exchange is due 15 days before anyone speaks. So the sequence for counsel is fixed. Confirm the appraiser is not on the magistrate list. Get the report dated to January 1 and written to the eight factors. Exchange it on time with numbered pages. Answer every written request from the property appraiser. Do that, and the hearing becomes a conversation about value between two appraisers. That is the contest the statute was written for. Skip a step, and the magistrate never reaches the number. Our appraisal services page covers tax appeal assignments, and the appraisal FAQ answers the timing questions that come up between filing and hearing.

Hearing Date Set and No Appraisal Yet?

PahRoo prepares January 1 appraisals for Collier County VAB petitions, written to section 193.011 and delivered in time for the 15-day exchange.

Prepare for Your Hearing

Frequently Asked Questions

What happens at a Florida VAB hearing?

A special magistrate takes testimony from both sides, reviews the evidence exchanged 15 days earlier, and may ask questions. Witnesses can be sworn, and each side may cross-examine. The magistrate then recommends, with findings of fact and conclusions of law, and the board makes the final decision.

Do I need an appraisal for a VAB petition?

Florida law does not require one. But the petitioner must prove by a preponderance that the assessed value does not represent just value, and the board can then set the value only if the record holds competent, substantial evidence meeting section 193.011. An appraisal dated to January 1 supplies it.

Can I appeal without appearing at the hearing?

Yes. A petitioner may be represented by an attorney, a licensed appraiser or broker, a CPA, an employee, a person holding a power of attorney, or an uncompensated person with written authorization. In Collier County, evidence uploaded before the hearing can be considered in the petitioner’s absence. Electronic appearance needs a written request 10 days ahead.

What is a special magistrate?

An independent hearing officer appointed by the Value Adjustment Board. For real estate valuation, the magistrate must be a state certified appraiser with at least five years of experience and may not represent petitioners before that board in the same year. The board may adopt the recommendation without another hearing.

What is the burden of proof at a VAB hearing?

The assessment is presumed correct if the property appraiser proves by a preponderance that it complied with section 193.011 and accepted appraisal practices. The petitioner must then prove by a preponderance that the assessed value does not represent just value. Statute rejected the old every-reasonable-hypothesis standard.

Appraisal Support for Collier County VAB Petitions

Property tax attorneys and owners of Naples-area homes and commercial property engage PahRoo Appraisal & Consultancy for January 1 appraisals written for Value Adjustment Board hearings, along with tax appeal work in Chicago and Cook County, Dallas-Fort Worth, Philadelphia, and Phoenix. To discuss a petition that already has a hearing date, contact our team.

Attorney reviewing a luxury home appraisal report in a high-asset divorce case
Appraising Luxury and Estate Homes in High-Asset Divorce

In a high-asset case, the house is rarely just a house. It might be a 9,000-square-foot estate in Winnetka with a coach house, or a full-floor Gold Coast condominium. The luxury home appraisal divorce counsel puts in front of the court has to survive three readers. An opposing expert, a skeptical judge, and a spouse who is sure the number is wrong. Reports built for lending were never designed for that.

By the end of this article, you’ll know:

  • Why estate and luxury homes are harder to value, and what a defensible method looks like
  • How appraisers find and adjust comparable sales when almost nothing matches
  • What to ask before you retain the appraiser, and how a broker can strengthen the file

What Makes a Luxury Home Appraisal Divorce-Ready

Three things separate a high-value home from the typical marital residence, and each adds risk to the final number. First, the buyer pool is thin. A property at the top of the Kenilworth market competes for a small group of qualified buyers. Second, the features are bespoke. No two estates share the same wine cellar, the same lot, or the same view. Third, the sales data is sparse. A submarket can produce only a handful of closings above a given price in a year.

Illinois law raises the stakes. Under 750 ILCS 5/503, the court must make specific factual findings on the value of each asset. It applies a fair market value standard. And it values the property as of the trial date, or another date the court sets. So the appraisal cannot hedge. It has to state a number, tie it to a date, and show the evidence.

That is where standards come in. The Uniform Standards of Professional Appraisal Practice, published by The Appraisal Foundation, govern how the analysis is developed and reported. A report that follows them names the effective date, explains the scope of work, and supports every adjustment. One that skips those steps hands opposing counsel a script. Our overview of appraisals in divorce proceedings covers the basics. Below is what changes at the top of the market.

Why Few Comparable Sales Is Not an Excuse

Attorneys often hear that there are no comps. In practice that means the appraiser has to work harder. The search widens in three directions.

Geography comes first. A Lake Forest estate may compete with Winnetka, Glencoe, and Barrington Hills rather than the next street over. The buyer choosing among them is the same buyer. The same logic holds in our other markets. A Highland Park buyer in Dallas may also be looking in University Park. Main Line buyers in Philadelphia shop across several townships. A Port Royal buyer in Naples is often weighing Aqualane Shores too. The appraiser then makes a supported location adjustment instead of pretending the sales are next door.

Time comes second. A luxury sale from 18 months ago can still be useful. But the appraiser has to adjust for market movement between that closing and the effective date. That adjustment needs evidence, such as repeat sales or price trends in the same tier, not a guess.

Then the appraiser brackets. Ideally one comparable is superior to the subject and one is inferior. Then the value falls inside a range the market actually produced. Paired sales analysis, where two similar sales differ mainly in one feature, is how the size of an adjustment gets tested. When the paired data is thin, the cost approach steps in as a check. It adds land value from vacant or teardown sales to the depreciated cost of the improvements. It rarely drives the number on an older estate, but it exposes an inflated sales comparison quickly.

Bespoke Features and the Superadequacy Problem

Custom features are where luxury appraisals go wrong most often. An owner who spent $180,000 on a wine cellar expects to see $180,000 in the value. The market usually disagrees.

Appraisers call the excess a superadequacy. The Dictionary of Real Estate Appraisal defines it as an excess in the capacity or quality of a structure or component, judged by market standards. It is a form of functional obsolescence, and it shows up in luxury homes more than anywhere else. The more unusual the feature, the smaller the pool of buyers who will pay for it.

Consider a hypothetical estate in Hinsdale with that $180,000 cellar. Suppose paired sales in the tier show buyers paying roughly $60,000 more for a home with a serious cellar. Then the contributory value is $60,000. The other $120,000 was consumed, not invested. The same math applies to indoor pools, sport courts, elevators, and eight-car garages. The report should state what each feature contributes and show how that figure was derived.

A prior lending appraisal from a refinance is useful here but not decisive. It was written for a different purpose, often on a form that limits explanation. Counsel should still request it, as our guide to disputed property value in Illinois divorce explains. Then expect the litigation appraisal to go well beyond it.

Who Should Appraise an Estate Home in a Divorce

Not every licensed appraiser should take this assignment, and USPAP says so. The Competency Rule requires an appraiser to determine, before agreeing to an assignment, that they can perform it competently. Competency covers the property type, the market, and the intended use. A residential appraiser who works mainly on $500,000 lender assignments may be fully licensed. That same appraiser can still be outside their competence on a $6 million estate headed to trial.

Ask four questions before you retain. How many properties above the relevant price point has the appraiser valued in this submarket in the last three years? Which designation do they hold? The Appraisal Institute awards the MAI for all types of real property and the SRA for residential work. Both require demonstrated experience beyond a state license. Have they testified, and how did the report hold up? And can they support the date of value the case needs, including a retrospective date if the court sets one? Our article on the date of value in a divorce appraisal explains why that last question matters.

Then plan for disclosure. Illinois Supreme Court Rule 213(f)(3) requires a party, on interrogatory, to disclose a controlled expert’s opinions, their bases, qualifications, and reports. A luxury appraisal built to be disclosed reads differently from one built to close a loan. The reasoning is on the page, the comparables can be verified, and the appraiser’s file is ready for deposition.

What Brokers Can Bring to the Appraisal

Luxury brokers hold data the MLS lacks. Off-market sales, buyer feedback on specific features, and the real reason a listing sat for months rarely reach a public record. In a divorce, that knowledge can make or break the comparable analysis.

If you have listed or sold in the subject’s tier, this is what helps the appraiser most. Send the full listing history for the subject, including expired and canceled listings. Prior exposure to the market is evidence of what buyers would not pay. Share any private sales you can verify with a closed price and date. Pass along showing feedback on features the appraiser has to value, such as the indoor pool nobody wanted or the view everyone mentioned. And be candid about concessions and seller credits. A recorded price with, say, $150,000 in credits behind it is not the price the comparable grid should carry.

Brokers also benefit on the back end. If the settlement leads to a sale, a court-ready appraisal gives you a defensible list price. It also protects your own price opinion. A broker price opinion serves a listing decision, but it is not the standard courts apply to a contested value. Our comparison of a divorce home appraisal and a price opinion explains why.

Put the Estate Home’s Value on the Record Early

High-asset cases move slowly, but expert deadlines do not. Retain the appraiser as soon as the property is identified as contested. Agree the effective date with opposing counsel if you can. Then give the appraiser access to the whole property, not a walkthrough of the main floor. If a buyout is on the table, the same report anchors the equity math, as our marital home buyout guide shows. The goal is one number, built on evidence a judge can follow, delivered in time to use it.

Is the Estate Home the Largest Asset in the Case?

PahRoo appraises luxury and estate homes for divorce counsel in Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, with comparables you can verify and an appraiser who will defend the work on the stand.

Order a Luxury Home Appraisal

Frequently Asked Questions

How is a luxury home appraised in a divorce?

The appraiser inspects the whole property, identifies the competing luxury submarkets, and analyzes comparable sales adjusted for location, time, size, and features. Paired sales and the cost approach test the adjustments. The report ties the value to the effective date the court uses and explains every step so it can be defended in testimony.

Why do luxury home appraisals vary so widely?

Thin sales data and custom features leave more room for judgment. Two appraisers may select different comparables, adjust for a feature differently, or treat a costly improvement as full value when the market pays a fraction. A wide gap usually signals weak support in one report rather than a market that cannot be measured.

How do you find comps for a unique home?

Widen the search to the submarkets the same buyer would consider, extend the time frame with a supported market adjustment, and bracket the subject with a superior and an inferior sale. Verified off-market sales, often known to luxury brokers, can fill gaps the MLS leaves.

Who should appraise an estate home in a divorce?

An appraiser with documented experience in the property type and price tier, ideally holding an Appraisal Institute designation such as the MAI or SRA, who has testified and can support the effective date the case requires. USPAP’s Competency Rule puts the burden on the appraiser to confirm this before accepting the work.

Do custom features add their full cost to the appraised value?

Rarely. A feature contributes what buyers in that market will pay for it, which is often less than it cost to build. The excess is called a superadequacy. The appraisal should state each feature’s contributory value and show the market evidence behind it.

Independent Valuation for High-Asset Divorce Cases

Since 1999, PahRoo Appraisal & Consultancy has valued estate homes, luxury condominiums, and complex residential property across Cook County and the wider Chicago area, along with Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, signs every report and is available for testimony. See our residential appraisal services, or contact us to discuss a high-value property.


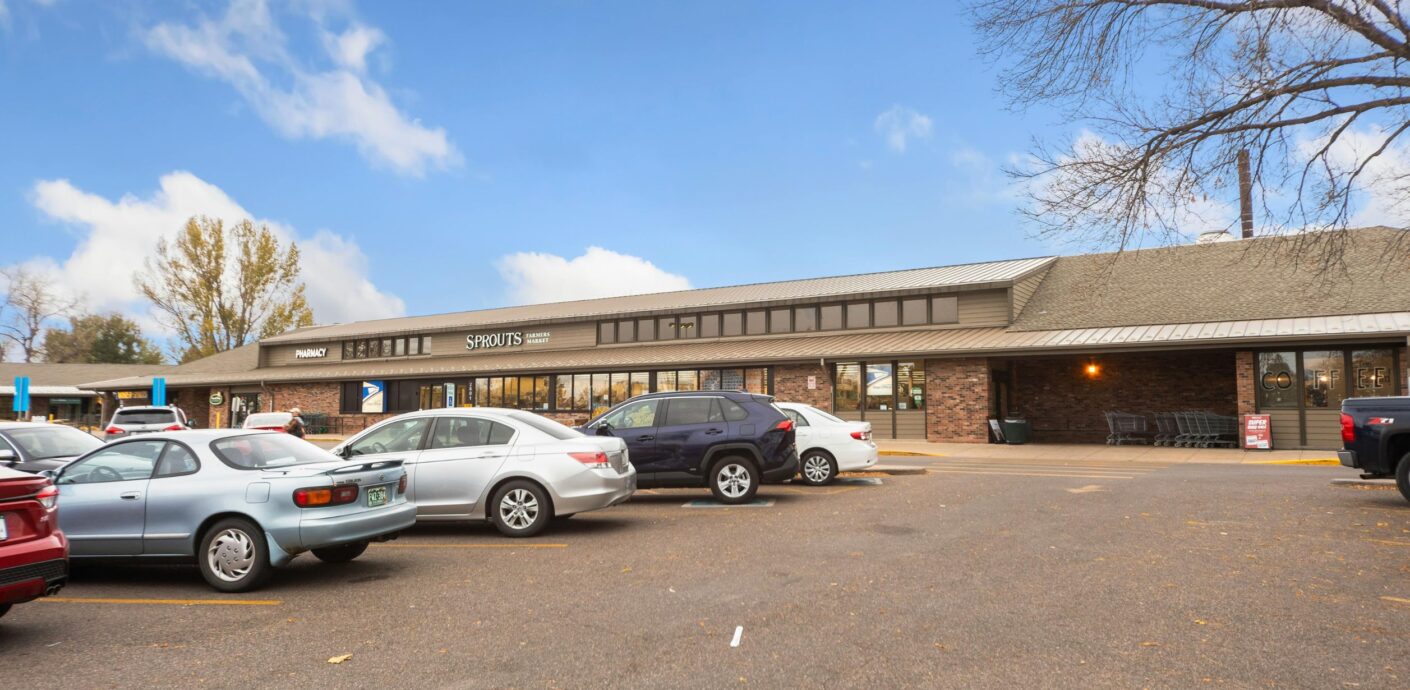
Neighborhood strip center with grocery anchor and inline shops, the subject of a retail property appraisal
Retail Property Appraisal and What Moves the Value

Two strip centers on the same road, same size, same age, same asking price. One is worth 15 percent more than the other, and nothing about the buildings explains why. The leases do. A retail property appraisal spends less time on the roof and the parking lot than brokers expect. It spends far more on who signed the leases, how long they run, and what happens to the rent when they end. So here is how location, tenants, and lease terms each move the number.

By the end of this article, you’ll know:

  • How trade area, access, and co-tenants set the ceiling on retail rent
  • Why tenant credit and tenant category can move a cap rate more than the building does
  • What a rent roll and lease abstract have to show before the appraisal can start

Location Sets the Ceiling

Retail rent is a function of what a tenant can sell from that spot. So the appraiser starts outside the property line. The trade area is the geography a center actually draws from. That may be a one-mile ring for a grocery-anchored neighborhood center, or a 20-minute drive for a destination power center. Population, household income, and daytime employment inside that area tell the appraiser what rent the market can bear. Then traffic counts, visibility, and access decide whether a tenant can capture it.

Co-tenancy matters almost as much as the corner. An inline space next to a strong grocer rents for more than the same space next to a vacant box. The grocer brings the cars. Anchors, shadow anchors across the street, and out-parcel pads all shape the rent an inline tenant will pay. So when the appraiser selects rent comparables, the first filter is not square footage. It is whether the comparable center has the same kind of draw.

Tenants Set the Cap Rate

Once the rent is established, the question shifts to how reliable it is. Two centers with the same net operating income can trade at very different prices. A buyer pays more for income that is likely to arrive. A national credit tenant on a long lease is income a buyer can underwrite. A first-year local operator is a bet. The appraiser reflects that difference in the capitalization rate. In practice, the spread between a credit-anchored center and a local-tenant center can be wider than the spread between a new building and an old one.

Tenant category matters too, and the national numbers show why. The Census Bureau’s July 2026 retail sales release put total retail and food services sales up 5.0 percent from a year earlier. Underneath that headline, nonstore retailers were up 7.7 percent and restaurants and bars were up 5.0 percent. Furniture stores were down 1.2 percent. So a center full of restaurants and service tenants is riding a different current than a center full of furniture showrooms. The appraiser’s vacancy and credit loss assumptions should say so.

Where tenant sales are available, the occupancy cost ratio is the health check. Rent plus recoveries, divided by sales, tells the appraiser whether a tenant can afford its lease. A tenant paying more of its sales than its category can sustain is a renewal risk no matter what the lease says. Most appraisals do not get sales data, though. Then the appraiser leans on category trends and the tenant’s public reporting where it exists.

Lease Terms That Change the Number

This is the section that does the work, and the one most rent rolls are least prepared for. The lease structure comes first. Under a triple net lease, the tenant pays its share of taxes, insurance, and common area maintenance on top of base rent. So the landlord’s net income sits close to the base rent. Under a gross lease, the landlord absorbs those costs, and rising taxes come straight out of net operating income. A modified gross lease splits them. Two centers with identical base rents can have very different net income. That is why our guide to net operating income starts with the recovery structure.

Term and rollover come next. A center where 40 percent of the income expires within 24 months carries costs a fully leased center does not: downtime, tenant improvement allowances, and leasing commissions. The appraiser models those costs in the year they land. So a long-term rent roll and a short-term rent roll with the same current income do not support the same value under the income approach. Renewal options, and whether they are at fixed rent or market, sit inside the same analysis.

Then the clauses that brokers sometimes skip. A co-tenancy clause lets a tenant reduce rent or leave if an anchor goes dark or occupancy drops below a threshold. So one vacancy can cascade. An exclusive-use clause blocks the landlord from leasing to a competing use. That narrows the pool of replacement tenants. Rent escalations, percentage rent breakpoints, and caps on CAM recoveries all change the income stream. None of them show up on a one-page rent roll. All of them show up in value.

What a Retail Property Appraisal Needs From the Rent Roll

A usable rent roll lists every suite with tenant name, square footage, lease start and expiration, and current base rent. It also shows the escalation schedule, recovery structure, renewal options, and any abatement still running. Behind it, the appraiser needs lease abstracts or the leases themselves for anchors and any tenant over about ten percent of the income. Add the last two years of CAM reconciliations and operating statements. Vacant suites need asking rent and the date they went dark.

When that package is complete, the appraisal moves quickly and the conclusions are defensible. When it is missing, the appraiser fills gaps with market assumptions. Market assumptions rarely favor the seller. The same package is what the buyer’s lender will ask for. So assembling it once serves the listing, the appraisal, and the closing.

A Hypothetical Neighborhood Center

Consider a 25,000 square foot center: a 12,000 square foot grocer on a triple net lease with 11 years left, six inline tenants, and one 1,800 square foot vacancy. Net operating income is $504,000. Suppose the inline leases are staggered, with no more than one expiring in any year, and the grocer is a regional credit. An appraiser might support a 7.0 percent cap rate, indicating $7,200,000.

Now change one fact. Four of the six inline leases expire within 18 months, and two tenants are month-to-month. The grocer has a co-tenancy clause tied to inline occupancy. Same building, same income today. An appraiser might now support an 8.0 percent rate, landing near $6,300,000, and deduct lease-up costs on top. The gap is close to $900,000 before those deductions. Every dollar of it lives in the leases.

Where Owners Get Ahead of the Appraisal

For an owner planning a sale or a refinance, the highest-return work happens before the appraiser is engaged. Renew the tenants whose leases expire inside the next two years, even at a modest concession. Term is worth more than the last dollar of rent. Resolve open co-tenancy exposure by backfilling the space that triggers it. Finish the CAM reconciliations so recovery income is documented rather than estimated. And abstract every lease so the rollover schedule, options, and clauses sit in one place. Each step converts an assumption into a fact the appraiser can cite.

Read the Rent Roll Before You Read the Cap Rate

When a retail appraisal lands on your desk, skip the cover value and go to the rent roll analysis. Check that lease structures are identified suite by suite and the rollover schedule is laid out by year. Check that the anchors’ clauses are addressed by name. Then check that the cap rate reflects the tenants actually in the building, not a survey average. If those pieces are there, the value will hold up with the buyer’s lender. If they are not, the number is a guess with a decimal point. Our overview of the three approaches to value shows how the income analysis fits with the others. For retail, it is nearly always the one that decides.

Pricing a Center With Rollover on the Horizon?

PahRoo appraises retail property from the leases up, with rollover modeling and cap rate support a buyer’s lender will accept.

Request a Retail Appraisal Quote

Frequently Asked Questions

How is a retail property appraised?

Primarily through the income approach. The appraiser analyzes the rent roll and leases to establish net operating income, evaluates tenant credit and lease term to select a capitalization rate, and models lease-up costs for expiring or vacant space. Sales comparison serves as a check on the result, and location analysis of the trade area, traffic, and co-tenancy frames the rent the market will bear.

What is a triple net lease and why does it matter to value?

Under a triple net lease the tenant pays its share of property taxes, insurance, and common area maintenance in addition to base rent. The landlord’s net income is close to the base rent and is insulated from rising expenses. Under a gross lease the landlord absorbs those costs, so the same base rent produces lower net operating income and a lower value.

How does tenant credit affect the cap rate?

Buyers pay more for income they are confident will arrive, so a center anchored by a national or regional credit tenant on a long lease supports a lower capitalization rate than a center leased to local operators on short terms. The appraiser reflects that in the rate, and the spread between the two can move value more than the age or condition of the building.

What is a co-tenancy clause?

A lease provision that lets a tenant reduce rent or terminate if a named anchor closes or center occupancy falls below a set level. It means one vacancy can trigger others. An appraiser reads anchor and major tenant leases for these clauses and accounts for the exposure in the vacancy and credit loss analysis.

What does an appraiser need from the rent roll?

Every suite with tenant name, square footage, lease start and expiration, current base rent and escalations, recovery structure, renewal options, and any abatements still running. Behind the rent roll, the appraiser needs lease abstracts or full leases for anchors and major tenants, two years of operating statements, and the CAM reconciliations.

Retail Valuation From the Lease Up

Brokers, owners, and lenders across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples engage PahRoo Appraisal & Consultancy for retail assignments from single-tenant pads to anchored centers. Our commercial appraisal services page lists the property types we cover, and our article on office building value drivers shows the same lease-first method applied to a different asset class. To discuss a retail property, contact our team.

Adult daughter in the kitchen of an inherited Chicago home before ordering an appraisal for inherited property
Appraisal for Inherited Property Before You Sell or Split

A call we get more often than you would think might run like this. A daughter has just buried her mother. The house in Skokie is paid off. Her brother wants to sell, and the listing agent has already named a price. Nobody has ordered an appraisal for inherited property, and nobody thinks they need one. Then the CPA asks a simple question: what was the house worth on the day Mom died? Silence.

By the end of this article, you’ll know:

  • Why the value on the date of death, not the sale price, drives your tax picture
  • How an appraiser reconstructs value for a date that has already passed
  • What to hand your CPA so the number holds up if anyone asks

Why an Appraisal for Inherited Property Comes First

When you inherit real estate, the tax code does something generous. It resets your cost basis. Under the IRS rules on basis of inherited property, your starting point is the fair market value on the date the owner died. Not what they paid in 1978. Not the assessor’s number. The market value on that one day.

Say the house was worth $650,000 when your mother died. You sell it six months later for $655,000. Your taxable gain is roughly $5,000, less selling costs. Without a defensible date-of-death value, you have no clean way to prove that. And the burden of proof sits with you, not the IRS.

That is why the appraisal comes first. Before the listing agreement. Before a sibling buyout. Before the return gets filed. An appraisal for inherited property is not paperwork for its own sake. It is the document that every later decision leans on. We prepare these as part of our estate planning appraisal work across Cook County every month. The families who order early spend far less time arguing later.

What a Date-of-Death Appraisal Actually Establishes

The appraisal fixes one number: market value as of the date of death. That number does a lot of work at once.

For income tax, it becomes the basis your CPA uses when the property is eventually sold. In a rising market, the reset usually wipes out decades of appreciation. In a falling market, the basis can step down instead of up, which is worth knowing before you plan around a loss.

For estate tax, the same value goes on the return if one is required. Federal estate tax reaches only very large estates, well above what most families own. Illinois is a different story. The Illinois Attorney General’s estate tax fact sheet sets the state exclusion amount at $4,000,000. It works as a threshold rather than a credit. A North Shore home, a retirement account, and a life insurance policy can cross that line faster than people expect. If they do, Form 700 is due nine months after death, and the state wants the appraisals attached.

There is one wrinkle. Under the IRS instructions for Form 706, an executor who files that return can elect alternate valuation. That values estate property as of six months after death instead. The election has to lower both the gross estate and the tax. It also applies to everything in the estate, not just the house. If your CPA is weighing that election, the appraiser needs to know, because it changes the effective date of the whole assignment.

How a Retrospective Appraisal Works When Months Have Passed

Most families call us after the fact. The death was in March, the probate case opened in June, and the CPA asked for a value in September. That is normal, and it is exactly what a retrospective appraisal is for.

A retrospective appraisal has an effective date in the past. The appraiser inspects the property today, then values it as it stood on the date of death. Only the market evidence a buyer could have seen at that time comes into play. Sales that closed after the effective date do not drive the value opinion. Under the standards published by The Appraisal Foundation, the appraiser has to state that effective date clearly and hold the analysis to it. That discipline matters, because the appraiser already knows what the market did afterward.

Condition matters too. If the kitchen was gutted after the funeral, the appraisal has to describe the kitchen that existed on the date of death. Old photos, the listing from a prior sale, permits, and family accounts all help. The more a property has changed since the death, the more this documentation earns its keep.

In practice, a retrospective assignment costs about the same as a current one. The difference is the research. A year-old effective date in a fast-moving Chicago submarket takes real care, so ask any appraiser you interview how they handle the data cutoff.

Where the Date-of-Death Number Gets Tested

The value gets tested in three places, and each one has a different audience.

The first is the sale. When you list, the appraisal tells you whether the agent’s price is realistic and what the gain will look like at closing. A pre-listing opinion of value also gives you cover if a buyer’s lender appraises low and you need to hold your ground.

The second is the split. When one sibling keeps the house and buys out the others, the buyout price should start from an independent number. Not the assessor’s figure, and not a Zestimate. We have watched families lose a year and a relationship over a $40,000 gap that a single report would have settled. Our residential appraisal team handles these buyout assignments with both sides named as intended users.

The third is the courthouse. If the estate goes through the Probate Division of the Circuit Court of Cook County at the Daley Center, the inventory will show a value for the real estate. A USPAP-compliant report backs that figure in a way an online estimate cannot. Whether a particular estate needs probate at all is a question for the family’s attorney, not the appraiser.

For the CPA: What to Ask For Before the Return Is Filed

Accountants call us about inherited property more than any other professional group. The same problems come up every time. So here is what to specify when you or your client orders the report.

First, put the effective date in the engagement. State the date of death, or the alternate valuation date if the executor is electing it on Form 706. An appraisal dated to the inspection is the wrong answer.

Second, name the intended use. Ask for a report prepared for tax basis and estate reporting purposes. That scope tells the appraiser to document market conditions as of the effective date, describe the property’s condition at that time, and explain the data cutoff. A lending form will not do that.

Third, check consistency. If the estate files Form 706, the value reported there controls the heir’s basis. The executor may also have to issue Schedule A of Form 8971 to the beneficiaries. The IRS FAQ linked above notes that a penalty can apply when a beneficiary claims a basis above the estate tax value. One appraisal, used on both the estate return and the heir’s eventual Schedule D, avoids that mismatch.

Finally, keep the report in the permanent file. The property may not sell for a decade. When it does, the basis question comes right back, and the report is the answer. Our earlier piece on qualified appraisals for donated real estate covers the related IRS rules if the heir plans to donate the property instead.

Order the Appraisal Before the Listing Agreement or the Return

Sequence is everything here. Get the date-of-death value first. Then price the listing, negotiate the buyout, or file the return with a number behind it. Families who reverse that order end up backing into a value after the sale. That is harder to defend and more expensive to fix.

Our lane is the value and the report. How the basis is claimed, whether alternate valuation makes sense, and what the return should say are properly the CPA’s work. When both sides do their part early, the number that reaches the IRS is one that holds.

Inherited a Home and Not Sure What It Was Worth?

PahRoo prepares date-of-death and retrospective appraisals that give heirs, executors, and their CPAs one defensible number to build on.

Request an Estate Appraisal

Frequently Asked Questions

Do you need an appraisal for an inherited house?

In most cases, yes. Your tax basis in inherited real estate is its fair market value on the date of death. An independent appraisal is the standard way to document that value. It also settles the number for sibling buyouts, probate inventories, and any state estate tax return.

What is a date-of-death appraisal?

It is an appraisal with an effective date equal to the day the owner died. The appraiser values the property as it stood on that date using market evidence available at the time. The inspection and report can happen months later.

How do you determine the value of an inherited property?

A licensed appraiser inspects the property and reconstructs its condition as of the date of death. Then the appraiser analyzes comparable sales that closed around that date. The report explains the data cutoff and states a market value opinion tied to that effective date.

What is a stepped-up basis?

It is the reset of an inherited asset’s cost basis to its fair market value at the date of death. If the property has appreciated, the heir’s basis steps up, which reduces the taxable gain on a later sale. If the value fell, the basis can step down instead.

Can I get an appraisal months after the death?

Yes. This is called a retrospective appraisal. The appraiser sets the effective date to the date of death. The analysis then uses only information a buyer could have known at that time. It is routine work for appraisers who handle estate assignments.

Estate Valuation Support Across Cook County

PahRoo Appraisal & Consultancy prepares date-of-death, retrospective, and buyout appraisals for heirs, executors, attorneys, and CPAs. We serve Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Every report is developed to USPAP and written so a reviewer can follow the effective date and the evidence behind it. See our full range of real estate appraisal services, or contact our team before the listing agreement or the return goes out.

Calendar open to January 1 beside a house key, the effective date for a retrospective appraisal tax appeal
January 1 Is the Only Date That Matters in a Tax Appeal

A Cook County appeal can be argued in October, decided in December, and appealed to the state the following spring. None of those dates matter to the value. Illinois assesses property as of January 1. So a retrospective appraisal tax appeal has one effective date, fixed by statute, whether the hearing lands eight months later or eighteen. The most common way a strong appeal loses is not a bad comparable. In practice, it is an appraisal dated the wrong day.

By the end of this article, you’ll know:

  • Where the January 1 date comes from and what the Board of Review and PTAB do with it
  • How an appraiser rebuilds a January 1 value from evidence that arrives months later
  • Why a refinance or purchase appraisal with the wrong date can sink an otherwise good case

Where the January 1 Date Comes From

The rule is in the Property Tax Code. Under section 9-155, the assessor determines the value of each property “as of January 1 of that year.” So everything downstream inherits that date. The assessment is a fraction of fair cash value on January 1. The Board of Review decides whether that fraction is right on January 1. Then the Property Tax Appeal Board, if the case gets that far, rules on the same day’s value.

Cook County adds a wrinkle that makes the date carry more weight, not less. The county reassesses on a three-year cycle, township by township. We covered that cycle in our piece on the 2026 south suburbs reassessment. A value set as of January 1 in a reassessment year becomes the base for the next two years’ bills. So get that one date right and the benefit compounds. Get it wrong and so does the cost.

What a Retrospective Appraisal Tax Appeal Has to Prove

The PTAB’s own rules spell out what counts as proof of market value. Under 86 Ill. Adm. Code 1910.65, the Board will look at an appraisal of the subject “as of the assessment date at issue.” It will also look at a recent sale of the subject, at construction costs if the build date is close to the assessment date, or at three or more comparable sales with support for their similarity. Every one of those is anchored to the same January 1.

The same Part makes PTAB proceedings de novo. The Board considers only what is submitted to it, and gives no weight to what happened at the Board of Review. So an appraisal that carried the day at the county level has to be filed again at the state level. And an appraisal never dated to January 1 does not improve by being resubmitted. Our article on Board of Review evidence rules covers the county-level requirements in detail.

Also, the word “retrospective” describes the work, not the report type. By the time an appeal is heard, January 1 is in the past. The appraiser has to establish what a buyer and seller would have agreed to on that date, using only what was knowable then. That is a different discipline from a current-value appraisal. It shows most in the comparable selection.

Rebuilding January 1 From Evidence That Arrives Later

Consider a hypothetical Northbrook house reassessed for 2026. The appeal is filed in the fall, so the hearing sits well past the date. By then the appraiser can see sales from November 2025, February 2026, and June 2026. The November and February sales bracket the date and need only a small market conditions adjustment to land on January 1. The June sale is a different matter. If the market moved between January and June, the adjustment has to run backward to the effective date. The report should say how the appraiser measured that movement.

Physical condition follows the same logic, too. A roof that failed in March does not lower the January 1 value. A basement that flooded in December 2025 does. Permits, listing photos, inspection reports, and the property record card all help establish what the house looked like on the first of the year. In Cook County the record card also shows the characteristics the assessor used. So errors in living area, age, or condition rating are among the cleanest grounds for a change. They go to the assessor’s own inputs on the assessor’s own date.

Sales of the subject, meanwhile, deserve their own note. A closing near January 1 is powerful evidence, and both the PTAB rules and most county boards treat it that way. A closing well after the date is still useful, but it has to be adjusted back. The further it sits from January 1, the more the argument depends on the adjustment rather than the price.

The Refinance Appraisal Problem

Tax consultants running volume appeals see this one constantly. An owner refinanced in May, has a lender’s appraisal in hand, and wants to use it. The report is competent, of course. It is also dated May, prepared for a lender, with an intended use of mortgage lending. Submitted as-is, it invites the obvious objection. This is not a January 1 value, and it was not prepared for this purpose.

The fix is not to throw the report away. Instead, ask the appraiser, or a new one, for a retrospective value as of January 1 with the appeal as the stated intended use. Then the lender’s report becomes source material for condition and characteristics. The new report supplies the date and the purpose. For a consultant managing dozens of parcels, check the effective date and intended use on every appraisal before filing. That two-minute step will save more cases than any other.

Other States, Same Date

January 1 is not an Illinois quirk. Florida assesses as of January 1 as well, and its Value Adjustment Board petitions turn on that date the same way. Texas uses January 1 for most property as well. The mechanics of the appeal differ from state to state. But the appraiser’s task is the same everywhere PahRoo works: find the value on the lien date, not the hearing date.

The divorce lane has its own version of this problem, where the date is chosen rather than fixed. We covered that in our article on the date of value in a divorce appraisal. The tax version is simpler in one way and harder in another. Simpler, because nobody argues about which date applies. Harder, because evidence keeps arriving after the date has passed, and the appraiser has to keep it out.

Check the Date Before You Check the Number

Before an appraisal goes into an appeal file, confirm three things on its first page. The effective date is January 1 of the assessment year at issue. The intended use names the assessment appeal, not a loan. And the comparable sales either bracket the date or carry a stated market conditions adjustment back to it. If any of the three is missing, then the number on the cover is answering a question the Board did not ask. So fix the date first. The value follows.

Is Your Client’s Appraisal Dated January 1?

PahRoo prepares retrospective appraisals as of the assessment date for Board of Review and PTAB appeals, with the intended use and adjustments the rules expect.

Value It as of January 1

Frequently Asked Questions

What date does an Illinois property tax appraisal have to use?

January 1 of the assessment year at issue. Section 9-155 of the Property Tax Code sets the assessor’s valuation date at January 1, and the PTAB rules describe acceptable proof of value as an appraisal “as of the assessment date at issue.” An appraisal dated any other day is answering a different question.

Can I use a refinance appraisal for a tax appeal?

Usually not as-is. A lender’s appraisal carries the lender’s effective date and an intended use of mortgage lending. It can be useful source material for condition and characteristics, but the appeal needs a report with a January 1 effective date and the assessment appeal named as the intended use.

What is a retrospective appraisal?

An appraisal with an effective date in the past. The appraiser estimates value as of that earlier date using only information a market participant could have known at the time, and adjusts later evidence back to the date. Every tax appeal appraisal is retrospective, because January 1 has passed by the time the appeal is heard.

Do sales after January 1 count in a tax appeal?

They can, with care. A sale shortly after the date is often the best evidence available, and it can be adjusted back to January 1 for any market movement in between. The further a sale sits from the date, the more the argument depends on the adjustment rather than the price, and the report should show how the adjustment was measured.

Does the PTAB accept the appraisal I filed with the Board of Review?

Only if you file it again. PTAB proceedings are de novo under 86 Ill. Adm. Code 1910.50, which means the Board considers only the evidence submitted to it and gives no weight to what the county board decided. The appraisal must be part of the PTAB record on its own.

January 1 Valuations for Illinois Appeals

Property tax attorneys and consultants across Cook County and the collar counties rely on PahRoo Appraisal & Consultancy for retrospective appraisals dated to the assessment year. Our MAI and SRA designated team prepares reports for Board of Review and PTAB filings as part of our appraisal services, and our property tax appeal FAQs cover what clients ask first. To discuss a parcel or a portfolio, contact our team.

NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712