Author: Michael Hobbs

Request a quote

Our blog

Latest news
& events

Commercial real estate appraiser in Chicago analyzing Highest and Best Use for property appraisal.
Commercial Real Estate Appraiser Chicago: Highest & Best Use

When hiring a commercial real estate appraiser in Chicago, one of the most important factors affecting value is a property’s Highest and Best Use.

Many property owners assume that a Highest and Best Use analysis automatically increases value. In reality, market evidence often tells a different story. In some cases, a property’s Highest and Best Use can actually support a lower value conclusion, particularly when market conditions, redevelopment potential, or economic feasibility do not align with expectations.

For property owners, attorneys, accountants, bankers, and brokers, understanding how Highest and Best Use influences an appraisal can be critical during tax appeals, estate settlements, litigation matters, financing decisions, and investment planning.

A qualified commercial real estate appraiser in Chicago evaluates not only what a property could become, but what informed buyers would realistically pay for it in today’s market. That distinction can have a significant impact on value.

What Is Highest and Best Use in Commercial Real Estate?

Highest and Best Use is one of the fundamental principles of real estate appraisal. It represents the reasonably probable use of a property that is:

      • Legally permissible
        • Physically possible
      • Financially feasible
      • Maximally productive

A commercial real estate appraiser in Chicago must analyze all four criteria before determining a property’s Highest and Best Use.

Importantly, Highest and Best Use is not based on speculation. It must be supported by market evidence, economic realities, and buyer behavior. Just because a property could be developed differently does not mean that alternative use creates additional value.

How a Commercial Real Estate Appraiser in Chicago Determines Highest and Best Use

Every commercial property is unique. A professional appraisal examines numerous factors that influence value, including:

      1. Current zoning regulations
      2. Market demand
      3. Location characteristics
      4. Existing improvements
      5. Development costs
      6. Financing conditions
      7. Neighborhood trends

For example, a property owner may believe a vacant parcel is worth more because it could accommodate a larger development. However, if market demand does not support that development, the proposed use may not be financially feasible.

In these situations, the property’s current use may remain its Highest and Best Use.

This analysis helps ensure that value conclusions reflect market realities rather than theoretical possibilities.

Why Development Potential Does Not Always Increase Value

One of the most common misconceptions in commercial real estate is that development potential automatically increases value.

While a property may have favorable zoning, buyers ultimately determine value based on what they can realistically achieve and profit from.

Several factors can limit redevelopment potential:

      1. Rising construction costs
      2. Higher interest rates
      3. Weak tenant demand
      4. Lengthy entitlement processes
      5. Environmental concerns
      6. Utility limitations

A commercial property appraiser in Chicago must consider these factors when evaluating whether redevelopment is financially feasible.

If redevelopment is not economically justified, buyers may not pay a premium for future potential. As a result, the property’s value may be lower than expected.

How Chicago Market Conditions Affect Highest and Best Use

Commercial real estate markets are constantly evolving.

In Chicago, market conditions can vary significantly by property type, neighborhood, and economic cycle. Office, industrial, retail, and mixed-use properties may all experience different demand patterns.

For example:

      • An office building may face elevated vacancy rates.
      • A retail property may struggle with changing consumer habits.
      • An industrial facility may benefit from increased logistics demand.
      • A mixed-use project may face financing challenges.

Because market conditions directly influence financial feasibility, they also influence Highest and Best Use conclusions.

A commercial real estate appraiser in Chicago analyzes local market data to determine whether an alternative use reflects current buyer behavior and investment trends.

Why Highest and Best Use Matters in Property Tax Appeals

Highest and Best Use frequently becomes a key issue during property tax appeals.

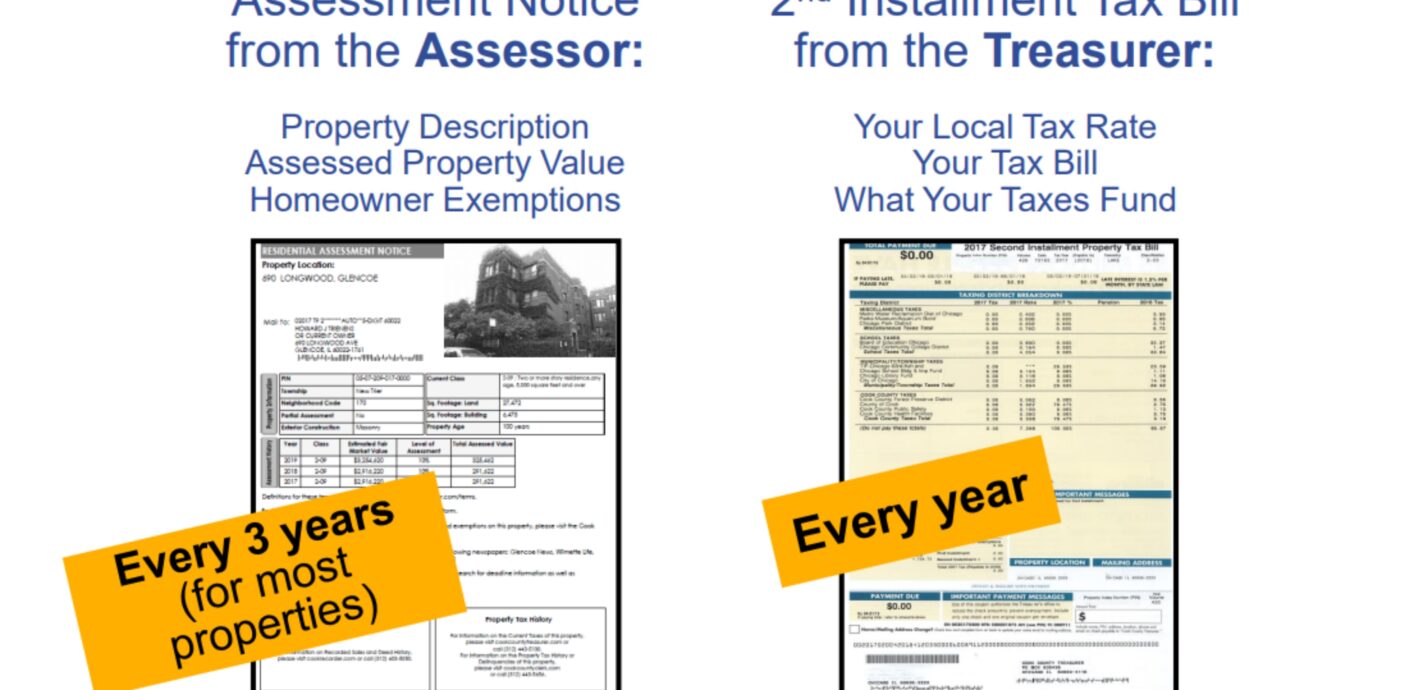
Assessments are sometimes based on assumptions regarding redevelopment potential or future use. Property owners can review assessment information through the Cook County Assessor’s Office. However, if those assumptions are not supported by market evidence, the resulting assessment may exceed market value.

An independent appraisal can help answer critical questions:

      • Would a typical buyer pursue the assessor’s assumed use?
      • Is redevelopment financially feasible?
      • Does current market demand support the alternative use?
      • Are there legal or physical limitations affecting the property?

When market evidence indicates that a less intensive use is more realistic, the resulting appraisal may support a lower assessed value.

For many property owners, this analysis becomes one of the most persuasive components of a successful tax appeal.

When Commercial Property Owners Should Obtain an Independent Appraisal

There are several situations where an independent appraisal can provide valuable insight and support.

Property Tax Appeals

A professionally prepared appraisal can provide objective market evidence when challenging an assessment.

Estate and Trust Administration

Accurate appraisal reports help establish credible market value for estate planning, wealth transfer, and settlement purposes.

Litigation Support

Attorneys frequently rely on appraisal reports to support commercial real estate disputes and expert testimony.

Financing and Refinancing

Lenders require reliable market value conclusions when evaluating collateral and underwriting risk.

Investment Decision-Making

Investors use appraisals to better understand opportunities, risks, and market positioning before making capital commitments.

In each of these situations, a thorough Highest and Best Use analysis helps ensure that value conclusions reflect actual market conditions.

Working with a Commercial Real Estate Appraiser in Chicago

Choosing the right appraiser can make a significant difference in the credibility and reliability of the final analysis. Many commercial real estate professionals pursue education and professional development through organizations such as the Appraisal Institute.

An experienced commercial real estate appraiser in Chicago understands local market conditions, zoning considerations, development trends, and appraisal methodologies that influence commercial property value.

More importantly, an independent appraisal provides objective market evidence that can withstand scrutiny from lenders, attorneys, taxing authorities, investors, and other stakeholders.

Whether you are pursuing a property tax appeal, planning an estate, resolving litigation, refinancing a property, or evaluating an investment opportunity, understanding a property’s Highest and Best Use is often one of the most important steps in determining market value.

FAQ: Does Highest and Best Use always increase property value?

Answer: No. A property's Highest and Best Use does not automatically result in a higher value. 
While redevelopment potential may create additional value in some situations, market conditions, development costs, 
financing availability, zoning restrictions, and buyer demand all influence whether an alternative use is financially 
feasible. In many cases, a commercial real estate appraiser in Chicago may determine that the current use represents 
the property's Highest and Best Use, resulting in a lower value than anticipated.
Final Thoughts

Highest and Best Use does not automatically increase property value. In many cases, a thorough analysis reveals that market realities, financial feasibility, or physical limitations reduce the likelihood of alternative development scenarios.

By focusing on what informed buyers would realistically pay in today’s market, a commercial real estate appraiser in Chicago can provide a well-supported opinion of value that reflects actual market conditions rather than speculation.

For property owners, attorneys, accountants, bankers, and brokers, that distinction can have a meaningful impact on financial decisions, tax appeals, estate administration, litigation outcomes, and long-term investment strategies.

Need a Commercial Real Estate Appraisal in Chicago?

Whether you are preparing for a property tax appeal, estate settlement, financing transaction, litigation matter, or investment decision, obtaining an independent appraisal can provide the objective market evidence needed to move forward with confidence.
Chicago housing market analysis showing Cook, DuPage, Lake and Will County trends
Chicago Housing Market: Tight Inventory, Uneven Demand

Chicago Housing Market Analysis: Tight Inventory Masks Emerging Market Divergence

The Chicago housing market remains firmly in seller-market territory heading into June 2026, but the underlying story is becoming more complex. While inventory levels remain historically tight across Cook, DuPage, Lake, and Will Counties, demand is no longer moving uniformly across the region.

PahRoo Appraisal & Consultancy’s Week 22 Market Intelligence Report reveals a market increasingly shaped by mortgage-rate pressures, county-level demand shifts, and significant differences between single-family and condominium performance. For lenders, attorneys, accountants, brokers, and investors, understanding these distinctions may be more important than ever.

Inventory Remains Tight Across the Chicago MSA

At first glance, the market appears exceptionally strong. Months of supply remain below 1.2 months across all major residential submarkets, a level traditionally associated with a strong seller’s market.

However, that tightness comes with an important caveat.

Much of the current inventory scarcity is being amplified by reduced listing activity. New listings declined across every county during the Memorial Day holiday week, creating artificially compressed inventory metrics. While year-over-year inventory contraction remains real, current supply figures may overstate market strength.

For appraisal assignments, lending decisions, and acquisition strategies, this distinction matters. Inventory scarcity alone does not guarantee accelerating demand.

Mortgage Rates Are Becoming a Larger Market Driver

One of the most significant developments this week is the widening disconnect between Federal Reserve policy and mortgage borrowing costs.

The effective federal funds rate remained unchanged at 3.62%, yet the average 30-year fixed mortgage rate increased to 6.53%.

This pushed the mortgage spread to approximately 291 basis points above the effective federal funds rate, significantly wider than the historical range of 150–170 basis points. According to the Mortgage Bankers Association, mortgage-rate movements continue to influence affordability, financing costs, and housing market activity nationwide.

The result is a housing market where policy easing is no longer fully reaching borrowers.

For buyers operating near affordability thresholds, even modest increases in financing costs can impact purchasing decisions. As mortgage rates rise, the demand recovery observed earlier this spring appears increasingly vulnerable.

Q: How do mortgage rates affect home values?
A: Mortgage rates influence affordability and buyer demand, which can impact pricing 
trends and market activity over time.
Single-Family Housing Demand Is Splitting by County

Perhaps the most important trend emerging in Week 22 is the growing divergence among single-family housing markets.

Only two weeks ago, all four major county markets were showing positive year-over-year pending sales growth. Today, the picture is mixed:

  • DuPage County pending sales increased 19.4% year-over-year.
  • Will County pending sales increased 24.5%.
  • Cook County pending sales declined 5.7%.
  • Lake County pending sales declined 14.2%.

This shift raises an important question.

Are buyers reacting to higher mortgage rates, or is the decline simply the result of Memorial Day-related transaction disruptions?

The answer remains unclear. Market participants should monitor Weeks 23 and 24 closely before concluding that a broader demand slowdown has begun.

DuPage County Emerges as the Strongest Market

Among all Chicago-area counties analyzed, DuPage County continues to demonstrate the healthiest market fundamentals.

Single-family pending sales increased nearly 20% year-over-year, while condominium demand rose more than 25%.

Inventory remains exceptionally tight, and pricing continues to show resilience. Unlike several neighboring markets, DuPage benefits from broad-based demand growth across both housing segments.

For lenders, investors, and real estate professionals seeking stability, DuPage currently presents the strongest combination of demand, supply discipline, and pricing support.

Cook County’s Housing Market Is Cooling

Cook County remains the dominant force within the Chicago MSA, accounting for approximately 61% of active single-family inventory and 77% of active condominium inventory.

Because of its size, county-level trends often influence perceptions of the entire metropolitan market.

Yet Cook’s single-family market is showing signs of moderation.

Earlier this spring, buyers were regularly paying significantly above asking price. The median absorbed-to-list premium has now narrowed substantially, falling from approximately $44,300 two weeks ago to roughly $19,100 today.

This does not signal weakness.

Instead, it suggests that bidding competition is becoming less aggressive and that buyers may be gaining slightly more negotiating leverage than they had earlier in the year.

Will County Condominiums Show the Clearest Signs of Stress

While most Chicago-area housing segments remain stable, one submarket stands apart.

Will County condominiums continue to display the strongest indicators of market softening.

Inventory has increased 26% year-over-year while pending sales have fallen 22%. At the same time, nearly 28% of listings have undergone price reductions, and median absorbed prices have declined 5.8%.

Taken together, these indicators point toward a genuine supply-demand imbalance rather than temporary market noise.

For buyers, this environment may create attractive negotiating opportunities.

For lenders and appraisal professionals, however, the segment warrants additional caution and careful market support when developing value conclusions.

Q: Is Chicago still a seller's market?
A: Yes. Most Chicago-area submarkets continue to have low inventory levels, although demand varies by 
county and housing type.
What This Means for Real Estate Decision-Makers

The Week 22 data highlights the growing importance of submarket-level analysis.

The Chicago housing market cannot be accurately understood through metro-wide averages alone. Strong demand in DuPage and Will County single-family markets coexists with emerging weakness in Lake County and ongoing softness in Will County condominiums.

For attorneys handling estate, divorce, or litigation matters, market-specific Chicago real estate appraisal services become increasingly important when market conditions vary significantly between counties.

For lenders, widening mortgage spreads and shifting demand patterns may affect collateral risk.

For investors, opportunities remain available, but they are becoming more localized and selective.

Looking Ahead

The most important question entering June is whether recent single-family demand softness in Cook and Lake Counties represents a temporary holiday-week distortion or the beginning of a broader affordability-driven slowdown.

  • If mortgage rates continue rising, housing demand could weaken further across rate-sensitive segments.
  • If rates stabilize or retreat, the demand recovery observed earlier this spring may resume.

For now, the data supports a measured conclusion: inventory remains tight, but demand is no longer moving in one direction across the Chicago metropolitan area.

Successful decision-making will depend on understanding where strength is persisting, where weakness is emerging, and when professional Chicago real estate appraisal services can help support informed decisions.

Make More Informed Real Estate Decisions

Real estate decisions are only as strong as the market data behind them. Whether you’re navigating an estate settlement, divorce, litigation matter, lending decision, investment acquisition, or portfolio review, understanding how local market conditions affect value is critical.

The Chicago housing market is becoming increasingly segmented, with meaningful differences emerging between counties, neighborhoods, and property types. Relying on broad market headlines can lead to costly assumptions.

A certified appraiser can provide the independent market analysis and credible appraisal support needed to make informed decisions with confidence.

etrospective market value appraisal analysis for tax attorneys
Retrospective vs Current Market Value: When Tax Attorneys Need Each

Retrospective vs Current Market Value Appraisal

For tax attorneys handling disputes, estate matters, IRS issues, or litigation support, choosing the correct type of appraisal can directly impact case strategy and credibility. One of the most important distinctions is understanding the difference between a retrospective appraisal and a current market value appraisal.

Although both opinions of value rely on professional appraisal methodology, they serve very different legal and financial purposes. Using the wrong appraisal date can weaken a claim, create challenges during negotiations, or expose a client to unnecessary scrutiny.

Understanding when each appraisal applies helps attorneys protect clients, support defensible positions, and avoid costly valuation disputes.

What Is a Current Market Value Appraisal?

A current market value appraisal determines the value of a property as of today’s effective date. This type of appraisal reflects current market conditions, recent comparable sales, local economic influences, and active buyer behavior.

Tax attorneys commonly need a current market value appraisal when:

      • Negotiating property tax disputes
      • Supporting present-day litigation
      • Reviewing collateral or lending matters
      • Advising clients on asset disposition
      • Establishing value for current negotiations

A current appraisal provides insight into how the market views a property right now. Because market conditions shift over time, today’s value may differ substantially from a prior period.

For attorneys managing active tax matters, this appraisal can help establish a realistic and supportable benchmark for negotiations or legal positioning.

What Is a Retrospective Appraisal?

A retrospective appraisal determines a property’s value as of a past effective date. Instead of analyzing current market conditions, the appraiser reconstructs historical market data, comparable sales, economic conditions, and property characteristics relevant to that specific point in time.

Tax attorneys often require retrospective appraisals for:

      1. Estate and probate matters
      2. IRS disputes
      3. Gift tax reporting
      4. Historical tax appeals
      5. Partnership dissolution cases
      6. Trust litigation
      7. Bankruptcy proceedings
      8. Date-of-death appraisals

The appraisal process involves researching historical records and market evidence to form a credible opinion of value that reflects what market participants would reasonably have considered on the effective date.

This distinction matters because courts, taxing authorities, and the IRS typically require valuation opinions tied to a legally relevant historical date.

Why the Effective Date Matters in Tax Litigation

In appraisal work, the effective date is not simply administrative. It is central to the assignment’s credibility and legal relevance.

A retrospective appraisal answers:

“What was the property worth on a specific date in the past?”

A current market value appraisal answers:

“What is the property worth today?”

Using a current appraisal for a historical tax issue may fail to address the legal standard required in the dispute. Likewise, relying on a retrospective appraisal in a present-day negotiation may not reflect current market realities.

For tax attorneys, aligning the appraisal date with the legal issue strengthens defensibility and reduces unnecessary challenges from opposing parties or taxing authorities.

Common Scenarios Where Tax Attorneys Need Retrospective Appraisals

Estate Tax and Date-of-Death Appraisals

Federal estate tax matters often require a retrospective appraisal tied to the decedent’s date of death. The IRS Estate Tax Guidance outlines reporting expectations for estate-related filings, making credible appraisal support especially important for complex or high-value real estate holdings.

An unsupported value opinion can trigger audits, disputes, or penalties.

Historical Property Tax Appeals

Some jurisdictions allow retroactive appeals or correction cases involving prior assessment years. In these situations, attorneys may need historical market evidence tied to the disputed assessment date.

Litigation and Partnership Disputes

When ownership disputes involve prior transactions or historical ownership interests, the valuation date frequently predates the litigation itself.

A retrospective appraisal helps establish a defensible historical benchmark that supports legal arguments and settlement discussions.

When Current Market Value Appraisals Are More Appropriate

Current market value appraisals are often necessary when attorneys need insight into present-day conditions affecting negotiations, asset decisions, or ongoing disputes.

Examples include:

      • Current property tax negotiations, especially when supporting a Chicago commercial property tax appeal with defensible appraisal evidence.
      • Active litigation involving present damages
      • Financing and collateral reviews
      • Current portfolio analysis
      • Pre-settlement negotiations

Because market conditions can change rapidly, relying on outdated data may create inaccurate conclusions or weaken strategic decisions.

Why Tax Attorneys Benefit From Specialized Appraisal Support

Retrospective assignments often require significantly more research than standard current appraisals. Historical market reconstruction, archived comparable sales data, and legal scrutiny increase both complexity and importance.

Tax attorneys benefit from working with appraisal professionals who understand:

      • Litigation support requirements
      • IRS and court expectations
      • Historical market analysis
      • Defensible reporting standards
      • Complex real estate asset analysis

An appraisal is not simply a number. In tax disputes, it can become a foundational piece of evidence influencing negotiations, settlements, and courtroom outcomes.

Choosing the Right Appraisal Can Reduce Risk

Selecting the correct appraisal type early in the process helps avoid delays, unsupported claims, and unnecessary challenges later.

Whether a matter requires a retrospective appraisal or a current market value appraisal depends on the legal issue, governing tax rules, and relevant valuation date.

For tax attorneys, aligning the appraisal assignment with the legal objective creates stronger documentation, more credible support, and better strategic positioning for clients.

If you are handling a tax dispute, estate matter, or historical valuation issue, obtaining the correct appraisal type can make a substantial difference in case preparation and defensibility.

Chicago residential appraisal market trends Week 18 across Cook, DuPage, Lake, and Will Counties
Chicago Residential Appraisal Market Trends: Week 18 Analysis
Chicago Housing Markets Are Moving in Different Directions

Chicago residential appraisal market trends for Week 18 show a clear split across the metro area. Cook and DuPage Counties are still showing strong seller-market momentum. Lake and Will Counties are showing more caution, with softer demand and rising supply pressure.

That matters for attorneys, lenders, accountants, brokers, and investors. A broad “Chicago market” view can miss what is really happening at the county level. Accurate real estate appraisals now need local market context, not general assumptions.

Cook County Remains the Strongest Seller Market

Cook County continues to lead the Chicago metro area in demand and pricing strength.

Single-family pending sales increased 10.2% from the prior week and 11.1% from last year. Active inventory fell 12.1% year-over-year, creating one of the tightest supply environments in the region.

Cook County also posted an absorbed-to-list ratio of 1.09x. In plain terms, many well-positioned homes are selling above asking price.

For professionals involved in lending, estate planning, divorce, property tax appeals, or pre-listing strategy, this kind of market requires careful appraisal support. Strong demand can move quickly, and pricing decisions need to be backed by current local data.

Cook County condos and townhomes also performed well. Pending sales rose 21.2% year-over-year while active inventory dropped 14.1%, showing continued buyer interest across multiple residential property types.

DuPage County Shows Strong Demand With Pricing Disconnects

DuPage County had some of the strongest demand growth in the Chicago area during Week 18.

Single-family pending sales rose 32.7% year-over-year. The absorption rate increased 39.1%, and months of supply tightened to 1.24 months. Those numbers point to a strong seller-market environment.

Still, one issue deserves attention.

DuPage reported an absorbed-to-list ratio of 0.76x. That means closed sales were much lower than current listing prices. This does not automatically mean the market is weakening. More likely, it shows a gap between higher-priced active listings and the mid-market homes that are actually closing.

For brokers, lenders, and attorneys, this is where appraisal judgment matters. Active listings alone may not tell the full story. Comparable sales, property class, buyer activity, and price range all need to be reviewed carefully.

DuPage condos also showed a sharp increase in absorbed prices during Week 18. Because condo transaction volume can be thinner, that jump may reflect the mix of properties that sold rather than a broad pricing shift.

Lake County Presents Mixed Market Signals

Lake County is currently one of the harder Chicago-area markets to read.

Several demand indicators weakened during Week 18. Pending sales declined 12.8% from the prior week. Inventory increased. Price reductions rose. Homes also took longer to sell.

At the same time, median absorbed prices moved sharply higher, rising 13.9% from the prior week and 21.3% from last year.

Those two signals do not line up neatly.

The likely explanation is that fewer homes sold overall, but the homes that did sell were concentrated in higher price ranges. That can lift the median absorbed price without proving that the entire market is gaining strength.

This matters in appraisal work. For estate matters, litigation, financing, portfolio reviews, and investment decisions, relying only on headline price growth can create risk. Lake County needs a closer look at the actual sales behind the numbers.

Will County Faces Growing Supply Pressure

Will County is showing the clearest signs of a shift toward buyers.

Active inventory increased 20.0% year-over-year. New listings rose 42.5% year-over-year. The pending-to-new listings ratio fell below parity at 0.90x, and months of supply increased 17.2%.

Unlike Cook and DuPage, Will County is seeing much more supply come onto the market. Demand has not kept up at the same pace.

That can lead to:

      • More buyer leverage
      • More seller concessions
      • Greater pricing pressure
      • Slower absorption
      • More competition among listings

Will County condos are also showing stress. The condo market posted the lowest absorbed-to-list ratio among the counties at 0.84x, which points to larger gaps between asking prices and completed sale prices.

For lenders and investors, this is a market where appraisal accuracy is especially important. Rising supply can affect collateral risk, pricing expectations, and timing decisions.

Mortgage Rates Still Matter

National housing affordability and inventory conditions continue influencing local Chicago-area buyer behavior.

The average 30-year fixed mortgage rate rose slightly to 6.30% during Week 18, according to housing finance data and broader Federal Reserve rate trends. The increase was small, but affordability pressure still affects each county differently.

Cook County remains more affordable compared with higher-priced areas, which helps support buyer activity. Lake and DuPage Counties have higher median absorbed prices, so buyers there may be more sensitive to rate changes.

These affordability differences help explain why county-level trends are starting to move apart.

Why County-Level Appraisals Matter More in 2026

The main takeaway from Week 18 is simple: Chicago is not moving as one market.

Conditions now vary by county in meaningful ways. Demand, inventory, pricing, seller leverage, buyer leverage, and market speed are all changing at different rates.

For attorneys, accountants, lenders, brokers, and investors, this creates real risk if decisions are based only on broad metro data.

A reliable appraisal should reflect the specific market, property type, price range, and current transaction activity. That level of detail helps support stronger lending decisions, clearer litigation support, better pricing strategy, and more confident financial planning.

Chicago Housing Market Outlook for Q2 2026

Cook County remains the strongest seller-market environment in the Chicago region. Low inventory and steady buyer demand continue to support pricing.

DuPage County also shows strong demand, but pricing signals need careful review.

Lake County has mixed indicators, so deeper sales analysis is needed before drawing firm conclusions.

Will County carries the most supply-side risk right now. Inventory growth is outpacing demand, and that could create more pricing pressure if the trend continues.

The next few weeks will show whether these county-level differences widen or settle. For now, local real estate appraisal insight remains essential for anyone making high-stakes property decisions across the Chicago metro area.

cost segregation appraisal process showing property analysis, component breakdown, and IRS-compliant reporting
Cost Segregation Appraisal: Avoid Costly Mistakes

A cost segregation appraisal is only as valuable as the evidence behind it. Done well, it accelerates depreciation and improves cash flow on a commercial property. Done cheaply, it can unravel the moment the IRS, a lender, or a client’s attorney asks for support. For the professionals who rely on these studies, quality matters far more than the price on the invoice.

By the end of this article, you’ll know:

  • Why a bargain study can cost more than it saves
  • What the IRS looks for when it reviews a study
  • Where an independent appraiser fits into the process

What a Cost Segregation Appraisal Really Involves

Cost segregation is a tax strategy, not a valuation on its own. A study breaks a building into its components. Then it assigns each one to the right depreciation class, so the owner can recover cost faster. The IRS treats this as an engineering-based analysis. Its Cost Segregation Audit Techniques Guide spells out what a quality study should contain.

Here is where an appraiser earns a seat at the table. Before components can be classified, someone has to establish the property’s value. That means allocating the purchase price across land, building, and improvements. That allocation is a valuation question, and it is the foundation the rest of the study stands on. Get it wrong, and every number downstream inherits the error. Our commercial appraisal work often supports exactly this kind of foundation. The engineering and tax professionals then complete the study.

Why Defensibility Matters More Than Price

Two studies can look identical on paper. Both list components, assign useful lives, and project a depreciation benefit. The real test comes later, when someone challenges the numbers.

A defensible study answers three questions cleanly. Is the methodology documented and consistent with IRS guidance? Is each classification supported by real analysis rather than assumption? Can the conclusions survive an audit? Cheaper studies often cut corners in ways that stay invisible until an examiner starts reading closely. The IRS guide is blunt on this point. Preparer qualifications and documentation quality separate a study that holds from one that collapses.

What a Weak Study Can Cost You

When a study fails, the damage is financial and it lands on real people. An owner can face disallowed deductions, audit adjustments, amended returns, and penalties. The savings that looked so attractive get clawed back, often with interest.

The exposure is not limited to the taxpayer. For the attorney, accountant, or banker who recommended the work, a study that falls apart becomes a credibility problem. Protecting a client’s position and your own reputation is reason enough to care about how the study was built.

Red Flags in a Cost Segregation Study

You do not need to be an engineer to spot a questionable study. A few warning signs tend to show up together.

Watch for aggressive classifications with no supporting detail, thin documentation, and templates that treat every property the same. Be wary of pricing that seems disconnected from the scope of work. The IRS specifically flags contingency-fee arrangements and rule-of-thumb allocations, because both create pressure to overstate short-life property. When the report reads like it was built for speed, that is usually what you are getting.

How to Choose Work That Holds Up

Change the question you ask. Instead of who can do this cheapest, ask what protects the position if it is challenged. That reframe points you toward qualified preparers, thorough documentation, and a sound valuation underneath it all.

An independent appraisal is part of that protection. It grounds the study in a defensible opinion of value. The depreciation classifications then rest on solid footing rather than guesswork. When real money and professional reputations are on the line, that footing is worth paying for.

High-Stakes Property? Start With a Defensible Valuation.

PahRoo provides the independent commercial appraisal that a sound cost segregation study is built on. It rests on real analysis and thorough documentation. Talk to us before the numbers get tested.

Speak With Our Team

Frequently Asked Questions

What is a cost segregation appraisal?

It is the independent valuation work that supports a cost segregation study. The study reclassifies building components for faster depreciation. The appraisal establishes the underlying property value and cost allocation it relies on.

Who should perform a cost segregation study?

The IRS expects preparers with expertise in construction, engineering, and tax law. A quality study identifies its preparers and their credentials, which is one reason qualified professional involvement matters.

What makes a cost segregation study defensible to the IRS?

Clear methodology, detailed asset classification supported by analysis, and documentation tied to IRS guidance. The IRS Cost Segregation Audit Techniques Guide describes the elements of a quality study.

What are the risks of a low-quality study?

Disallowed depreciation deductions, IRS audit adjustments, amended returns, and penalties. For advisors who recommended the work, a failed study can also damage professional credibility.

How does an appraiser support cost segregation?

An appraiser provides the independent opinion of value and purchase price allocation that a study is built on. That valuation foundation helps the depreciation classifications rest on defensible ground.

Need a Defensible Commercial Valuation?

PahRoo Appraisal & Consultancy delivers independent, USPAP-compliant valuations for commercial and investment property, led by Michael Hobbs. A cost segregation study, a lender, or a legal matter can all depend on a credible number. Our commercial appraisal team provides that foundation. Explore our full range of appraisal services, or reach us through our contact page to talk through your situation.


Chicago single-family housing inventory trends and appraisal insight March 2026
Chicago Real Estate Appraisal Update: Second Week of March 2026

What the Chicago Housing Market Means for Attorneys, Accountants, Bankers, and Brokers

During the second week of March 2026, the Chicago metro housing market continued to show a familiar pattern: tight supply, stable pricing, and demand that remains sensitive to interest rates. For professionals who rely on real estate appraisal in litigation, lending, estate work, tax matters, and transaction support, this matters because even small market shifts can affect value conclusions and decision quality.

This is not a market where surface-level pricing trends tell the full story. You need appraisal analysis that explains how current supply, buyer behavior, and financing conditions influence property-specific outcomes.

Tight Inventory Continues to Shape Value

The Chicago metro remains a supply-constrained market. The report shows about 7,615 single-family homes and 3,956 condominiums on the market, for total inventory near 11,570 properties, which is roughly 2.3% below last year.

For you, that has direct appraisal implications.

When supply remains limited, comparable sale selection becomes more important. Fewer relevant comps can increase the significance of adjustment support, neighborhood context, and timing analysis. That is especially important when an appraisal must hold up in underwriting, dispute resolution, or advisory review.

In practical terms, a constrained market can create pricing resilience while also increasing interpretation risk. That means you benefit from an appraisal that does more than summarize data. You need one that explains what the data means.

Single-Family Housing Still Shows More Strength

Single-family housing remains the stronger segment in the Chicago metro area. In the report, the median list price for single-family homes reached $389,900, up 2.6% year over year, while the median absorbed price rose to $379,900, up 5.6% year over year. Months of supply remained low at 1.44 months.

That combination points to continued support for pricing, even though transaction activity is not accelerating aggressively.

For attorneys, lenders, and financial professionals, this matters because stronger pricing does not remove the need for caution. It increases the need for supportable conclusions. A rising market can still contain overpricing, weak comparables, and negotiation-driven price differences that need proper interpretation.

The Condo Segment Looks More Balanced

The condo segment shows a different pattern. Active inventory rose modestly year over year, and pricing gains were more restrained. The median condo list price was $329,999, while the median absorbed price was $304,950. Months of supply sat near 1.41 months, with more balanced supply-demand conditions than in the single-family segment.

This distinction matters because condo appraisal assignments should not be interpreted through the same lens as single-family properties. If you are advising on a condo-related matter, you may be dealing with different buyer behavior, different competitive pressures, and different pricing support.

That difference can materially affect appraisal conclusions, especially when the assignment is tied to litigation strategy, portfolio review, or transaction structuring.

Mortgage Rates Still Influence Market Behavior

Financing conditions remain one of the biggest variables affecting the market. The report notes a 30-year mortgage rate of approximately 6.11%, lower than last year but still elevated relative to the ultra-low-rate environment seen earlier in the decade.

For your decisions, that creates a higher-rate operating environment where demand can improve modestly without becoming fully loose or aggressive. Buyers may have more relief than they had a year ago, but affordability still limits movement.

That is important in appraisal work because financing conditions affect:

      • buyer pool depth
      • pricing sensitivity
      • time on market
      • negotiation behavior

In other words, rates do not just affect sales volume. They influence the market evidence used to support value.

Demand Is Holding, but It Is Not Immune to Risk

Pending activity suggests a market that is stable but not immune to disruption. Single-family pending sales were slightly below last year, and condo pending sales also showed softening year over year. At the same time, weekly movement reflected some seasonal spring activity.

That creates an important takeaway for professionals: this is a market where conditions can hold steady and still remain fragile.

For appraisal users, the risk is assuming stability means predictability. It does not. Interest-rate shifts, inflation pressures, and broader economic changes can affect value support faster than many stakeholders expect.

Price Reductions Still Matter

Even with constrained inventory, not every listing has pricing power. The report shows 25.2% of single-family listings had price reductions.

That matters because it shows a more nuanced market than headline price growth alone suggests. Sellers may still need to adjust expectations, and buyers remain selective. For you, that means appraisal analysis should separate broad market strength from individual asset performance.

A credible appraisal helps you understand whether a property is benefiting from real market support or simply entering the market with aspirational pricing.

Why This Matters for Appraisal Clients

In the second week of March 2026, the Chicago market continued to reflect a combination of:

      • limited supply
      • stable to modestly rising prices
      • interest-rate sensitivity
      • different conditions by property type

That matters to you because appraisal assignments in this environment require more than basic market commentary. They require defensible interpretation.

Whether you are handling litigation, advising a client, underwriting a loan, evaluating collateral risk, or planning for estate or tax decisions, accurate real estate appraisal helps you move forward with more confidence and less uncertainty.

Bottom Line

The Chicago housing market remains structurally tight, especially in single-family housing, and that continues to support pricing into March 2026. But this is still a rate-sensitive market with uneven conditions across segments. That makes reliable real estate appraisal especially valuable.

When the market is stable but fragile, your advantage comes from clear analysis, supportable conclusions, and local appraisal expertise.

2026 Cook County reassessment notice used for property tax appeal appraisal
2026 Cook County Reassessment Appraisal: Protect Your Property Taxes

A Cook County reassessment appraisal is an independent, USPAP-compliant opinion of your property’s value, prepared so you can support a property tax appeal when the county’s new number looks too high. The 2026 notices are landing across the county right now. The figure on yours sets the taxable value for the next three years, so it earns a close read before you file it away.

By the end of this article, you’ll know:

  • Why the county’s assessment can miss what your property is really worth
  • Which owners have the strongest reason to appeal
  • How township deadlines work, and what evidence actually moves a decision

What a Cook County Reassessment Appraisal Actually Does

The Assessor’s Office values every parcel in the county, which is an enormous job. To handle that volume, it uses mass appraisal: neighborhood data, historical trends, and statistical models that assign values in bulk. That method is efficient, but it is also blunt. It describes the average property on your block better than it describes yours.

A reassessment appraisal works the other direction. A certified appraiser inspects your specific property and builds an opinion of value from comparable sales, market rents, physical condition, and income, all documented under the Uniform Standards of Professional Appraisal Practice set by the Appraisal Foundation. The result is independent and tied to evidence, not to a countywide model. When you file an appeal, that is what gives your position weight. You can see how we handle these assignments on our real estate appraisal services page.

Where the County’s Mass Appraisal Misses Your Property

Mass models run on assumptions, and assumptions break down at the individual level.

Condition is the common one. Deferred maintenance, an aging roof, or outdated mechanical systems rarely show up in county data, yet they pull real value out of a building.

Income properties get missed too. If your building carries vacancy, below-market leases, or rising operating costs, a statistical model will not feel any of that. It sees square footage and a neighborhood, not a rent roll under pressure.

Timing matters as well. Markets move, cap rates shift, and investor demand changes faster than assessment cycles do. When the county’s data lags the market, your assigned value can sit above what a buyer would actually pay. Then the tax bill climbs even though performance has not.

Who Should Take a Second Look Before the Deadline

Not every notice is worth challenging. Some assessments are fair, and appealing them only wastes time. But a few situations almost always justify a closer review.

Look harder at your reassessment if you own commercial or multi-family property, or if you bought recently at a price below the new assessed value. The same goes if income has slipped, vacancy has risen, or the building needs significant repairs. Owners handling estate, trust, or divorce real estate should pay attention too, because the assessed value can ripple into those proceedings. So should the CPAs and attorneys advising them.

Because the 2026 figure holds for a full three-year cycle, even a modest reduction compounds. On commercial and investment property, that can add up fast, which is why our commercial appraisal clients tend to run the numbers early.

How the Appeal Timeline Works

Each township in Cook County opens and closes on its own schedule, and the deadlines are firm. Once your township’s window shuts, your options for that year are mostly gone.

Most appeals start at the Cook County Board of Review, where you submit evidence supporting a lower value. The Board weighs that evidence and issues a decision. If it does not resolve things, the Illinois Property Tax Appeal Board is the next stop. In both venues, an appeal built on a documented appraisal reads very differently from one built on a homeowner’s hunch. The discussion shifts from opinion to analysis, and analysis is harder to wave off.

Waiting is the quiet mistake. A rushed filing in the final week rarely produces the strongest case. Reviewing your notice early gives you time to decide whether an appeal even makes sense, and to prepare the documentation properly if it does.

What to Do With Your 2026 Notice

Start by reading the assessed value the way a buyer would. Would your property actually sell for that today? If the answer is yes, you can probably let it stand. If it feels high, or if your income numbers no longer support it, that is your signal to get an independent appraisal before your township deadline.

The 2026 reassessment is a proposed value. You have the right to test it, and the evidence to do so is well within reach.

Think Your 2026 Assessment Runs High?

We prepare USPAP-compliant appraisals built to stand up at the Board of Review, tailored to your property and your township’s deadline. Let’s find out whether an appeal makes financial sense.

Request Your Appraisal Quote

Frequently Asked Questions

What is a Cook County reassessment appraisal?

It is an independent, USPAP-compliant opinion of your property’s value, prepared by a certified appraiser so you can support a property tax appeal. It looks at your specific property rather than a countywide model.

Does a higher assessment always mean I should appeal?

No. Some reassessments are accurate, and appealing them is not worth the effort. An appraisal helps you tell the difference before you commit to filing.

What evidence carries the most weight in a property tax appeal?

A documented appraisal supported by comparable sales, market rents, and condition analysis tends to carry the most weight. It moves the discussion from opinion toward verifiable data.

How long do I have to appeal my 2026 reassessment?

Each Cook County township has its own appeal window, and the deadlines are firm. Check your township’s schedule as soon as your notice arrives, because late filings are generally not accepted.

Can an appraisal help with commercial or investment property appeals?

Yes. Commercial and multi-family properties often benefit most, since vacancy, below-market leases, and rising expenses are exactly the factors a mass model overlooks.

Need an Independent Appraisal in Cook County?

PahRoo Appraisal & Consultancy prepares independent, USPAP-compliant valuations across Chicago and Cook County, led by Michael Hobbs. Alongside property tax appeal work, we handle commercial and estate assignments, and you can reach the team any time through our contact page. If your 2026 notice looks off, the earliest review gives you the most room to act.


2026 Commercial Refinancing Cliff showing CRE loan maturities
The 2026 Commercial Refinancing Cliff

The 2026 Commercial Refinancing Cliff is no longer theoretical. It is here.

More than $1.5 trillion in commercial real estate loans are scheduled to mature between now and the end of 2026. Many of those loans were originated in a low-interest-rate environment that no longer exists. What was once inexpensive leverage is now a refinancing challenge.

However, this is not just about higher rates.

It is about tighter underwriting, valuation recalibration, and a new level of scrutiny from lenders. In this environment, a professional commercial appraisal is not a checkbox. It is leverage.

For attorneys, bankers, accountants, and commercial property owners, the question is simple:

What is the property defensibly worth today, not in 2022?

The Reality Behind the $1.5 Trillion Maturity Wave

According to the Mortgage Bankers Association (MBA), more than $1.5 trillion in commercial mortgage debt is scheduled to mature through 2026. Federal Reserve rate policy shifts and capital market tightening have further complicated refinancing assumptions. Data from Trepp’s CRE research reports also shows increased delinquency pressure across certain asset classes, reinforcing why accurate underwriting inputs matter more than ever.

As a result, many properties now face a triple pressure point:

1. Higher Borrowing Costs

Interest rates remain materially above the levels of five to ten years ago. Even stabilized assets may struggle to meet prior debt service metrics.

2. Stricter Underwriting Standards

Debt Service Coverage Ratio (DSCR) thresholds are tighter.
Loan-to-Value (LTV) limits have compressed.
Credit committees are scrutinizing assumptions with far more conservatism.

3. Valuation Volatility

Office usage has shifted. Retail absorption varies by submarket. Insurance costs and operating expenses have risen across multifamily and hospitality. Industrial demand has cooled in certain corridors.

Because of these factors, refinance proceeds may not match the maturing loan balance. That difference is the equity gap.

The 2026 Commercial Refinancing Cliff is not just about rates. It is about value recalibration.

Why the 2026 Commercial Refinancing Cliff Creates Equity Gaps

When a loan matures, the lender evaluates current market value, not historic purchase price or past optimism.

If valuation declines — even modestly — leverage compresses.

For example:

      • A property financed at 75% LTV five years ago may now qualify for only 60–65%.
      • NOI adjustments from higher expenses reduce supportable loan proceeds.
      • Lease rollover risk may materially impact underwriting assumptions.

Without a clear, defensible appraisal, negotiations become reactive instead of strategic.

You do not want to discover the equity gap at the closing table.

You want clarity months in advance.

How a Professional Appraisal Protects Your Refinance

A credible commercial appraisal provides more than a number. It provides positioning.

1. You Gain Realistic Market Intelligence

In a K-shaped recovery, some assets are outperforming while others struggle. A data-driven appraisal clarifies where your property sits within its competitive set.

This is not about optimism.
It is about defensibility.

With credible market analysis, you walk into lender conversations prepared — not guessing.

2. You Reduce Credit Committee Friction

Bankers are under pressure. Regulators are watching. Risk tolerance has narrowed.

A well-supported appraisal:

      • Documents income stability
      • Addresses lease rollover exposure
      • Explains market absorption trends
      • Clarifies capitalization rate positioning

When documentation is thorough, lender objections decrease.

Instead of debating assumptions, the conversation shifts to structure.

That shift matters.

3. You Strengthen Negotiation Leverage

If refinancing falls short, you may need:

      • Additional equity
      • Loan restructuring
      • Capital partner discussions
      • Workout negotiations

An accurate appraisal becomes the anchor for every one of those conversations.

Attorneys negotiating restructuring need defensible value.
Accountants advising clients need realistic asset positioning.
Owners evaluating capital calls need clarity before making commitments.

The 2026 Commercial Refinancing Cliff rewards preparation. It penalizes delay.

What Credit Committees Are Looking for in 2026

Understanding lender psychology improves outcomes.

In 2026, credit committees are prioritizing:

      • Sustainable NOI (not peak-year income)
      • Conservative vacancy assumptions
      • Verified lease terms
      • Expense normalization
      • Realistic exit capitalization rates

Credit committees are stress-testing projections and comparing submarket trends with increased scrutiny. Tenant credit quality is also under deeper review than in prior cycles.

A professional appraisal anticipates those questions before they are asked.

That preparation reduces uncertainty and uncertainty is what stalls approvals.

Asset Class Sensitivity Matters

Not all properties face the refinancing cliff equally.

Office:
Tenant downsizing and hybrid models continue to pressure absorption in many CBD submarkets.

Multifamily:
Higher insurance premiums and operating costs impact net income, particularly in Sunbelt regions.

Retail:
Service-oriented and grocery-anchored centers are outperforming discretionary retail.

Industrial:
Cooling demand in certain logistics corridors has moderated rent growth assumptions.

An appraisal grounded in real-time submarket data distinguishes resilient assets from vulnerable ones.

Generic modeling does not.

The Risk of Waiting

One of the most common mistakes owners make is waiting until 30–60 days before loan maturity to obtain an appraisal.

By then:

      • Negotiating leverage is reduced
      • Alternative lenders may require expedited underwriting
      • Equity partners have limited time for review

Early appraisal provides optionality.

Optionality means:

      • Time to source new capital
      • Time to restructure intelligently
      • Time to adjust strategy

The 2026 Commercial Refinancing Cliff is steep. But it is manageable for those who prepare early.

Why This Matters to You

If you are advising clients — or protecting your own portfolio — uncertainty is the real risk.

A defensible commercial appraisal gives you:

      • Clarity before negotiations begin
      • Credibility in front of lenders
      • Data to support restructuring discussions
      • Strategic positioning instead of reactive decision-making

In this lending environment, numbers unsupported by rigorous analysis will not survive credit review.

Professional documentation will.

Prepare Before the Maturity Date

The refinancing wave is not slowing. It is accelerating toward 2026.

The question is not whether underwriting has tightened.
It has.

The question is whether you enter the refinance discussion prepared.

The 2026 Commercial Refinancing Cliff separates speculative assumptions from defensible analysis.

An early, well-supported commercial appraisal provides the clarity you need to protect equity, strengthen negotiations, and move forward with confidence.

Chicago condo months of supply February 2026
Chicago Residential Real Estate Market Trends – Week 7

Chicago Residential Real Estate Market Trends – Week 7, 2026

The latest Chicago residential real estate market trends show declining pending sales, rising months of supply, and widening pricing gaps across Cook, DuPage, Lake, and Will Counties.

If you rely on defensible real estate appraisal analysis for litigation, lending, estate planning, or brokerage strategy, these trends directly affect risk exposure and value conclusions.

This market intelligence is based on Week 7 data ending February 13, 2026.

Executive Summary: A Market Tilting Toward Buyers

Week 7 data confirms continued softening across the Chicago residential landscape.

      • Cook County pending sales: -26.6% YoY
      • Lake County pending sales: -13.8% YoY
      • Single-family months of supply: Up as much as 40.6% YoY
      • 30-year mortgage rate: 6.09% (down 11.4% YoY)

You can verify national mortgage rate trends via the Freddie Mac Primary Mortgage Market Survey.

And historical 30-year fixed data on FRED: https://fred.stlouisfed.org/series/MORTGAGE30US

Lower financing costs typically stimulate activity. However, current Chicago residential real estate market trends show buyers remain cautious despite improved borrowing conditions.

Why this matters to you:
When absorption slows while inventory expands, appraisal support must carefully reconcile time adjustments, pricing pressure, and concession analysis.

Single-Family Homes: Supply Expansion Meets Demand Slowdown

Cook County

      • Active Inventory: 3,415 (-8.1% YoY)
      • Pending Sales: -26.6% YoY
      • Median Days on Market: 84 (+9.1%)
      • 25.8% of listings reduced price

Longer marketing times combined with widespread price reductions indicate negotiating leverage is shifting.

For attorneys and lenders, this affects:

      • Date-of-value defensibility
      • Retrospective appraisal exposure
      • Refinance underwriting risk

If your case or transaction requires court-defensible analysis, review how PahRoo structures litigation-ready appraisal reports, you can find out more from here: If Your Appraisal Gets Challenged, Does It Hold Its Ground?

DuPage County

      • Median Absorbed Price: $489,900 (-14.7% YoY)
      • Absorbed-to-List Ratio: 75%

A 75% absorbed-to-list ratio suggests significant discounting in upper-tier suburban segments.

For estate planning or partnership disputes, this means comparable selection must be segmented and time-supported, not averaged.

If you need a defensible residential appraisal for lending, litigation, or estate work, start here: Residential Home Appraisal Services

Will County

      • Inventory: +14.3% YoY
      • Months of Supply: +40.6% YoY

Rapid supply expansion without matching demand creates downward pricing pressure if Q2 stabilization fails.

For Chicago-area assignments requiring defensible, court-ready analysis, review our Chicago Real Estate Appraisals services.

Condominium Market: Mixed Signals

Condo segments present a more nuanced pattern within current Chicago residential real estate market trends.

Cook County Condos

      • Active Inventory: -9.7% YoY
      • Median Absorbed Price: -5.1% YoY
      • Days on Market: 70 (-9.1%)

Shorter marketing times contrast with price softening, suggesting selective buyer activity rather than broad strength.

Will County Condos

      • Inventory: +56.4% YoY
      • Months of Supply: +53.2% YoY

Oversupply risk is emerging in specific condo corridors.

If you’re handling probate, divorce, or estate assignments, market segmentation is critical. Learn how probate appraisal risk is addressed here: Chicago Probate Appraisal: A Legal Safeguard in 2026

Pricing Indicators Professionals Should Monitor

Key signals in these Chicago residential real estate market trends:

      • Absorbed-to-List below 100% in DuPage (75%) and Lake (77%)
      • 25.8% of Cook single-family listings reducing price
      • Days on market expansion in key submarkets
      • Declining pending-to-new-list ratios

These increase:

      • Refinance exposure
      • Litigation sensitivity
      • Estate tax defensibility risk
      • Broker pricing misalignment risk

When absorption weakens and supply expands, appraisal credibility depends on segmented data interpretation, not headline averages.

Interest Rates: A Cushion, But Not a Catalyst

The effective federal funds rate is 3.64% right now.

If you want to track rate movement (and cite it cleanly in a memo, underwriting file, or expert report), use these primary sources:

  1. Check the official benchmark on the New York Fed’s EFFR reference page
  2. Pull the historical trend line from FRED’s EFFR time series
  3. Confirm broader rate context on the Federal Reserve’s H.15 rates release

Here’s the key takeaway for decision-makers: cheaper money helps, but it doesn’t force buyers off the sidelines. Current Chicago residential real estate market trends show that even with easing borrowing costs, transaction velocity hasn’t snapped back.

Why? Buyers still act like they’re holding the remote. They’re waiting for clearer signals: pricing realism, job confidence, and the sense that they won’t overpay today for a market that could soften tomorrow.

Q2 2026 Outlook: Stabilization or Prolonged Buyer’s Market?

If:

      • Pending sales stabilize
      • Months of supply plateaus
      • Mortgage rates remain near 6%

The market may rebalance by late Q2.

If:

      • Inventory continues rising
      • Price reductions expand
      • Absorption weakens further

A prolonged buyer’s market becomes likely.

For attorneys, bankers, accountants, and brokers, this is where professional-grade real estate appraisal analysis protects you from unsupported assumptions and mispriced exposure.

Markets move fast. Risk moves faster. Stay informed with our Chicago Real Estate Market Insights and Weekly Analysis Updates.

Why These Chicago Residential Real Estate Market Trends Matter to You

You gain:

      • Early identification of pricing pressure
      • Stronger comparable support
      • Defensible time adjustments
      • Reduced underwriting or litigation exposure
      • Market-backed decision clarity

In a transitioning environment, precision matters.

Is your assignment, transaction, or case dependent on analysis that will actually hold up under scrutiny?

NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712