Category: Property Tax

Request a quote

Our blog

Latest news
& events

Property owner reviewing a 2026 Cook County reassessment notice at home
South Suburbs Reassessment 2026: When to Get a Second Opinion

The 2026 south suburbs reassessment is landing in mailboxes, and some of the numbers are startling. Jumps of 30 percent are common in reassessment years, and some properties see far more. Before you accept a number that will follow you for three years, it is worth understanding how it was produced and how to test it.

By the end of this article, you’ll know:

  • Why the 2026 reassessment matters through 2028, not just this year
  • How mass appraisal produces large jumps, and where it goes wrong
  • When an independent appraisal justifies a formal appeal

What the 2026 South Suburbs Reassessment Actually Sets

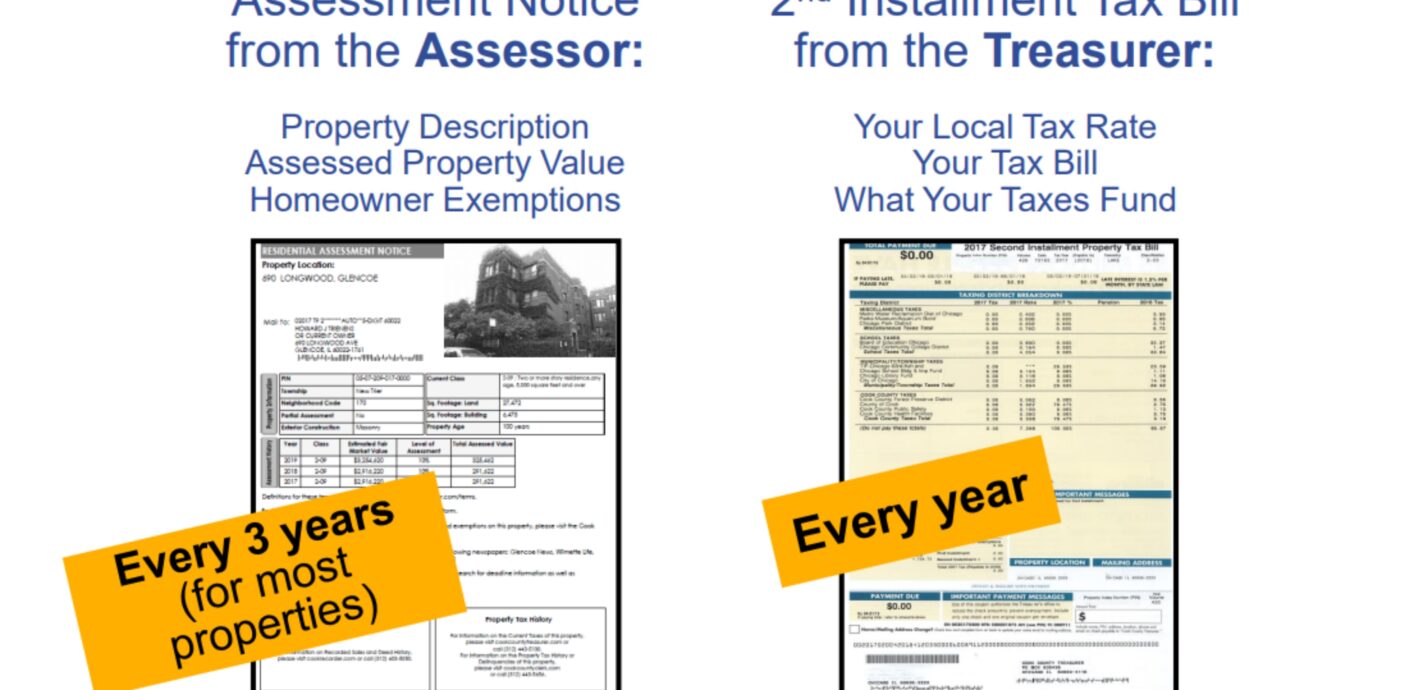
Cook County reassesses one third of the county each year on a triennial cycle. In 2026, it is the turn of the south and west suburban townships. The Cook County Assessor’s assessment calendar shows townships opening on a rolling schedule, with reassessment notices mailed as each township opens. The value on that notice becomes the base for the 2026 through 2028 tax years unless it is successfully challenged.

That three-year reach is the point people miss. An inflated 2026 value does not just raise one bill. It compounds across three billing cycles, and reassessment generally wipes out prior relief, so reductions won in earlier appeals reset to zero.

Why the Jumps Are So Large This Cycle

The south and west triad was last reassessed in 2023, a cycle remembered for steep increases and well-publicized errors. Three years of market movement now gets recognized all at once. That is why a 30 percent jump can appear even when nothing about the property changed. On top of that, 2025 closed with some of the largest tax increases in county history. The average residential bill rose around 16 percent as falling commercial values shifted burden onto homeowners.

So a large 2026 increase sits on top of an already elevated bill. The reassessment itself does not set your tax, but it sets your share of it. If your value rose faster than your township’s overall, your share grows.

Mass Appraisal Gets Averages Right and Individual Properties Wrong

The Assessor values hundreds of thousands of parcels with statistical models, not property-by-property inspections. Mass appraisal is a legitimate technique for that job, but it works from recorded characteristics and neighborhood-level trends. It cannot see deferred maintenance, a functionally awkward floor plan, or the busy arterial road behind your lot line. It also inherits data errors: wrong square footage, wrong classification, improvements that no longer exist.

That gap between the model and the property is exactly what an appeal tests. The question is never whether values rose in your township. They did. The question is whether your specific number reflects what your specific property would sell for.

When a 30 Percent Jump Deserves a Second Opinion

Not every increase warrants a fight. A single-point appraisal of every reassessed parcel would waste money, and some new values are simply accurate. But a few situations justify independent review. The new value implies a sale price the local market cannot support. Similar nearby properties carry meaningfully lower assessments. The characteristics on file are wrong. Or the parcel is income-producing and the implied value ignores actual rents and vacancy. In those cases, an independent appraisal gives you a defensible market value to measure the assessment against. It is developed to USPAP standards, not modeled from averages.

For commercial owners, the stakes multiply. Larger assessed values, higher assessment levels, and three years of exposure mean even a modest percentage error carries six-figure consequences over the triennial.

Act Inside the Window, Because It Closes Fast

Each township’s appeal window opens when its notices mail and closes on a firm deadline. The first stop is the Assessor’s office, then the Board of Review. Windows roll through the fall, and once your township closes, the next chance is a year away with the new value already locked in. So the sequence is simple. Check your notice against reality when it arrives. Get an independent read on value if the number looks wrong. Then file inside your township’s window with evidence attached. Our breakdown of the 2026 Cook County reassessment walks through what that evidence should look like.

Did your new assessment pass the sniff test?

A 2026 value follows you through 2028. PahRoo delivers an independent appraisal that tells you whether the number holds up, before your appeal window closes.

Question Your Reassessment

Frequently Asked Questions

Why did my Cook County assessment increase in 2026?

If your property is in the south or west suburbs, 2026 is your triennial reassessment year. The Assessor updated your value to reflect three years of market change since 2023. That is why increases arrive all at once rather than gradually.

How often does Cook County reassess property?

Every three years. The county is divided into three sections, and one is reassessed each year. The south and west suburbs are reassessed in 2026, and those values generally apply through 2028.

What townships are reassessed in 2026?

The townships of the south and west suburban triad. Each township opens on a rolling schedule through the year, and the Cook County Assessor’s website lists mailing dates and appeal deadlines for each one.

Should I appeal a reassessment?

Appeal when the new value exceeds what your property would realistically sell for. Also appeal when comparable properties are assessed lower, or when the county’s records about your property are wrong. An independent appraisal is the cleanest way to test the number first.

Does an appeal lower my taxes for all three years?

A successful appeal reduces the assessed value that carries through the triennial, so relief won in 2026 generally benefits the 2027 and 2028 bills too. You can also appeal again in the following years if grounds remain.

Independent Valuation for the 2026 Cycle

PahRoo Appraisal & Consultancy provides independent residential and commercial appraisals across Cook County, supporting owners, attorneys, and CPAs through reassessment years. For context on how heavy appeal volume has reshaped the process, see our analysis of record Cook County appeal filings. Or start with our property tax appeal FAQs.
Tax appeal appraisal report and comparable sales evidence prepared for a Cook County Board of Review filing
Tax Appeal Appraisal: What the Cook County BOR Requires

A tax appeal appraisal is only as strong as the evidence rules it satisfies. The Cook County Board of Review has specific requirements, and a report that misses them loses weight before anyone reads the value conclusion. So attorneys and CPAs who order appraisals for appeals need to know exactly what the document must contain.

By the end of this article, you’ll know:

  • The specific evidence the Cook County Board of Review expects with an appraisal
  • Why the lien date, not the filing date, controls the valuation
  • The disclosure and documentation traps that sink otherwise solid appeals

What a Tax Appeal Appraisal Must Contain for the Board of Review

Start with the Board’s own rulebook. The official rules of the Cook County Board of Review spell out the baseline. An appraisal filed with an appeal must include an original photograph of the subject property’s front. It must also list the permanent index number of the subject and of every property used in the appraiser’s analysis. Miss either element, and analysts can discount the report without weighing its conclusions.

The report also has to stand on verifiable comparable evidence. Analysts pull the same public sales records the appraiser used, so every comparable needs a traceable sale that supports the adjustments. Because of that, we build our appraisal reports so each comparable can be checked against county records without a single follow-up question.

The Lien Date Controls Everything

Cook County values property as of January 1 of the assessment year, the lien date. An appraisal with a mid-summer effective date answers the wrong question, even if the analysis is otherwise careful. The report must establish market value as of that lien date, using sales that bracket it.

This trips up more appeals than any technical rule. A refinance appraisal from May, for example, was prepared for a different purpose and a different date. It can still matter, though, which leads to the disclosure problem below.

Disclosure Rules That Catch Filers Off Guard

The Board requires a completed Historical Summary Form for most non-residential appeals. Any transfers or prior appraisals must be disclosed on it. The Assessor’s rules go further. Filers must provide any appraisal or valuation report on the subject prepared within two years before the lien date. That includes reports done for financing or management purposes. So that May refinance appraisal is not optional background. It is discoverable evidence, and hiding it damages credibility.

Income-producing properties carry their own paper burden. Where the property is leased or available for lease, the Board asks for Schedule E filings for the three years before the lien date. Vacancy claims need current income and expense documentation. A tax appeal appraisal for these properties should anticipate that record set, not contradict it.

USPAP Compliance Is a Threshold, Not a Bonus

Appraisals in gross violation of USPAP standards will not be treated as credible evidence. Worse, the Assessor’s office can refer them to the IDFPR for investigation. That is a real professional consequence, and it explains why a cheap report is expensive. Standards published by The Appraisal Foundation govern how the analysis must be developed and reported, and appeal analysts know those standards well.

In practice, USPAP compliance shows up as documented adjustments, a supported highest and best use conclusion, and a clear reconciliation. Boilerplate gets noticed. So does an adjustment grid with no market support behind the numbers.

Build the Evidence File Before the Township Opens

Township windows open on a rolling schedule, and evidence deadlines follow quickly once a township closes. The Board accepts supplemental evidence only up to a set point before the hearing. So a report commissioned late arrives rushed, or after the door shuts. The better sequence starts early. Identify the properties worth appealing, then order the appraisal with the lien date and the Board’s rules written into the engagement. File with a complete package. Appeals resolved on the written file get the same review as those with hearings, which means the written file has to carry the whole case.

Filing at the Board of Review this season?

PahRoo prepares lien-date appraisals built to the Board’s evidence rules, with comparables an analyst can verify line by line.

Get Appeal-Ready Evidence

Frequently Asked Questions

What evidence does the Cook County Board of Review accept?

The Board accepts appraisals, comparable sales data, photographs, and closing documents from a recent purchase. Documentation of factual errors, such as incorrect square footage, also counts. Appraisals must include a front photo of the subject and the PIN of every property in the analysis.

What should a tax appeal appraisal include?

It should establish market value as of the January 1 lien date and comply with USPAP. It also needs verifiable comparable sales with permanent index numbers and a front photograph of the subject. Adjustments need market support an analyst can trace.

Can I appeal my Cook County property taxes myself?

Individual owners can represent themselves on residential appeals. Properties held by corporations, LLCs, or other entities must be represented by an attorney under the Board’s rules. Either way, the evidence requirements are the same.

Do I have to disclose a prior appraisal in my appeal?

Yes. Transfers and prior appraisals must be disclosed on the Historical Summary Form. Reports prepared within two years before the lien date must also be provided, even ones done for financing purposes.

What does a Board of Review appeal cost?

Filing at the Board of Review is free. The real costs are professional ones: an independent appraisal if your case needs valuation evidence, and attorney fees where representation is required or advisable.

Appraisal Support for Cook County Appeal Work

PahRoo Appraisal & Consultancy prepares independent, USPAP-compliant valuations for property tax attorneys, CPAs, and owners across Cook County. If the 2026 cycle has clients asking questions, our guide to the 2026 Cook County reassessment covers when a new assessment deserves a formal challenge. Our property tax appeal FAQs answer the questions clients raise most.

2026 Cook County reassessment notice used for property tax appeal appraisal
Commercial Refinancing Cliff 2026, What the Data Says

The commercial refinancing cliff turned out to be a slope. That is not the same as flat ground. Mortgage Bankers Association data puts $875 billion of commercial and multifamily debt maturing in 2026, down from $957 billion in 2025. Another $652 billion sits behind it in 2027. The peak has passed. What remains is a long stretch of loans written at rates that no longer exist, many already extended once. Every one of them arrives at a credit committee that will ask what the property is worth today.

By the end of this article, you’ll know:

  • What MBA’s 2026 maturity survey actually shows, by property type and by lender type
  • Where the equity gap comes from when a loan matures into a higher-rate, tighter-underwriting market
  • Why an appraisal ordered months ahead of maturity changes the conversation for both the lender and the borrower

What the Commercial Refinancing Cliff Looks Like in the Data

The Mortgage Bankers Association released its 2025 Commercial Real Estate Survey of Loan Maturity Volumes in February. Seventeen percent of the $5.0 trillion in outstanding commercial mortgages, or $875 billion, matures in 2026. That is a 9 percent decrease from 2025. MBA’s chief economist called 2025 a transition year. Lenders stopped simply extending loan terms, and the wall of scheduled maturities began to shrink.

The distribution matters more than the headline. Among property types, 30 percent of hotel loans come due this year. Industrial follows at 23 percent, then office at 17, health care at 15, and multifamily at 13. Among lender types, depositories carry $396 billion of the 2026 maturities. CMBS, CLO, and other securitized loans carry $200 billion. Credit companies and warehouse lenders carry $163 billion. Life insurers hold $76 billion. Agency and FHA multifamily paper, by contrast, has only $39 billion coming due.

So the refinancing question in 2026 is not spread evenly. It sits with banks and non-bank lenders, and with the property types that borrowed hardest in the low-rate years. MBA also notes that the figures are unpaid balances as of December 31, 2025. So the amounts at maturity will be somewhat lower. The direction is still the same.

Why a Maturing Loan Becomes an Equity Gap

A loan written in 2019 or 2021 was sized against a value, a rate, and an income stream. All three looked different from today. When it matures, the lender does not care what the property was worth then. The new loan is sized against current value, current net operating income, and current rates.

Three things compress at once. Higher rates mean the same NOI supports less debt, because coverage has to hold. Tighter underwriting means lower loan-to-value limits and more conservative vacancy and expense assumptions. And where value has fallen, the loan-to-value math starts from a smaller number. The gap between what the new loan will support and what the old loan still owes is the equity gap. Someone has to fill it: the borrower with cash, a partner with capital, or the lender with a restructure.

The loans that were extended in 2024 and 2025 are the ones most exposed now. An extension bought time; it did not change the rate the property has to refinance into. MBA expects the Federal Reserve to be near the end of its rate-cutting cycle. So the relief many borrowers were waiting for is largely already priced in. Our commercial appraisal work in 2026 has increasingly been on exactly these files.

What Credit Committees Are Asking For

The underwriting questions have not changed much. What has changed is how little tolerance there is for assumptions. Committees want sustainable NOI, not the peak year. They want vacancy assumptions that reflect the submarket, verified lease terms and rollover exposure, and normalized expenses that account for insurance and tax increases. Then an exit cap rate that would survive a skeptic.

A lender who orders the appraisal early gets those answers before the file is in front of the committee. A borrower who orders it early gets them before the lender does. That is the better position to negotiate from. Either way, the report replaces the argument. Instead of debating whether the 2021 value still holds, both sides work from a current opinion with the comparables and income analysis laid out.

This is also where property tax belongs in the conversation. A Cook County commercial assessment that runs above market value inflates the expense line. That drags NOI and shrinks the loan the property can support. An appraisal prepared for the refinance often becomes the evidence for an appeal, so the two efforts pay for each other.

Not Every Property Type Faces the Same Cliff

The maturity shares tell you where the pressure concentrates. Hotels carry the largest share of 2026 maturities by property type. Hotel income is also the most sensitive to travel demand and operating cost. Industrial has the second largest share. After years of strong rent growth, underwriting has become more careful about whether that growth continues in a given corridor.

Office is the type everyone expects to see on this list, and 17 percent of office loans do mature this year. The variation between buildings is wide. A leased suburban building and a half-empty tower downtown are both office. They will not appraise or refinance the same way. Multifamily has the smallest share maturing among the major types. Much of that is agency paper with ready refinancing options.

The lesson for a lender or an owner is that the headline number tells you very little about your loan. The property’s own income, its lease roll, its submarket, and its condition decide the outcome. That is what an appraisal is for. It is also why a generic model does not settle a credit committee.

If Your Loan Matures in the Next 18 Months

If you own the property, or advise the owner, start earlier than feels necessary. Ninety days before maturity is too late to source new capital, restructure with a partner, or bring in a second lender. Six to nine months out is when an appraisal gives you room to act on what it says.

Bring the appraiser the full picture. That means the rent roll, twelve months of operating statements, the current tax bill and any pending appeal, capital spending since the last appraisal, and the existing loan terms. An appraisal is only as good as the income it can verify. Then take the report to the lender before the lender’s own appraiser has been ordered. Walking in with a supported number and a plan for any gap is a different meeting than walking in with a hope.

A Slope Rewards the Prepared

The refinancing wave did not break all at once, and MBA’s data says the worst of it is behind the market. What is left is steadier and longer: $875 billion this year and $652 billion next year, much of it already extended. Most of it sits with the banks and private lenders who have the least room to pretend the 2021 value still stands.

For a lender, the early appraisal is how a maturing loan becomes a workable refinance instead of a workout. For an owner, it is how an equity gap becomes a known number with a plan attached, not a surprise at the closing table. Either way, the number has to be current, supported, and written so a credit committee can test it.

Maturing in 2026 or 2027? Know the Number First.

PahRoo prepares commercial appraisals for refinancing, restructuring, and credit review across Chicago and the collar counties, with the income analysis and comparable sales laid out for committee scrutiny. Michael Hobbs, MAI, SRA, signs every report.

Request a Commercial Appraisal

Frequently Asked Questions

How much commercial debt matures in 2026?

According to the Mortgage Bankers Association’s 2025 Commercial Real Estate Survey of Loan Maturity Volumes, $875 billion, or 17 percent of the $5.0 trillion outstanding, is scheduled to mature in 2026. That is 9 percent less than the $957 billion scheduled for 2025, with $652 billion scheduled for 2027.

Is the commercial refinancing cliff over?

MBA’s data suggests the peak of the maturity wave has passed, but the volume remains elevated and many 2026 maturities are loans that were already extended once. The pressure has shifted from size to duration.

What is an equity gap in a commercial refinance?

The difference between the balance owed on the maturing loan and the amount a new loan will support at current value, current income, and current rates. The borrower, a capital partner, or a restructure has to cover it.

Which property types have the most loans maturing in 2026?

By share of outstanding balance, hotel loans lead at 30 percent, followed by industrial at 23 percent, office and health care at 17 and 15 percent, and multifamily at 13 percent, per MBA.

When should an owner order an appraisal before maturity?

Six to nine months out. That leaves time to act on the result: source capital, negotiate a restructure, pursue a tax appeal, or approach a second lender. Ninety days before maturity is usually too late.

Commercial Appraisals Built for Credit Review

PahRoo appraises office, industrial, retail, multifamily, and mixed-use property for lenders and owners across Chicago and Cook County. Our commercial appraisal reports are written for refinancing, restructuring, and litigation, with the income approach shown in full. The same team handles Cook County property tax appeal appraisals, which often start from the same refinance file.

Property tax exemptions impacting appraisal and tax rates
Property Tax Exemptions and Why Non-Exempt Owners Pay the Difference

If you handle Cook County appeals, you have heard this question since Tax Year 2025 bills went out in August. The assessment barely moved, so why did the bill go up? Property tax exemptions are often part of the answer. They change the rate every non-exempt property pays.

By the end of this article, you’ll know:

  • How property tax exemptions push a district’s tax rate up for everyone else.
  • Why the same exemption saves a homeowner far less in some towns than in others.
  • How the Assessor’s 2026 loaded cap rate turns a rate increase into a value question.

How Property Tax Exemptions Change the Tax Rate

Illinois taxing districts start with a budget. Each one sets a levy, the dollar amount it needs to collect. The county then divides that levy by the district’s total equalized assessed value, or EAV. The result is the tax rate.

Exemptions come off EAV before that division happens. The Homeowner Exemption takes up to $10,000 off an owner-occupied home’s EAV. The Senior Exemption removes another $8,000. So every exempt dollar shrinks the base, but the levy still has to be collected. The rate rises until it is.

That is why a flat assessment can still produce a higher bill. Nothing about the property changed. The denominator did.

A Hypothetical District Shows Who Pays

Picture a hypothetical district that needs $40 million from $500 million of EAV. The rate is 8.000%.

Now suppose exemptions remove $50 million of that EAV. The district still needs $40 million, but it now collects it from $450 million. The rate climbs to about 8.889%.

A commercial property with $1 million of EAV and no exemption feels that right away. Its bill goes from $80,000 to about $88,889. That is an 11% increase with no change in value. Homeowners get relief on paper, too. Still, the higher rate claws back part of it, because their remaining EAV is taxed at the new rate.

Why the Same Exemption Saves Less in Some Towns

How much of the savings survives depends on who else sits in the tax base. If a district has a deep commercial and industrial base, the shifted burden spreads across those owners. If it is mostly owner-occupied homes, there is nobody else to absorb it. Then homeowners pay much of their own relief back through the rate.

Research prepared for the Cook County Property Tax Reform Group put numbers on this. The Chicago Metropolitan Agency for Planning and the UIC Government Finance Research Center found the resulting rate increase can erase as much as 90 percent of the homestead exemption’s potential savings in Dolton. For a similarly priced home in Glencoe, the figure is about 14 percent.

The same research traced where the shifted burden lands. It moves mostly to commercial and industrial owners in the same taxing districts. Multifamily housing picks up some of it too, and owners can pass that on to renters.

Where 2025 Bills Moved the Other Way

Exemptions are only one force on a bill, though. The Cook County Treasurer’s analysis of Tax Year 2025 bills found owners countywide were asked for $743.8 million more than the prior year. Homeowners are responsible for $593.4 million of that increase.

So the burden moved toward homeowners this cycle, even with exemptions in place. According to the Treasurer, rising home values and falling commercial values drove much of that shift. In practice, both forces run through every district at once. Which one wins depends on the district’s mix of property.

For attorneys, that matters when a client’s story doesn’t fit the headline. A commercial owner in a homeowner-heavy suburb and one in a downtown district can see very different rate movement in the same year.

The Tax Load Is Where the Rate Meets Value

Here the rate stops being a billing issue and becomes a valuation issue. Starting in 2026, the Cook County Assessor’s Office values all commercial property with a loaded cap rate. Real estate taxes no longer come out as an operating expense. Instead, a tax load is added to the market cap rate.

The Assessor’s published formula sets that tax load as the level of assessment times the equalization factor times the tax rate. So when exemptions push the rate up, the tax load rises with it. A higher loaded cap rate means a lower indicated value.

Run the hypothetical district through that formula, using the Assessor’s own example inputs: a 25% level of assessment, a 3.0355 equalization factor, and a 9.25% market cap rate. At an 8.000% tax rate, the tax load is about 6.07%. At 8.889%, it rises to about 6.75%. On $100,000 of net operating income, the indicated value drops from about $652,700 to about $625,200.

That is roughly 4% lower, driven entirely by the rate. For an appeal, it cuts both ways. The rate in the load has to match the property’s actual taxing district and tax year. An outdated or averaged rate can misstate value in either direction. Our guide to the income approach for commercial property covers how net operating income feeds that math.

What Commercial Owners Can Check on Their Own

Commercial owners don’t need to wait for an appraiser to spot a rate problem. The Assessor publishes township methodology worksheets with the data behind each commercial valuation. Start there and review the income, vacancy, and cap rate assumptions applied to your property.

Next, find the composite tax rate on your Tax Year 2025 second-installment bill. Plug it into the tax load formula above to see what load your actual rate implies. If it lands far from the loaded cap rate the Assessor used, share both numbers with your attorney before your township’s filing window closes.

Also compare full-year totals, not installments. The first installment is 55% of the prior year’s total, so rate changes only show up on the second installment.

Start With the Rate When a Bill Looks Wrong

A flat assessment and a rising bill usually point to the rate. Sometimes exemptions narrowed the base. Sometimes levies rose, or other owners won reductions. Either way, the explanation sits in how the rate was built.

For appeal work, that means documenting the rate with the same care as the value. A property-specific appraisal can show both, and our overview of what the Board of Review expects from appraisal evidence explains how that documentation gets used. The legal strategy stays with counsel. The appraisal’s job is to get the value, and the tax load behind it, right.

Is Your Client’s Tax Load Built on the Right Rate?

We can test the rate, the tax load, and the value behind a Cook County commercial assessment before you file.

Test the Tax Load

Frequently Asked Questions

Do property tax exemptions raise tax rates?

Yes. Exemptions reduce a district’s total taxable value. The levy stays the same, so the rate rises to collect it, and non-exempt properties pay more.

Why did my Cook County tax bill rise if my assessment didn’t change?

A bill equals taxable value times the tax rate. If the assessment held steady, the rate likely rose. Higher levies, lower values elsewhere in the district, and exemption growth can all push it up.

What is a loaded cap rate in Cook County?

Starting in 2026, the Assessor adds a tax load to the market cap rate for commercial property instead of deducting taxes as an expense. The tax load equals the level of assessment times the equalization factor times the tax rate.

Who pays more when homestead exemptions expand?

Research for the Cook County Property Tax Reform Group found the burden shifts mostly to commercial and industrial owners in the same taxing districts, and less so to multifamily housing.

Is the exemption savings shown on a tax bill accurate?

The bill shows the exemption times the current rate. It does not show that exemptions raised that rate. In districts made up mostly of homeowners, real savings can be much smaller.

Appeal Valuations That Account for the Rate

Cook County appeal work at PahRoo starts with the subject property’s own income, condition, and comparables, then checks the tax load against the district’s actual rate. Michael Hobbs and the appraisal team hold MAI and SRA credentials and prepare reports to USPAP Standards 1 and 2 for residential and commercial property. For how recent appeals reshaped the county’s tax base, see our Board of Review analysis. You can also explore our commercial appraisal services.

property tax appeal appraisal evidence under board review
Appraisal Evidence in Cook County Tax Appeals

In January 2025, the Cook County Assessor’s Office published a number that still comes up in appeal conversations. Commercial appeal appraisals came in at a median of 62% of later sale prices. If you file commercial appeals, that figure now shapes how your appraisal evidence gets read, so it helps to know what the study actually measured.

By the end of this article, you’ll know:

  • What the Assessor’s 2025 study of appeal appraisals found and how it was built.
  • Where the study’s own limits sit, and why the 62% figure still matters.
  • What makes appraisal evidence hold up when someone compares it to a sale.

What the Assessor’s Study of Appraisal Evidence Found

The office matched appraisals filed in commercial appeals to later arm’s-length sales over $2 million. The sales ran from 2020 through 2023. After screening out mismatches, the study kept 60 appraisal-sale pairs: 52 commercial and industrial properties, plus 8 large apartment buildings.

The median appraisal came in at 62% of the later sale price. The mean was about 71%. In 49 of the 60 pairs, the appraisal fell below the sale. The spread between firms was wide, too. Median ratios by appraisal firm ran from 46% to 112%.

The Assessor’s framing was direct. If low appraisals are accepted routinely, the tax burden shifts to other owners, including homeowners. That argument gives every reviewer a public reason to test an appeal appraisal against the market.

What the Study Can and Can’t Tell You

The study is worth reading in full, because the office states its own limits plainly. First, the sample is not random. Owners only file appraisals that support a lower value, so appraisals above the assessment never reached the pool. The office says the results would likely improve if it saw those.

Second, time. Sales could occur up to three years after the appraisal’s effective date. A one-year window would have left only 24 pairs, so the office accepted the wider gap. Markets move in three years.

Third, size. With 60 pairs, the office calls its breakdowns by firm, attorney, and class statistically insignificant. Still, it concluded that there appears to be a systemic undervaluation. Those caveats soften the 62% figure. They don’t erase it.

A Hypothetical Shows How Time Moves the Ratio

Picture a hypothetical industrial building appraised at $4.0 million as of January 1, 2021. Industrial demand runs hot for the next two years. The building then sells in late 2023 for $5.6 million.

That pair produces a ratio of about 71%. Yet the appraisal could have been accurate for its date. The market simply moved after it.

Time cuts the other way, too. In the study, commercial buildings over three stories had a median ratio of 105%, which fits a falling office market. But two-to-three-story mixed retail buildings came in at a median near 48%. A gap that wide deserves a harder look than market timing alone.

Why the Bar for Appeal Appraisals Is Rising

The study didn’t change any filing rule. What it did was hand reviewers a benchmark. So an appraisal that sits far below a known sale, offer, or financing appraisal now draws questions faster.

In practice, the appraisals that hold up share a few habits. They use income and expenses supported by the market and the property’s own records. They reconcile the approaches instead of leaning on the lowest one. And when a recent sale disagrees with their value, they explain why rather than leave it out.

Our guide to what the Board of Review requires from an appeal appraisal covers the filing side. For how the income numbers should be built, see our breakdown of the income approach for commercial property. The difference between the Assessor’s model and a property-specific opinion is covered in mass appraisal vs single property appraisal.

What Commercial Owners Should Hand Over Early

A credible appeal appraisal starts with complete records. If you own the property, send the appraiser your rent roll, current leases, and two or three years of income and expense statements.

Then disclose anything that points to value. That includes a recent purchase, a listing, a written offer, or a lender’s appraisal from a refinance. If an appraisal ignores a number like that, it becomes easy to challenge. Also tell your attorney about it before filing, since they decide how the evidence gets used.

Write the Appraisal as if the Sale Is Coming

The simplest test for appraisal evidence is this: would it still look reasonable if the building sold next year? If the answer is yes, the report is doing its job. If it only works because nobody will check, it won’t hold up for long.

That means a report developed under USPAP Standards 1 and 2, built from the subject’s own income and condition, and reconciled to the sales the market actually produced. The legal strategy stays with counsel. The appraisal’s job is to give that strategy a value it can stand behind.

Will Your Appraisal Hold Up Next to a Sale Price?

We prepare Cook County appeal appraisals that reconcile to the market, so your filing starts from a value that survives comparison.

Request an Appeal Appraisal

Frequently Asked Questions

What did the Cook County Assessor’s appraisal study find?

The January 2025 study matched 60 appraisals filed in commercial appeals to later sales over $2 million. The median appraisal was 62% of the sale price, and 49 of the 60 appraisals came in below the sale.

Does the study mean appeal appraisals get rejected?

No. The Assessor’s Office says it does not treat appraisals as the final word on value but may consider them. The study gives reviewers a benchmark, so appraisals far below known sales draw more questions.

Why can an accurate appraisal come in below a later sale price?

The study allowed sales up to three years after the appraisal date. If the market rose in that time, even an accurate appraisal will show a low ratio. The office also noted its sample only included appraisals filed to lower values.

What makes appraisal evidence credible in a Cook County appeal?

Market-supported income and expenses, a clear reconciliation of the approaches to value, and an explanation for any recent sale or offer that points to a different number. The report should be developed under USPAP Standards 1 and 2.

Should an owner tell the appraiser about a recent sale or offer?

Yes. An appraisal that ignores a known sale, offer, or lender appraisal is easy to challenge. Share it with the appraiser and your attorney before filing.

Appeal Appraisals Built to Be Tested

At PahRoo, every Cook County appeal assignment starts with the subject’s own rent roll, expenses, and condition, then checks the value against the sales the market has produced. Michael Hobbs and the appraisal team hold MAI and SRA credentials and prepare reports under USPAP Standards 1 and 2 for residential and commercial property. For how recent appeals reshaped the county’s tax base, read our Board of Review analysis, or explore our commercial appraisal services.

Commercial real estate appraisal in Chicago after the 2025 north suburban reassessment
Do These Chicago Commercial Values Hold Up?

The question in this post’s title now has an answer with data behind it. The 2025 north suburban reassessment has run its full course, appeals included. So the commercial real estate appraisal Chicago owners bring to the table matters more than it did a cycle ago. Here is the short version. Values went up, appeal reductions got smaller, and the Assessor’s office is actively defending its numbers. The owners who did best brought evidence. The ones who brought complaints paid retail.

By the end of this article, you’ll know:

  • The 2025 north suburban results, from the Assessor’s own releases.
  • Why commercial appeal reductions shrank from 20% to 14%, and what that signals.
  • What to do now, since the 2025 values are landing on 2026 bills.

What the 2025 North Suburban Numbers Show

Start with the scale. The Assessor’s April 2025 release on Evanston Township reported total assessed value growing 28%. That reflects three years of market change since the 2022 cycle. Then came the appeals, and the Assessor’s wrap-up on the 2025 cycle tells the rest. Take the 13 north and northwest suburban townships together. Homeowners’ share of the tax base moved from 66% before reassessment to 68% after appeals. In 2022, that shift ran from 63% to 67%, roughly twice as large.

The commercial side explains the difference. Board of Review appeals reduced commercial values 14% in the 2025 cycle, down from 20% in 2022. So the burden still shifted toward homeowners, but less, because commercial reductions got harder to win.

The Appeal Climate Tightened

Two details from the Assessor’s release show why. First, the office defended 14 large commercial properties through the appeal process, mostly data centers. Four received no reduction at all, and four more received reductions under 25%. Second, a December 2024 report found north suburban industrial properties typically assessed at two-thirds of market value after appeals. That is exactly the kind of finding that invites tougher defense of commercial values. Put plainly, the easy reduction era is fading. The data center defense also fits the wider 2026 picture, where high-growth niches attract both capital and assessor attention. A class the market prices confidently is a class the county values confidently, and defends the same way. Owners of ordinary buildings inherit that posture whether they like it or not. We tracked the same pattern countywide in our BOR data breakdown. In short: record appeal volume, rising scrutiny, and outcomes that follow the evidence.

The Commercial Real Estate Appraisal Chicago Owners Actually Need

In that climate, the appraisal stops being paperwork and becomes the case. A mass-model assessment can still mismatch a specific building. For example: real vacancy the model ignored, capital needs it never saw, income the market will not support. Still, nobody at the Board takes that argument on faith anymore. Instead, the winning file documents it: rent rolls, comparable sales, and a traceable income analysis. We detailed that discipline in NOI and cap rates under scrutiny. For portfolio owners, a preliminary review screens which parcels carry a real gap. Then the full workup goes only where it pays. The complete playbook lives in our commercial tax appeal guide.

Bills Arrive Now, and the Next Cycle Is Dated

The timing is not abstract. Properties certified in the 2025 reassessment affect second-installment bills issued in 2026. So north suburban owners are meeting these numbers in their mailboxes this year. Meanwhile, the calendar keeps moving. Appeal windows open township by township every year, even between reassessments. Chicago gets revalued in 2027, and the north suburbs come around again in 2028. For example, the evidence file built for a 2026 appeal meets the 2028 notice already standing. The work compounds in the owner’s favor for once.

Translate the tightening into dollars on one building. Say a north suburban property hoped for the old 20% reduction on a $2 million assessed value, a $400,000 trim. At the 2025 cycle’s 14% average, the same appeal yields $280,000 instead. That $120,000 difference stays in the assessed base. Then the equalizer and the local rate multiply it on every bill until something changes. The lesson is not that appeals stopped working. It is that average outcomes got thinner. So the above-average file, the one with documented income and defensible comps, is where the remaining money lives.

Hold the Value Up Before Someone Tests It

The 2025 cycle delivered a clear message to commercial owners north of the city. Assessments rose with three years of market change, and reductions tightened. Also, the office that sets the values now defends them with data. So match the method. Get the building’s real numbers documented, test them against what the assessment implies, and file where the gap is real. A value that holds up is no longer a nice-to-have. It is the price of being taken seriously in the room.

The appeal discounts shrank. Did your evidence grow?

Get a commercial valuation documented for the climate the 2025 cycle just revealed.

Test My Assessment

Frequently Asked Questions

What happened in the 2025 north suburban reassessment?

The 13 north and northwest suburban townships were revalued for the first time since 2022. Evanston Township’s total assessed value grew 28%. After Board of Review appeals, homeowners’ share of the tax base went from 66% to 68%. That is about half the shift seen in the 2022 cycle.

Why did commercial appeal reductions shrink?

Per the Assessor’s release, Board of Review appeals cut commercial values 14% in 2025 versus 20% in 2022. Also, the office actively defended large commercial values through the process. Whatever the mix of causes, the practical effect is the same. Winning a reduction takes stronger evidence than it used to.

When do the 2025 values show up on tax bills?

Properties certified in the 2025 reassessment affect second-installment bills issued in 2026. So the financial impact of the cycle lands this year, which is why owners comparing their bill to their building’s real performance are doing it now.

Can north suburban owners still appeal before 2028?

Yes. Appeal windows open township by township every year, even between reassessments. They run first at the Assessor and then at the Board of Review. An appeal corrects one year’s value, so owners with a persistent gap often file annually until the next cycle resets the number.

When is the next reassessment for the north suburbs?

2028, under the county’s three-year rotation. Chicago is revalued in 2027 and the south suburbs in 2026. Evidence gathered for a current appeal keeps working at the next notice. So the file is worth building once and maintaining.

Commercial Values Built for a Tougher Room

PahRoo Appraisal & Consultancy has valued Chicago-area commercial property for over two decades. An appraiser holding both MAI and SRA designations leads the firm. Maybe your 2026 bill needs testing against a commercial appraisal of what the building actually earns. Maybe a dispute calls for litigation-ready work with testimony behind it. Either way, the value arrives documented, because the 2025 cycle showed what happens to numbers that are not.


Commercial property tax appeal strategy showing how rising levies impact tax bills
Why a Commercial Property Tax Appeal Win Can Still Mean a Higher Bill

A client wins a commercial property tax appeal, the assessment drops, and the next bill still goes up. In Cook County that happens often enough that it’s worth explaining before you file, not after the bill arrives. The reason sits in how Illinois turns levies into tax bills.

By the end of this article, you’ll know:

  • Why an appeal changes a property’s share of the levy, not the levy itself.
  • What Illinois tax caps limit, and what they leave alone.
  • How to measure an appeal win so the client sees what it actually saved.

A Commercial Property Tax Appeal Changes the Share, Not the Levy

Every taxing district in Cook County starts with a levy, the dollars it plans to collect. Districts file those levies with the Cook County Clerk. The Clerk then divides each levy by the district’s total equalized assessed value, or EAV, to set the rate.

So a tax bill is really a slice of a pie. The appeal shrinks the property’s EAV, which shrinks its slice. But the district sets the size of the pie on its own. If the pie grows faster than the slice shrinks, the bill still rises.

That’s why a winning appeal and a higher bill can both be true. We see it in our own files. When we reviewed 275 commercial tax bills from our client records after successful appeals, 38% still rose year over year. That included bills where the assessed value came down by more than 15%. The appeal did its job. Something else moved.

What Illinois Tax Caps Limit and What They Don’t

Many owners assume a tax cap protects their bill. It doesn’t. The Property Tax Extension Limitation Law, or PTELL, limits how much a non-home rule district can extend each year. The increase is held to the lesser of 5% or the prior year’s CPI.

For 2025 levies, billed in 2026, the Illinois Department of Revenue set that CPI at 2.9%. Districts can also add revenue for new construction and for increases voters approve. Home rule governments, including the City of Chicago, aren’t covered by PTELL at all.

The Department of Revenue says it plainly: PTELL limits a district’s total, not any single bill. Individual bills can still rise or fall. Still, countywide, owners were asked for $743.8 million more on Tax Year 2025 bills, according to the Cook County Treasurer. The median commercial bill rose 2.2%, to $11,146.

Other Owners’ Appeals Move Your Rate Too

But the appeal also competes with everyone else’s. When other owners in the district win reductions, the district’s total EAV falls. Then the rate climbs to collect the same levy from a smaller base.

That makes the size of the win relative. A 15% cut in a district where total EAV fell 10% shrinks the property’s share by only about 5.6%. If everyone won the same 15%, nobody’s share would change at all. Exemptions, new construction, and TIF districts reshape the base as well. Our breakdown of how property tax exemptions push rates up walks through that side of the math.

How This Plays Out by Market

While the mechanics are universal, each market applies pressure differently, and sophisticated counsel now accounts for that nuance. These dynamics are documented across property tax systems nationwide, where local governments levy property taxes as a major source of local revenue.

Chicago (Cook County). Aggressive levy growth, overlapping taxing districts, pension funding obligations, and frequent TIF reallocations make Cook County the most visible example. Appeals focused solely on value often fail to anticipate rate compression. For local system nuance, see the Cook County Assessor’s system overview.

Philadelphia. School district funding demands and shifting assessment practices can neutralize appeal gains, particularly when levy increases coincide with reassessment cycles.

Dallas. Rapid municipal growth, infrastructure expansion, and school funding needs create levy pressure that can dilute even substantial assessment reductions.

Naples (Collier County). Special districts, redevelopment initiatives, and targeted funding measures can quietly shift tax burdens, especially in high-value commercial corridors.

Phoenix (Maricopa County). Voter-approved funding measures and expanding tax bases redistribute liability, requiring appeal strategies to be evaluated alongside revenue modeling.

The common thread: assessment appeals are necessary, but no longer sufficient on their own.

A Hypothetical Shows the Win Hidden in a Higher Bill

Take a hypothetical commercial property with a $100,000 tax bill last year. Its district raises the levy by the full 2.9%. Meanwhile, other appeals and changes cut the district’s total EAV by 10%. Hold everything else constant.

If the owner doesn’t appeal, the property’s share grows as the base shrinks. The bill lands near $114,300.

If the owner wins a 5% reduction, the bill still rises, to about $108,600. The client sees an 8.6% increase and may think the appeal failed. In fact, it saved about $5,700 against the bill they would have paid.

If the owner wins a 15% reduction, the bill drops to about $97,200. That’s a savings of roughly $17,150 against doing nothing, even though the bill only fell about 3%.

Setting Client Expectations Before Filing

The fix is mostly in the conversation. Before filing, tell the client the appeal targets value, while the bill also depends on levies and on everyone else’s appeals. Then report the result against the no-appeal bill, not just last year’s bill.

Levy history helps set that expectation. The Clerk publishes an annual tax rate report, and a district that has taken its full PTELL increase every year will likely do it again. A levy increase above 5% also triggers a Truth in Taxation hearing, which gives you advance notice.

In one downtown case, a law firm helped a client avoid a six-figure exposure by pairing its appeal strategy with a levy-impact model. The model flagged a mid-cycle rate increase tied to a local referendum before it surfaced on the tax bill. That outcome didn’t come from litigation skill alone. It came from anticipating the revenue side of the equation.

The value side still has to hold up, too. A reduction only sticks if the evidence behind it does. Our guide to what the Board of Review requires from an appeal appraisal covers that part.

What Owners Can Check on Their Own Bills

Commercial owners can run a quick version of this themselves. Pull two years of second-installment bills and compare the EAV and the composite rate separately.

If the EAV fell and the rate rose, the appeal worked and the levy side moved against you. Then look at which taxing districts drove the change, since the bill lists each one. Bring that comparison to your attorney before the next filing window, so the next appeal starts with realistic numbers.

Measure the Win Against the Bill You Avoided

An appeal can’t control what school districts, municipalities, and other taxing bodies decide to levy. It can control the value those levies get spread across. That is still worth fighting for, even in a year when the total goes up.

So set expectations early, measure the result against the bill the client would have paid, and make sure the value behind the reduction is one that holds up on review. The legal strategy stays with counsel. The appraisal gives it a defensible number.

Support Your Commercial Property Tax Appeal Strategy With Levy Intelligence

If you represent commercial property owners in Chicago, Philadelphia, Dallas, Naples, or Phoenix, winning the appeal is only part of the equation. In levy-driven tax environments, assessment reductions alone don’t always translate into lower tax bills.

Request a Levy Impact Analysis to:

  • Identify where commercial property tax appeal wins may be offset by rising levies
  • Strengthen client communication and expectation-setting before filing
  • Align valuation and appeal strategy with real-world tax outcomes across local taxing districts

Equip your clients with clarity and your practice with a defensible, data-driven advisory edge.

Want the Levy Side Mapped Before You File?

Pair a defensible value with a clear view of the levies behind the bill, so your client knows what the appeal can and can’t change.

Request a Levy Impact Analysis

Frequently Asked Questions

Why did my tax bill go up after I won a property tax appeal?

The appeal lowered your property’s share of each district’s levy. If the levies grew, or other owners won larger reductions, the rate rose enough to outpace your reduction.

Doesn’t the Illinois tax cap limit my bill?

No. PTELL limits the total a non-home rule district can extend, generally to the lesser of 5% or CPI, plus new construction and voter-approved increases. It does not cap individual bills.

Is the City of Chicago subject to PTELL?

No. Chicago is a home rule government, and home rule units are not covered by PTELL. Other districts on a Chicago bill may be.

How should a commercial property tax appeal be measured?

Compare the new bill with what the bill would have been without the appeal, not just with last year’s bill. That shows the savings the reduction actually produced.

How do other owners’ appeals affect my taxes?

When other owners win reductions, the district’s total taxable value falls and the rate rises. Your share depends on how your reduction compares with theirs.

Commercial Appeal Appraisals From Our Lincolnwood Team

From our Lincolnwood office, PahRoo prepares commercial appeal appraisals across Cook County, built from the subject’s own rent roll, expenses, and condition. Michael Hobbs and the appraisal team hold MAI and SRA credentials and develop each report under USPAP Standards 1 and 2. For how recent appeals reshaped the county’s tax base, read our Board of Review analysis, or explore our commercial appraisal services.

Chicago Class 3 multifamily apartment building after the 34% assessment increase
Class 3 Tax Planning After a 34% Assessment Jump

Class 3 tax planning stopped being optional the day the 2024 Chicago reassessment landed. Per the Cook County Assessor’s final data, Class 3 multifamily assessed values rose 34% citywide. That was one of the two largest jumps of any class. Only industrial rose faster. For an apartment owner, that is not an abstraction. The assessment is the base of the bill. So a bigger base means a bigger check unless the value gets challenged with evidence. Here is what the data actually says, and what to do about it.

By the end of this article, you’ll know:

  • How the 34% Class 3 jump compares to every other class, with the source.
  • Why mass-model assessments outrun real rent rolls, and how appeals exploit that.
  • The planning calendar that runs from township windows to the 2027 reassessment.

What the 2024 Numbers Actually Show

Start with definitions. Per the Assessor’s classification rules, Class 3 covers larger multifamily rental buildings, the family that starts at seven units. Also, as residential property it assesses at 10% of market value. Now the growth table, straight from the Assessor’s final 2024 Chicago reassessment data. Class 2 residential rose 18%. Class 5A commercial, the offices and hotels and retail, rose 22%. Class 3 multifamily rose 34%. Class 5B industrial rose 65%. So apartments carried one of the two heaviest increases in the city, and the release says exactly that.

Put the 34% on one building to feel it. Say a 24-unit property carried a $400,000 assessed value into the cycle. A 34% increase moves it to $536,000 before anyone checks the rent roll. Then the equalizer and the local rate multiply the difference on every bill that follows. For example, an owner who shrugs at the spring notice meets that number again each year until an appeal resets it. The planning starts at the notice, not at the bill.

One honest note on geography. Still, township-level swings vary a lot. The Assessor publishes those details on its reassessment data pages rather than in the release. If a specific neighborhood number matters to your planning, pull it from the dashboard instead of trusting a blog’s recollection, ours included.

Why Assessments Outrun Rent Rolls

Mass assessment prices thousands of buildings with models. Then the models run on assumptions: stabilized occupancy, market rents, typical expenses. Still, a real building is rarely that tidy. For example, maybe two units sat vacant through a renovation. Maybe the rent roll carries long-term tenants below market, or the insurance bill doubled. Meanwhile, the model does not know any of that. So the assessment can describe an idealized version of the property. Then the owner pays taxes on a building that does not exist.

So that gap is exactly what appeals are for. The challenge is not an argument about fairness. It is a documentation exercise: actual income against assumed income, actual expenses against typical ones.

Class 3 Tax Planning Runs on Building Evidence

Instead, the winning file for a multifamily appeal looks like underwriting. Rent rolls with real occupancy history. Concessions and collection losses, documented. Operating expenses with the ugly line items included. Then the income approach turns those inputs into a supportable value, which is the analysis review bodies actually test. We broke down how that works in our piece on NOI and cap rates under scrutiny. Also, the full process lives in our commercial tax appeal guide. For owners with several buildings, a preliminary review sorts the portfolio first. So the full workup goes only where the gap justifies it.

Meanwhile, affordable housing owners have an extra layer. Class 9 properties and LIHTC projects carry their own filings and their own rules. So incentive paperwork and appeal strategy need to move together. The Assessor’s published forms are the starting point, and counsel should see both tracks at once.

The Calendar Does the Compounding

Appeal windows open township by township every year, first at the Assessor and then at the Board of Review. So a 34% jump left unchallenged does not cost you once. It compounds through every bill until a successful appeal resets the number. Meanwhile, the next citywide reassessment arrives in 2027 under the triennial cycle, and the appeal volume records keep climbing, as we covered in the BOR data breakdown. Owners who build the evidence file now use it twice: this cycle’s appeal and the 2027 response.

Plan From the Rent Roll, Not the Notice

The 2024 numbers made one thing plain. Multifamily is carrying a heavy share of Chicago’s assessment growth. Meanwhile, the owners who absorb it quietly subsidize the ones who challenge it. So run the planning sequence in order. Pull the actual performance data and compare it to what the assessment implies. Then screen the gap, and file in the window with a value someone can defend in the room. The building’s real numbers are the whole strategy.

Is your building taxed on rents it never collected?

Get a valuation built on your actual income story, ready for the hearing that tests it.

Value My Building

Frequently Asked Questions

How much did Class 3 assessments rise in the 2024 reassessment?

Per the Cook County Assessor’s final data, Class 3 multifamily assessed values rose 34% citywide. That was one of the two largest increases of any class, alongside Class 5B industrial at 65%. Class 2 residential rose 18% and Class 5A commercial rose 22%.

What counts as a Class 3 property?

The Class 3 family covers larger multifamily rental buildings, starting at seven units. As residential property, it is assessed at 10% of market value. The state equalizer and local rates apply after that.

Can I appeal if my building’s income does not support the new value?

Yes, and that mismatch is the core of most multifamily appeals. Document actual rents, occupancy, concessions, and expenses, then show the value those numbers support. Appeal windows open township by township every year at the Assessor and the Board of Review.

Do Class 9 or LIHTC properties plan differently?

Yes. Affordable housing programs carry their own filings and compliance calendars. So the incentive paperwork and any appeal need to move together. Pull the current forms from the Assessor and have counsel review both tracks at once.

When should a multifamily owner start preparing?

Before the township window opens, not after the notice surprises you. The evidence file takes time to assemble. Also, the same file serves this cycle’s appeal and the 2027 reassessment response. Portfolio owners can screen with a preliminary review first.

Multifamily Values With the Evidence Attached

PahRoo Appraisal & Consultancy has valued Chicago-area multifamily and commercial property for over two decades. An appraiser holding both MAI and SRA designations leads the firm. Maybe your appeal needs a commercial appraisal with the income analysis attached. Maybe an acquisition or estate calls for broader appraisal services. Either way, the value arrives documented, built from the building’s real numbers and ready for the people who will test it.


Chicago commercial corridor eligible for Cook County tax incentives
What Cook County Incentives From Class 7 to 8 MICRO Actually Offer

Cook County tax incentives get described in vague superlatives, so here is the actual arithmetic. Most incentive classes assess a property at 10% of market value instead of the standard 25%, which removes 60% of the assessed base for a decade or longer. Also, those are the county’s own published terms, not a sales pitch. The programs cover more ground than most advisors use: commercial projects large and small, grocery stores in food deserts, five south suburban townships, and one 30-year lane most people have never read correctly.

By the end of this article, you’ll know:

  • The real terms of Class 7a through 7d and Class 8, from county sources.
  • What Class 8 MICRO actually covers, which is not what its name suggests.
  • Where the hardship lanes fit, and where valuation work enters.

The Cook County Tax Incentives Map

Per the county’s property tax incentives page, the commercial classes share one schedule: 10% assessment for 10 years, 15% in year 11, 20% in year 12, and all of them are renewable. Class 7a covers commercial projects under $2 million. Then Class 7b covers projects over $2 million. Class 7d covers grocery stores in designated food deserts. Class 8 covers industrial and commercial property in Bloom, Bremen, Calumet, Rich, and Thornton Townships.

Also, two variations round out the map. Class 7c, aimed at newly constructed commercial buildings, runs a shorter clock: 10% for three years, 15% in year four, 20% in year five, renewable. Meanwhile, industrial property has its own lane in the Class 6b, which we covered in detail in our 6b renewal guide. Different doors, same engine: a 60% cut to the assessed base while the incentive holds.

Translate that into one deal to feel the weight. Say a $3 million retail project qualifies for Class 7b. At the standard 25% level, its assessed value is $750,000. At 10%, it is $300,000. So the same levy math that builds every Cook County bill now starts from less than half the base. For example, a lender modeling debt service on the incentive column sees a different project than one modeling the default. That is why the eligibility check belongs in diligence, not after closing.

Class 8 MICRO Is Not What the Name Suggests

The newest class gets misdescribed constantly, so let the county speak. Per the county’s September 2024 release, Class 8 MICRO covers manufacturers of semiconductors, microchips, and associated components, in areas certified as needing substantial revitalization. Also, the terms are striking: a 10% assessment level for 30 years. Still, two caveats matter. It is district-bound, and it is not renewable. So MICRO is a site-selection tool for a specific industry, not a general small-business break, whatever the name implies.

Class 7d Puts Grocery Stores on the Map

The 7d is the county’s food-desert answer, and its terms are the full commercial schedule: 10% for 10 years, then the 15% and 20% steps, renewable. For a grocery operator, that moves store-level economics in a category famous for thin margins. Meanwhile, for a developer, it can turn a marginal site into a fundable one. For the surrounding neighborhood, it is the difference between a vacant box and a produce aisle. So deals like these are where an early eligibility read earns its keep, because the site, the operator, and the municipality all have to line up.

The Hardship Lanes, SER and CEERM

The county’s current list also includes two retention programs. SER, the Sustainable Emergency Relief lane, serves long-term industrial tenants with at least 10 years at the site, documented hardship, and facility age. Meanwhile, CEERM, the Critical Emergency Employee Retention Modification, requires no purchase for value, at least three continuous months of vacancy, and at least 250 jobs at the site. Both exist to keep employers in buildings they might otherwise leave. The eligibility walls are specific, so pull the current forms from the Assessor’s incentives page before assuming a fit.

What Every Class Has in Common

Three threads run through all of these programs. First, municipal support: the resolutions behind these incentives come from village boards and councils, so the political calendar is part of the filing calendar. Then documentation: eligibility runs on records, and the counties audit what they subsidize. Finally, market value: every percentage above applies to a value someone must support. That is where valuation work enters. A documented commercial appraisal anchors the incentive math, and a preliminary review sorts a portfolio before anyone commits. For properties without an incentive, the appeal process remains the other lever on the same bill.

Sixty Percent Is Hiding in Plain Sight

None of these programs are hidden in any real sense. They sit on county webpages with published terms and downloadable applications. Instead, what hides them is habit: advisors quote the standard 25% level because that is the default, and deals get modeled without the incentive column. So run the check early on every qualifying acquisition, development, or retention problem. After all, the classes above move more money than most line items an advisor will ever touch.

Modeling a deal at 25% that could run at 10%?

Get the market value documented before the incentive math, the resolution, or the hearing needs it.

Run My Numbers

Frequently Asked Questions

How much do Cook County incentives cut an assessment?

The main classes assess at 10% of market value instead of the standard 25%, which removes 60% of the assessed base. The level steps to 15% in year 11 and 20% in year 12 on the standard schedule before renewal.

What is Class 8 MICRO?

A 2024 incentive for manufacturers of semiconductors, microchips, and associated components in areas certified as needing substantial revitalization. It holds a 10% assessment level for 30 years and is not renewable. It is industry-specific, not a general small-business program.

What is Class 7d?

The county’s incentive for grocery stores in designated food deserts. It carries the standard commercial schedule: 10% assessment for 10 years, 15% in year 11, 20% in year 12, and it is renewable.

Are the incentives renewable?

Most are. Classes 7a, 7b, 7c, 7d, and 8 are listed as renewable on the county’s incentives page. Class 8 MICRO is the exception: 30 years, one time. Renewals run through the same municipal-resolution machinery as the original filing.

Does the municipality have to support the application?

Yes. These incentives run on resolutions or ordinances from the local government, so municipal support is part of every timeline. Start that conversation early, because a board meeting calendar moves slower than any form.

Valuation Behind the Incentive Math

PahRoo Appraisal & Consultancy has valued Cook County commercial and industrial property for over two decades. An appraiser holding both MAI and SRA designations leads the firm. Maybe an acquisition needs its value documented before the incentive model gets built. Maybe a dispute or estate calls for broader appraisal services, or a hearing needs testimony behind the number. Either way, the value arrives with evidence attached, because every incentive percentage applies to it.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712