Category: Services Offered

Request a quote

Our blog

Latest news
& events

Divorce attorney and expert witness appraiser reviewing a defensible appraisal report before trial
What Makes an Appraisal Defensible on the Witness Stand

Consider a hypothetical Oak Park two-flat in a contested divorce. One appraiser says $1,150,000. The other says $960,000. The judge has to pick, and in Illinois the judge has to explain the pick in writing. What decides it is rarely the number. It is which appraiser can still explain the number after an hour of cross-examination. That is what a defensible appraisal expert witness delivers. It is a different product from a lender appraisal.

By the end of this article, you’ll know:

  • What Illinois and federal courts test when an appraiser takes the stand
  • Where reports break under cross-examination, and how to spot weak ones early
  • What to check before you retain, and what the CPA on the case needs

What Defensible Appraisal Expert Witness Testimony Rests On

Under Illinois Rule of Evidence 702, an expert may testify when specialized knowledge will assist the trier of fact. The rule’s committee comment confirms Illinois is a Frye state. But the general-acceptance burden only applies when the opinion rests on a new or novel scientific methodology. The sales comparison, cost, and income approaches are not novel. So in a Cook County divorce, the fight over an appraiser is rarely about admissibility. It is about weight and credibility.

Federal court is stricter on paper. Under Federal Rule of Evidence 702, the proponent must show four things are more likely than not. The testimony helps the court, rests on sufficient facts or data, uses reliable methods, and applies them reliably. That is the Daubert framework. The committee notes add that valuation opinions get judged by the standards of the appraisal field itself. In practice, opposing counsel in state court borrows the same four questions on cross. Was the appraiser qualified? Is the data sufficient? Does the method have standing in the field? Did the appraiser apply it correctly?

Which standard governs is counsel’s call. What an appraiser controls is whether the report answers all four before anyone asks. Our overview of appraisals in divorce proceedings covers the basics. Below is what changes when testimony is likely.

Where Appraisal Reports Break Under Cross-Examination

The attacks are predictable, because they work. The first is the date. A refinance appraisal carries the lender’s effective date and intended use. In a divorce it answers a question the court did not ask. Under 750 ILCS 5/503, the court applies fair market value as of the trial date or another date it sets. The wrong date sinks a report before the comparables come up. Our article on the date of value in a divorce appraisal explains how that date gets chosen.

The second is verification. Did the appraiser confirm each sale, or lift it from the MLS? Did anyone drive past the comps? An appraiser who cannot describe the confirmation loses that comparable in front of the judge.

The third is adjustment support, and this is where most reports fail. The Colorado Division of Real Estate names four: boilerplate that claims paired sales or regression support but shows no analysis, predetermined adjustments reused from file to file, cost figures treated as market reaction, and averages standing in for real comparisons. Each is one question from collapsing on the stand.

The fourth is the file. USPAP requires a workfile holding all data behind the conclusions, including data considered and not used, plus summaries or transcripts of any testimony. Illinois Rule of Evidence 705 lets cross-examining counsel demand the underlying facts. A thin workfile means a thin opinion, and everyone in the room finds out at once.

Then comes the appraiser. An expert who argues the client’s side, moves the number after a phone call, or forgets a prior report on the same property has written the other side’s closing. Independence, after all, is the whole basis for weight.

What a Defensible Report Looks Like on the Page

USPAP, published by The Appraisal Foundation and authorized by Congress in 1989, is the recognized standard for U.S. appraisers. It requires the appraiser to identify the problem before solving it. That means naming the client and intended users, the intended use, the type and definition of value, the effective date, the property’s relevant characteristics, and any assignment conditions. A court-ready report states each on its first pages, and each matches the case.

From there, the report shows its work. Every adjustment ties back to evidence the reader can check: a paired sale, a bracketed range, a documented buyer interview, or a regression. The reconciliation then says which approach carried the weight and why. Extraordinary assumptions, such as an interior the appraiser could not access, appear up front. And the report discloses what research the appraiser did and did not do, as USPAP’s reporting standard requires.

Format matters too. A lender form limits explanation by design. A narrative report written for litigation walks a judge from the data to the number. It is one reason a divorce appraisal and a price opinion land so differently in court.

What Attorneys Should Check Before the Report Is Ordered

Disclosure shapes the retention. Under Illinois Supreme Court Rule 213(f)(3), a retained appraiser is a controlled expert. On interrogatory you must disclose the subject matter, the opinions and their bases, the qualifications, and any reports. Rule 213(g) then limits direct examination to those disclosures. So the report becomes an exhibit the day the appraiser signs it, and the number cannot drift at trial. Retain early, then, not late.

Vet the witness first. Ask how many times the appraiser has testified at deposition and at trial. Find out whether any court has excluded or limited that testimony. Ask whether they have worked for both husbands and wives, because a one-sided record is a cross-examination theme. Designations matter too; the MAI and SRA require experience beyond a state license. And ask whether they will produce the workfile without a fight.

Then scope the engagement in writing. Name the effective date, or two dates if the case needs a current and a retrospective value, as a quitclaim transfer mid-case often does. State the intended use as the dissolution proceeding. If the appraisal is joint, name both counsel as intended users. Confirm a fixed fee with no tie to the outcome. Confirm a full inspection, which matters most on an estate home with custom features. Our guide to disputed property value in an Illinois divorce lists the records to gather first.

The statute adds one more path. Under 503(l), the court may consult its own financial expert, who is subject to examination and cross-examination too.

For the CPA on the Case

Accountants in a divorce carry the real estate value into the marital balance sheet, the tracing schedule, or a business valuation. If the appraisal falls, those schedules fall with it. Four checks protect your work.

First, match the effective dates. If the business valuation is as of December 31 and the house is as of a May inspection, the balance sheet mixes two markets. So get the appraisal to the same date, or document the bridge. Second, match the definition of value. Section 503(k) calls for fair market value. A lender’s market value definition, or a fair value standard in a business valuation, may not line up. Third, check the arithmetic in the adjustment grid before the number lands in your schedule. The appraiser’s addition error becomes your error on the exhibit. Fourth, if rental property sits inside a business you are valuing, agree with the appraiser in writing on who values the real estate and who values the enterprise. Otherwise the same rent counts twice or not at all.

Keep the appraisal in your permanent file too. The Supreme Court’s standard matrimonial interrogatories ask each party about appraisals from the prior three years and about any net worth statements prepared for them. Whatever you build on the appraisal gets disclosed, so read the report first.

Retain the Witness Before You Order the Report

Sequence is what makes the report defensible. Choose the appraiser you would put on the stand, then order the report from that person. Fix the effective date and intended use in the engagement letter. Get the report early enough to read it, question it, and let the appraiser fix anything that will not hold. A report produced the week before disclosure draws the hardest cross. One built for testimony from the first page usually settles the value question before anyone reaches the courtroom.

Is Your Appraiser Ready for Cross-Examination?

PahRoo prepares litigation appraisals built for Rule 213 disclosure, deposition, and trial. Michael Hobbs, MAI, SRA, signs the report and takes the stand to defend it in Cook County and across our other markets.

Retain an Appraisal Expert Witness

Frequently Asked Questions

What makes an appraisal defensible in court?

It states an effective date, intended use, and definition of value that match the case, uses comparable sales the appraiser verified, supports every adjustment with market evidence, explains which approach carried the weight, and rests on a complete workfile. Then the appraiser explains each choice under cross-examination without changing the number.

Can an appraiser be an expert witness?

Yes. Under Illinois and federal Rule 702, a witness qualified by knowledge, skill, experience, training, or education may give opinion testimony that helps the court. A licensed appraiser with experience in the property type and market generally qualifies. Weight depends on the method and the support behind it.

What happens during appraiser cross-examination?

Opposing counsel tests the effective date and intended use, comparable verification, the evidence behind every adjustment, the workfile, the appraiser’s qualifications and testimony history, and any prior reports on the property. Illinois Rule of Evidence 705 lets counsel demand the underlying facts and data.

What is a Frye or Daubert challenge?

Both ask a judge to exclude expert testimony. Illinois follows Frye, which requires general acceptance only when an opinion rests on a new or novel scientific methodology. Federal courts follow Daubert, which requires sufficient data and reliable, reliably applied methods. Standard appraisal methods are rarely excluded, so most challenges go to weight.

How do you choose an expert appraiser for a divorce?

Look for experience with the property type and price tier, deposition and trial testimony that no court has excluded, work for both sides of prior disputes, an Appraisal Institute designation such as the MAI or SRA, and a willingness to produce the workfile. Then fix the effective date, intended use, and fee in the engagement letter.

Litigation Appraisal and Testimony From One Appraiser

Family law attorneys and forensic accountants across Cook County and the wider Chicago area, along with Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, bring PahRoo Appraisal & Consultancy into contested cases. Since 1999 the firm has prepared appraisals for dissolution, estate, and tax matters, and Michael Hobbs, MAI, SRA, signs every report and is available for deposition and trial. See our residential appraisal services, or contact us with the case caption and the disclosure deadline.
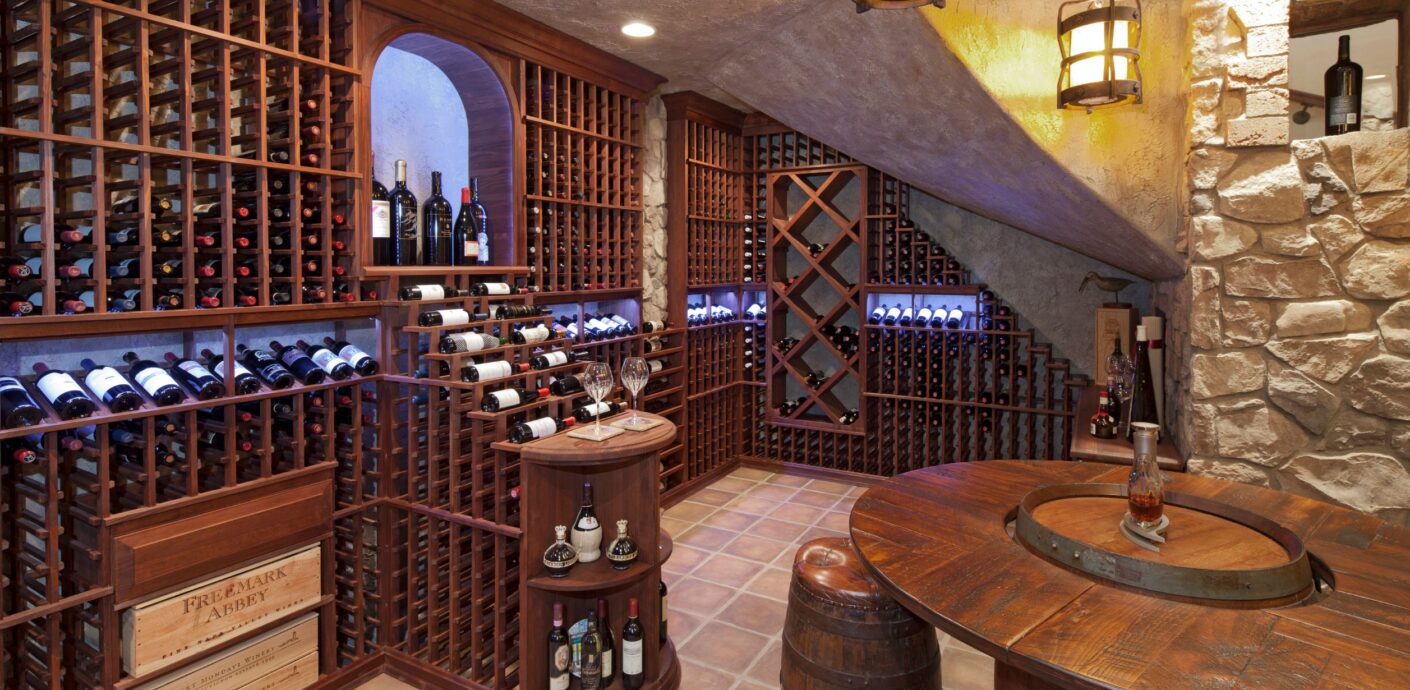

Attorney reviewing a luxury home appraisal report in a high-asset divorce case
Appraising Luxury and Estate Homes in High-Asset Divorce

In a high-asset case, the house is rarely just a house. It might be a 9,000-square-foot estate in Winnetka with a coach house, or a full-floor Gold Coast condominium. The luxury home appraisal divorce counsel puts in front of the court has to survive three readers. An opposing expert, a skeptical judge, and a spouse who is sure the number is wrong. Reports built for lending were never designed for that.

By the end of this article, you’ll know:

  • Why estate and luxury homes are harder to value, and what a defensible method looks like
  • How appraisers find and adjust comparable sales when almost nothing matches
  • What to ask before you retain the appraiser, and how a broker can strengthen the file

What Makes a Luxury Home Appraisal Divorce-Ready

Three things separate a high-value home from the typical marital residence, and each adds risk to the final number. First, the buyer pool is thin. A property at the top of the Kenilworth market competes for a small group of qualified buyers. Second, the features are bespoke. No two estates share the same wine cellar, the same lot, or the same view. Third, the sales data is sparse. A submarket can produce only a handful of closings above a given price in a year.

Illinois law raises the stakes. Under 750 ILCS 5/503, the court must make specific factual findings on the value of each asset. It applies a fair market value standard. And it values the property as of the trial date, or another date the court sets. So the appraisal cannot hedge. It has to state a number, tie it to a date, and show the evidence.

That is where standards come in. The Uniform Standards of Professional Appraisal Practice, published by The Appraisal Foundation, govern how the analysis is developed and reported. A report that follows them names the effective date, explains the scope of work, and supports every adjustment. One that skips those steps hands opposing counsel a script. Our overview of appraisals in divorce proceedings covers the basics. Below is what changes at the top of the market.

Why Few Comparable Sales Is Not an Excuse

Attorneys often hear that there are no comps. In practice that means the appraiser has to work harder. The search widens in three directions.

Geography comes first. A Lake Forest estate may compete with Winnetka, Glencoe, and Barrington Hills rather than the next street over. The buyer choosing among them is the same buyer. The same logic holds in our other markets. A Highland Park buyer in Dallas may also be looking in University Park. Main Line buyers in Philadelphia shop across several townships. A Port Royal buyer in Naples is often weighing Aqualane Shores too. The appraiser then makes a supported location adjustment instead of pretending the sales are next door.

Time comes second. A luxury sale from 18 months ago can still be useful. But the appraiser has to adjust for market movement between that closing and the effective date. That adjustment needs evidence, such as repeat sales or price trends in the same tier, not a guess.

Then the appraiser brackets. Ideally one comparable is superior to the subject and one is inferior. Then the value falls inside a range the market actually produced. Paired sales analysis, where two similar sales differ mainly in one feature, is how the size of an adjustment gets tested. When the paired data is thin, the cost approach steps in as a check. It adds land value from vacant or teardown sales to the depreciated cost of the improvements. It rarely drives the number on an older estate, but it exposes an inflated sales comparison quickly.

Bespoke Features and the Superadequacy Problem

Custom features are where luxury appraisals go wrong most often. An owner who spent $180,000 on a wine cellar expects to see $180,000 in the value. The market usually disagrees.

Appraisers call the excess a superadequacy. The Dictionary of Real Estate Appraisal defines it as an excess in the capacity or quality of a structure or component, judged by market standards. It is a form of functional obsolescence, and it shows up in luxury homes more than anywhere else. The more unusual the feature, the smaller the pool of buyers who will pay for it.

Consider a hypothetical estate in Hinsdale with that $180,000 cellar. Suppose paired sales in the tier show buyers paying roughly $60,000 more for a home with a serious cellar. Then the contributory value is $60,000. The other $120,000 was consumed, not invested. The same math applies to indoor pools, sport courts, elevators, and eight-car garages. The report should state what each feature contributes and show how that figure was derived.

A prior lending appraisal from a refinance is useful here but not decisive. It was written for a different purpose, often on a form that limits explanation. Counsel should still request it, as our guide to disputed property value in Illinois divorce explains. Then expect the litigation appraisal to go well beyond it.

Who Should Appraise an Estate Home in a Divorce

Not every licensed appraiser should take this assignment, and USPAP says so. The Competency Rule requires an appraiser to determine, before agreeing to an assignment, that they can perform it competently. Competency covers the property type, the market, and the intended use. A residential appraiser who works mainly on $500,000 lender assignments may be fully licensed. That same appraiser can still be outside their competence on a $6 million estate headed to trial.

Ask four questions before you retain. How many properties above the relevant price point has the appraiser valued in this submarket in the last three years? Which designation do they hold? The Appraisal Institute awards the MAI for all types of real property and the SRA for residential work. Both require demonstrated experience beyond a state license. Have they testified, and how did the report hold up? And can they support the date of value the case needs, including a retrospective date if the court sets one? Our article on the date of value in a divorce appraisal explains why that last question matters.

Then plan for disclosure. Illinois Supreme Court Rule 213(f)(3) requires a party, on interrogatory, to disclose a controlled expert’s opinions, their bases, qualifications, and reports. A luxury appraisal built to be disclosed reads differently from one built to close a loan. The reasoning is on the page, the comparables can be verified, and the appraiser’s file is ready for deposition.

What Brokers Can Bring to the Appraisal

Luxury brokers hold data the MLS lacks. Off-market sales, buyer feedback on specific features, and the real reason a listing sat for months rarely reach a public record. In a divorce, that knowledge can make or break the comparable analysis.

If you have listed or sold in the subject’s tier, this is what helps the appraiser most. Send the full listing history for the subject, including expired and canceled listings. Prior exposure to the market is evidence of what buyers would not pay. Share any private sales you can verify with a closed price and date. Pass along showing feedback on features the appraiser has to value, such as the indoor pool nobody wanted or the view everyone mentioned. And be candid about concessions and seller credits. A recorded price with, say, $150,000 in credits behind it is not the price the comparable grid should carry.

Brokers also benefit on the back end. If the settlement leads to a sale, a court-ready appraisal gives you a defensible list price. It also protects your own price opinion. A broker price opinion serves a listing decision, but it is not the standard courts apply to a contested value. Our comparison of a divorce home appraisal and a price opinion explains why.

Put the Estate Home’s Value on the Record Early

High-asset cases move slowly, but expert deadlines do not. Retain the appraiser as soon as the property is identified as contested. Agree the effective date with opposing counsel if you can. Then give the appraiser access to the whole property, not a walkthrough of the main floor. If a buyout is on the table, the same report anchors the equity math, as our marital home buyout guide shows. The goal is one number, built on evidence a judge can follow, delivered in time to use it.

Is the Estate Home the Largest Asset in the Case?

PahRoo appraises luxury and estate homes for divorce counsel in Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, with comparables you can verify and an appraiser who will defend the work on the stand.

Order a Luxury Home Appraisal

Frequently Asked Questions

How is a luxury home appraised in a divorce?

The appraiser inspects the whole property, identifies the competing luxury submarkets, and analyzes comparable sales adjusted for location, time, size, and features. Paired sales and the cost approach test the adjustments. The report ties the value to the effective date the court uses and explains every step so it can be defended in testimony.

Why do luxury home appraisals vary so widely?

Thin sales data and custom features leave more room for judgment. Two appraisers may select different comparables, adjust for a feature differently, or treat a costly improvement as full value when the market pays a fraction. A wide gap usually signals weak support in one report rather than a market that cannot be measured.

How do you find comps for a unique home?

Widen the search to the submarkets the same buyer would consider, extend the time frame with a supported market adjustment, and bracket the subject with a superior and an inferior sale. Verified off-market sales, often known to luxury brokers, can fill gaps the MLS leaves.

Who should appraise an estate home in a divorce?

An appraiser with documented experience in the property type and price tier, ideally holding an Appraisal Institute designation such as the MAI or SRA, who has testified and can support the effective date the case requires. USPAP’s Competency Rule puts the burden on the appraiser to confirm this before accepting the work.

Do custom features add their full cost to the appraised value?

Rarely. A feature contributes what buyers in that market will pay for it, which is often less than it cost to build. The excess is called a superadequacy. The appraisal should state each feature’s contributory value and show the market evidence behind it.

Independent Valuation for High-Asset Divorce Cases

Since 1999, PahRoo Appraisal & Consultancy has valued estate homes, luxury condominiums, and complex residential property across Cook County and the wider Chicago area, along with Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, signs every report and is available for testimony. See our residential appraisal services, or contact us to discuss a high-value property.


Adult daughter in the kitchen of an inherited Chicago home before ordering an appraisal for inherited property
Appraisal for Inherited Property Before You Sell or Split

A call we get more often than you would think might run like this. A daughter has just buried her mother. The house in Skokie is paid off. Her brother wants to sell, and the listing agent has already named a price. Nobody has ordered an appraisal for inherited property, and nobody thinks they need one. Then the CPA asks a simple question: what was the house worth on the day Mom died? Silence.

By the end of this article, you’ll know:

  • Why the value on the date of death, not the sale price, drives your tax picture
  • How an appraiser reconstructs value for a date that has already passed
  • What to hand your CPA so the number holds up if anyone asks

Why an Appraisal for Inherited Property Comes First

When you inherit real estate, the tax code does something generous. It resets your cost basis. Under the IRS rules on basis of inherited property, your starting point is the fair market value on the date the owner died. Not what they paid in 1978. Not the assessor’s number. The market value on that one day.

Say the house was worth $650,000 when your mother died. You sell it six months later for $655,000. Your taxable gain is roughly $5,000, less selling costs. Without a defensible date-of-death value, you have no clean way to prove that. And the burden of proof sits with you, not the IRS.

That is why the appraisal comes first. Before the listing agreement. Before a sibling buyout. Before the return gets filed. An appraisal for inherited property is not paperwork for its own sake. It is the document that every later decision leans on. We prepare these as part of our estate planning appraisal work across Cook County every month. The families who order early spend far less time arguing later.

What a Date-of-Death Appraisal Actually Establishes

The appraisal fixes one number: market value as of the date of death. That number does a lot of work at once.

For income tax, it becomes the basis your CPA uses when the property is eventually sold. In a rising market, the reset usually wipes out decades of appreciation. In a falling market, the basis can step down instead of up, which is worth knowing before you plan around a loss.

For estate tax, the same value goes on the return if one is required. Federal estate tax reaches only very large estates, well above what most families own. Illinois is a different story. The Illinois Attorney General’s estate tax fact sheet sets the state exclusion amount at $4,000,000. It works as a threshold rather than a credit. A North Shore home, a retirement account, and a life insurance policy can cross that line faster than people expect. If they do, Form 700 is due nine months after death, and the state wants the appraisals attached.

There is one wrinkle. Under the IRS instructions for Form 706, an executor who files that return can elect alternate valuation. That values estate property as of six months after death instead. The election has to lower both the gross estate and the tax. It also applies to everything in the estate, not just the house. If your CPA is weighing that election, the appraiser needs to know, because it changes the effective date of the whole assignment.

How a Retrospective Appraisal Works When Months Have Passed

Most families call us after the fact. The death was in March, the probate case opened in June, and the CPA asked for a value in September. That is normal, and it is exactly what a retrospective appraisal is for.

A retrospective appraisal has an effective date in the past. The appraiser inspects the property today, then values it as it stood on the date of death. Only the market evidence a buyer could have seen at that time comes into play. Sales that closed after the effective date do not drive the value opinion. Under the standards published by The Appraisal Foundation, the appraiser has to state that effective date clearly and hold the analysis to it. That discipline matters, because the appraiser already knows what the market did afterward.

Condition matters too. If the kitchen was gutted after the funeral, the appraisal has to describe the kitchen that existed on the date of death. Old photos, the listing from a prior sale, permits, and family accounts all help. The more a property has changed since the death, the more this documentation earns its keep.

In practice, a retrospective assignment costs about the same as a current one. The difference is the research. A year-old effective date in a fast-moving Chicago submarket takes real care, so ask any appraiser you interview how they handle the data cutoff.

Where the Date-of-Death Number Gets Tested

The value gets tested in three places, and each one has a different audience.

The first is the sale. When you list, the appraisal tells you whether the agent’s price is realistic and what the gain will look like at closing. A pre-listing opinion of value also gives you cover if a buyer’s lender appraises low and you need to hold your ground.

The second is the split. When one sibling keeps the house and buys out the others, the buyout price should start from an independent number. Not the assessor’s figure, and not a Zestimate. We have watched families lose a year and a relationship over a $40,000 gap that a single report would have settled. Our residential appraisal team handles these buyout assignments with both sides named as intended users.

The third is the courthouse. If the estate goes through the Probate Division of the Circuit Court of Cook County at the Daley Center, the inventory will show a value for the real estate. A USPAP-compliant report backs that figure in a way an online estimate cannot. Whether a particular estate needs probate at all is a question for the family’s attorney, not the appraiser.

For the CPA: What to Ask For Before the Return Is Filed

Accountants call us about inherited property more than any other professional group. The same problems come up every time. So here is what to specify when you or your client orders the report.

First, put the effective date in the engagement. State the date of death, or the alternate valuation date if the executor is electing it on Form 706. An appraisal dated to the inspection is the wrong answer.

Second, name the intended use. Ask for a report prepared for tax basis and estate reporting purposes. That scope tells the appraiser to document market conditions as of the effective date, describe the property’s condition at that time, and explain the data cutoff. A lending form will not do that.

Third, check consistency. If the estate files Form 706, the value reported there controls the heir’s basis. The executor may also have to issue Schedule A of Form 8971 to the beneficiaries. The IRS FAQ linked above notes that a penalty can apply when a beneficiary claims a basis above the estate tax value. One appraisal, used on both the estate return and the heir’s eventual Schedule D, avoids that mismatch.

Finally, keep the report in the permanent file. The property may not sell for a decade. When it does, the basis question comes right back, and the report is the answer. Our earlier piece on qualified appraisals for donated real estate covers the related IRS rules if the heir plans to donate the property instead.

Order the Appraisal Before the Listing Agreement or the Return

Sequence is everything here. Get the date-of-death value first. Then price the listing, negotiate the buyout, or file the return with a number behind it. Families who reverse that order end up backing into a value after the sale. That is harder to defend and more expensive to fix.

Our lane is the value and the report. How the basis is claimed, whether alternate valuation makes sense, and what the return should say are properly the CPA’s work. When both sides do their part early, the number that reaches the IRS is one that holds.

Inherited a Home and Not Sure What It Was Worth?

PahRoo prepares date-of-death and retrospective appraisals that give heirs, executors, and their CPAs one defensible number to build on.

Request an Estate Appraisal

Frequently Asked Questions

Do you need an appraisal for an inherited house?

In most cases, yes. Your tax basis in inherited real estate is its fair market value on the date of death. An independent appraisal is the standard way to document that value. It also settles the number for sibling buyouts, probate inventories, and any state estate tax return.

What is a date-of-death appraisal?

It is an appraisal with an effective date equal to the day the owner died. The appraiser values the property as it stood on that date using market evidence available at the time. The inspection and report can happen months later.

How do you determine the value of an inherited property?

A licensed appraiser inspects the property and reconstructs its condition as of the date of death. Then the appraiser analyzes comparable sales that closed around that date. The report explains the data cutoff and states a market value opinion tied to that effective date.

What is a stepped-up basis?

It is the reset of an inherited asset’s cost basis to its fair market value at the date of death. If the property has appreciated, the heir’s basis steps up, which reduces the taxable gain on a later sale. If the value fell, the basis can step down instead.

Can I get an appraisal months after the death?

Yes. This is called a retrospective appraisal. The appraiser sets the effective date to the date of death. The analysis then uses only information a buyer could have known at that time. It is routine work for appraisers who handle estate assignments.

Estate Valuation Support Across Cook County

PahRoo Appraisal & Consultancy prepares date-of-death, retrospective, and buyout appraisals for heirs, executors, attorneys, and CPAs. We serve Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Every report is developed to USPAP and written so a reviewer can follow the effective date and the evidence behind it. See our full range of real estate appraisal services, or contact our team before the listing agreement or the return goes out.

Signed quitclaim deed on a desk, the kind of divorce transfer an appraiser values at the transfer date
Quitclaim Deed Divorce Transfers and What Appraisers See

A quitclaim deed takes five minutes to sign and a few days to record. In a divorce, that speed is the problem. A quitclaim deed divorce transfer can move a house, a rental building, or a vacant lot to a relative or a new LLC. It can happen before the other spouse knows the marriage is ending. When that happens, the attorney’s first question is usually about the law. My first question is about the date. Everything the court eventually weighs depends on what the property was worth the day it changed hands.

By the end of this article, you’ll know:

  • What a quitclaim deed does, and why it shows up in divorce files
  • The specific things an appraiser checks when a property was transferred mid-case
  • How a transfer-date appraisal gives counsel a number to argue from

What a Quitclaim Deed Divorce Transfer Actually Does

A quitclaim deed conveys whatever interest the signer holds in a property, with no promise that the interest is any good. It is the simplest deed there is. Spouses use it every day for legitimate reasons. Most often, one spouse keeps the house after a marital home buyout and the other signs off.

The trouble starts when the deed runs the other direction, away from the marital estate. A spouse signs the family’s two-flat over to a sibling for ten dollars. A vacant lot moves into a newly formed LLC. Title to a lake house lands with an adult child from a first marriage. On paper the property is gone. In the market, nothing about the property changed that day except the name on title.

That gap is where an appraiser earns a fee. The Illinois Uniform Fraudulent Transfer Act treats real estate as transferred once the conveyance is perfected. It then measures the remedy against the asset’s value at the time of the transfer. Whether that Act, the dissipation rules in the divorce statute, or some other theory applies is the attorney’s call. Each one, though, turns on the same fact: what the property was worth on the transfer date.

Why the Transfer Date Becomes the Effective Date

In most divorce appraisals the court or the parties set the effective date, and it is often the trial date. We covered that choice in our piece on the date of value in a divorce appraisal. A transferred property breaks the pattern. The question is no longer what the house is worth today. It is what walked out of the estate, and when.

So the appraisal is retrospective. I value the property as of the deed’s signing or recording date, using only sales and market conditions that existed then. Sometimes the case also needs a current value, because the court may order the property returned or its value charged against the transferring spouse. That is a second effective date and a second analysis. Ordering both at once costs less than ordering the second one later.

Under USPAP, a retrospective value has to rest on information a market participant could have known as of the effective date. A sale that closed two months after the deed cannot support the value at the deed. Counsel should expect the report to say so plainly.

What an Appraiser Looks For in a Mid-Divorce Transfer

The deed itself is the first exhibit. I read the recorded instrument, not a summary, because the details matter. The grantee’s name tells me whether the property went to an insider: a relative, a business the spouse controls, a close friend. The stated consideration, along with the transfer tax declaration or exemption stamp attached to it, tells me what value reached the county’s records. A deed reciting ten dollars for a $600,000 two-flat is not evidence of value. It is evidence that value was not exchanged.

Then I look at what happened after the transfer. Who is living in the property? Who collects the rent and pays the taxes and insurance? If the transferring spouse still holds the keys and the bank account, the deed changed the name on title and little else. That pattern, retained possession after a transfer to an insider for nominal consideration, appears on the statute’s own list of factors a court may consider. I do not decide whether it is fraud. I do document it, because those facts sit inside the appraisal’s scope.

The property’s condition on the effective date matters too. Photos from a prior listing, a refinance appraisal, permit history, or the other spouse’s recollection all help reconstruct what the building looked like that day. They also show whether the deed came before or after a major repair, a fire, or a new roof.

Lenders meet the same deed from the other side. When one spouse tries to refinance the marital home to fund a buyout, a recent quitclaim to a relative or an LLC surfaces in the title search. Underwriting stalls until the ownership question is settled. A transfer-date appraisal already in the file answers the value half of that question before the loan officer has to ask.

Finally, I check the encumbrances. A property quitclaimed subject to a mortgage moves equity, not the whole value. The report separates the market value of the real estate from the debt against it. That way the attorney sees the actual dollars that left the estate. The same records we recommend in our guide to disputed property value in an Illinois divorce do double duty here.

Reconstructing the Market at the Transfer Date

A retrospective analysis takes more work than a current one, and the reasons are practical. Comparable sales have to reflect the record as it stood then, before later sales and later price movement crept in. Interest rates and inventory as of that date, not today’s, frame the adjustments. When the transfer happened years earlier, archived MLS records, county records, and old listing photos become the evidence base.

The result is a value the court can hold up against the consideration on the deed. A $600,000 building conveyed for ten dollars to a brother-in-law tells its own story once the number is on the table. So does a building conveyed for $580,000 to an unrelated buyer. That one looks like a real sale at a modest discount rather than a stripped asset. The appraisal does not argue the point. It removes the guesswork about the size of the gap.

Where the Appraiser Stops and the Attorney Starts

I establish value at the date the case needs. I document the facts around the transfer that fall within an appraiser’s competence. And I stand behind the report on the witness stand. Whether the deed was fraudulent, dissipative, or voidable, and what remedy the court should order, is legal characterization. That belongs to counsel and the judge. A report that wanders into it loses credibility fast, and opposing counsel will notice.

The same goes for reversing a transfer. Courts have tools to unwind a bad conveyance or charge its value against the party who made it. Which tool fits is a legal question. The appraiser’s job is to make sure that whatever tool the court reaches for, the value it applies is the right one.

Order the Transfer-Date Appraisal Before Discovery Closes

When a transferred property surfaces in a case, pull the recorded deed and the transfer declaration first. Confirm the exact date. Decide with the appraiser whether the case needs one effective date or two. Then order the retrospective appraisal early enough to disclose it with your expert designations. A value produced the week before trial draws the hardest attack. Fix the number to the date, and the rest of the argument has a foundation.

Did a Property Leave the Estate Before the Filing?

PahRoo prepares transfer-date and current-value appraisals for real estate quitclaimed before or during a divorce, documented for discovery and testimony.

Value the Transferred Property

Frequently Asked Questions

What is a quitclaim deed in a divorce?

A quitclaim deed transfers whatever ownership interest the signer holds in a property, with no guarantee of title. In divorce it is commonly used to move the marital home to the spouse who keeps it after settlement. Before or during the case, it can also shift property out of the marital estate to a relative or an entity.

Can a spouse transfer property before a divorce?

A spouse can sign and record a deed, but that does not settle whether the transfer holds up. Courts can examine transfers made in anticipation of divorce, and Illinois law allows dissipation and fraudulent transfer claims in the right circumstances. Whether a given transfer is open to challenge is a legal question for the attorney.

How is a transferred home valued in a divorce?

With a retrospective appraisal. The appraiser sets the effective date at the date of the deed. The value then rests only on sales and market conditions that existed at that time. If the court may also need a current value, the same assignment carries a second effective date.

Is a pre-divorce property transfer reversible?

Sometimes. Courts have remedies that can unwind a transfer or charge its value against the spouse who made it. Fraudulent transfer law provides its own relief. Which remedy applies, and whether one applies at all, depends on the facts and the attorney’s argument. The appraisal supplies the value that sets the size of the remedy.

What is a fraudulent conveyance?

In general terms, a transfer made to hinder, delay, or defraud a creditor. It also covers a transfer made without reasonably equivalent value while the transferor was in financial trouble. Illinois codifies this in the Uniform Fraudulent Transfer Act. Deciding whether a specific deed meets that definition is the court’s job, informed by counsel and by the appraised value at the transfer date.

Appraisal Support When a Deed Changes Hands Mid-Case

Attorneys across Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples bring PahRoo Appraisal & Consultancy into cases where a property changed hands at the wrong moment. Our MAI and SRA designated team prepares retrospective and current-value divorce appraisals built for discovery and cross examination. Start with our overview of appraisals in divorce proceedings, review our residential appraisal services, or contact us with the recorded deed in hand.

Qualified appraisal report for a charitable donation of Chicago commercial real estate.
Qualified Appraisal for Charitable Donation of Real Estate

A CPA called me last spring about a deduction under audit. Her client had donated a piece of Chicago commercial real estate to a nonprofit and deducted $850,000, the appraised value. A charitable donation of real estate rests on a qualified appraisal that meets the IRS definition. This one missed it three ways.

The appraiser was licensed but did not meet the federal definition of a qualified appraiser. The report lacked the required declarations. And the effective date fell three months after the donation. Any one of those flaws can sink the deduction on its own. Together, they put the full $850,000 at risk, plus possible accuracy-related penalties on top.

By the end of this article, you’ll know:

  • What the IRS requires from the report and the appraiser under Treas. Reg. 1.170A-17
  • How the 60-day window and the valuation effective date actually work
  • The Form 8283 steps that protect the deduction if the IRS examines it

What Counts as a Qualified Appraisal for a Charitable Donation of Real Estate

The rules live in one regulation. Under Treas. Reg. 1.170A-17, a qualified appraisal is a document prepared by a qualified appraiser in accordance with generally accepted appraisal standards. The regulation defines those standards as the substance and principles of USPAP, so a report that ignores USPAP fails at the starting line.

The report itself must carry specific content. It needs a detailed description of the property and its condition, the valuation effective date, and the fair market value as of that date. It also needs the appraiser’s identity, qualifications, signature, and date, along with a statement that the appraisal was prepared for income tax purposes.

Then come the declarations. The appraiser must state that they hold themselves out to the public as an appraiser and are qualified to value this type of property. They must also acknowledge that a substantial or gross valuation misstatement can trigger a civil penalty. Because the declarations are mandatory, a report without them can be rejected even when the value itself is defensible. So the engagement should specify a tax-purpose report from the start. We scope our own appraisal assignments around the intended use for exactly this reason.

Who Meets the Qualified Appraiser Definition

A state license is not enough. Neither is experience alone. The appraiser must have verifiable education and experience in valuing the specific type of property being donated, and the report has to document it.

There are two paths. The first is a designation from a recognized professional appraiser organization, earned for demonstrated competency in the relevant property type. For real estate, that includes the MAI, the SRA, and the ASA designations. The second path combines successful coursework in valuing that property type with at least two years of experience doing so.

The appraiser must also regularly perform appraisals for compensation. They cannot have been prohibited from practicing before the IRS during the three years before the appraisal date. Finally, the appraiser cannot be the donor, the donee, or a party to the transaction. So a broker who arranged the gift, however credentialed, is out.

The 60-Day Window and the Valuation Effective Date

Timing trips up more donations than valuation does. The appraisal must be dated no earlier than 60 days before the contribution and no later than the return’s due date, including extensions. The donor must receive it before that due date too.

The effective date follows its own rule. For a report dated before the donation, the effective date must fall within 60 days before the contribution. It cannot fall later than the contribution itself. If the report is dated after the donation, the effective date must be the contribution date exactly. My caller’s file failed here: the value spoke as of a date three months after the gift, which answers the wrong question.

Real estate values move, so this rule has teeth. The fix is usually straightforward. A qualified appraiser can prepare a retrospective appraisal with an effective date matching the donation. The analysis relies only on market evidence available as of that date. That is routine work for firms that handle tax assignments, but it has to be ordered, not assumed.

Form 8283 Is Where the Deduction Survives or Dies

The paperwork converges on one form. For real estate deductions over $5,000, Section B of Form 8283 must be fully completed and filed with the return. The qualified appraiser signs it, the donee organization acknowledges the gift on it, and an incomplete section can void the deduction by itself.

The threshold rises again at $500,000. Above that figure, the full qualified appraisal must be attached to the return, not merely retained in the file. And because the IRS is never required to accept an appraised value, high-dollar gifts draw closer review. Property recently purchased for far less than the claimed value, conservation easements, and unusual property types all invite scrutiny. The government’s own valuation guidance in IRS Publication 561 is worth reading before the return goes out, because examiners certainly have.

One more detail catches people. The appraisal fee cannot be based on the appraised value in any way. A contingent fee arrangement disqualifies the report outright.

Sequence the Appraisal Before the Deed Records

The protective timeline starts before the gift, not at tax time. First, verify the appraiser meets the qualified appraiser definition and will prepare the report to Treas. Reg. 1.170A-17 and USPAP. Then schedule the work so the report date lands inside the 60-day window, with the effective date tied to the planned donation date.

At the donation, document the contribution date clearly through the deed recording or transfer letter. When preparing the return, check the report against the regulation and complete Form 8283 Section B with the appraiser’s signature. Attach the full appraisal for deductions over $500,000. Then retain everything, because the burden in an examination sits with the taxpayer.

Our lane in this process is the value and the compliant report. How the deduction is claimed, timed, and defended on the return is properly the CPA’s work. When both sides do their part at the front end, the deduction that reaches the IRS is one that can hold.

Advising a Client on a Real Estate Donation?

PahRoo prepares qualified appraisals built to Treas. Reg. 1.170A-17 and USPAP, with the declarations, timing, and effective date the IRS expects.

Order a Qualified Appraisal

Frequently Asked Questions

What is a qualified appraisal for a charitable donation?

It is an appraisal prepared by a qualified appraiser under Treas. Reg. 1.170A-17, following USPAP, with required content and declarations. It must state fair market value as of the proper effective date and be timed to the donation and the return.

Who counts as a qualified appraiser under IRS rules?

An appraiser with verifiable education and experience valuing that property type. That is shown through a recognized designation such as MAI, SRA, or ASA, or through coursework plus two years of experience. They must regularly appraise for compensation and cannot be the donor, donee, or a party to the transaction.

When must the appraisal be dated for a real estate donation?

No earlier than 60 days before the contribution and no later than the return’s due date, including extensions. If the report is prepared after the gift, its effective date must be the contribution date, which usually means a retrospective appraisal.

When does Form 8283 require the full appraisal attached?

Real estate deductions over $5,000 require a completed Form 8283 Section B with the appraiser’s signature and the donee’s acknowledgment. Once the deduction exceeds $500,000, the entire qualified appraisal must be attached to the return itself.

Can the IRS reject a deduction even if the value is accurate?

Yes. Missing declarations, a wrong effective date, an unqualified appraiser, an incomplete Form 8283, or a value-based appraisal fee can each disallow the deduction. It does not matter whether the number was right. The rules are procedural, and they are enforced that way.

Appraisal Support for Charitable Gifts of Real Estate

PahRoo Appraisal & Consultancy prepares USPAP-compliant, tax-purpose appraisals for CPAs, attorneys, and property owners across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Our team handles donated residential and commercial property, along with related estate planning valuations. Have a donation on the calendar? Contact our team or call 773-388-0003 before the deed records.


A family home with two parties reviewing documents, weighing a marital home buyout.
Marital Home Buyout: How an Appraisal Sets a Number Both Sides Can Trust

A marital home buyout looks simple from the outside. One spouse keeps the house, pays the other for their share, and everyone moves on. The hard part is the number. Get it wrong and the deal falls apart or a lender walks. A marital home buyout appraisal fixes that number to defensible market value, which is why both sides, and the bank behind the refinance, tend to start there.

By the end of this article, you’ll know:

  • How a buyout figure is actually calculated
  • Why the lender needs an independent appraisal
  • What can shift the number, and who usually pays for the report

What a Marital Home Buyout Appraisal Does

A buyout appraisal is an independent opinion of the home’s current market value, prepared by a licensed or certified appraiser. That value is the anchor. Everything else in the buyout, the equity, each spouse’s share, the size of the refinance, builds off it.

Bankers care because the buyout usually runs through a refinance. The new loan pays off the old mortgage and funds the cash going to the departing spouse. The appraised value sets the loan-to-value, so it decides whether the deal is even financeable. Attorneys care because that same number has to hold up in the settlement.

How the Buyout Is Calculated

The math is short once you have a credible value. Here is the sequence most buyouts follow:

  1. Start with the appraised market value. This comes from the independent appraisal, not a listing estimate.
  2. Subtract the mortgage payoff and any liens against the property. What remains is the net equity.
  3. Subtract agreed costs, if the court allows them. Some settlements deduct estimated costs of sale, others do not.
  4. Split the net equity per the settlement. Illinois divides marital property in just proportions, which is not always a 50/50 cut.
  5. Pay the departing spouse their share. The spouse keeping the home funds it, usually through a refinance.

In short form: buyout amount equals appraised value, minus the mortgage payoff, times the departing spouse’s equity share. Under 750 ILCS 5/503, that share reflects what the court finds equitable, so the split is a legal decision while the value is an appraisal one.

Why Buyouts Are So Common Right Now

Rates are the reason. The 30-year fixed has held in the mid-6% range through 2026, according to Freddie Mac, well above the lows many couples locked in a few years ago. Selling the home and each buying again means trading a cheap mortgage for an expensive one, twice.

So keeping the house through a buyout often beats selling. That makes the appraised value the pivot point of the whole settlement. If the number is soft, the departing spouse feels shortchanged. If it is inflated, the refinance may not appraise out, and the deal stalls.

What Can Move the Number

Condition, recent sales, and the effective date all matter. A home that has been neglected during a long separation may appraise lower than either spouse expects. A fast-moving local market can shift the value between the offer and the closing. So a buyout appraisal is a snapshot tied to one date, and a stale one invites a challenge.

This is where a defensible report earns its fee. The appraiser documents the comparable sales and the reasoning, so the number survives a skeptical spouse, an opposing attorney, or a lender’s review.

Start the Buyout With a Real Value

Order the appraisal before the negotiation hardens, not after. Confirm the appraiser is licensed, works to recognized standards, and can support the effective date the case needs. Then build the buyout off that figure. It is far easier to agree on a split when nobody is arguing about the value underneath it.

Need a Buyout Number That Holds Up?

PahRoo prepares independent, USPAP-compliant appraisals that set a defensible buyout figure for the settlement and the refinance behind it.

Order a Buyout Appraisal

Frequently Asked Questions

How is a house buyout calculated in a divorce?

Start with the appraised market value, subtract the mortgage payoff and any liens to get net equity, then split that equity per the settlement. The spouse keeping the home pays the departing spouse their share, usually funded by a refinance. The appraisal sets the starting number the whole calculation rests on.

Do you need an appraisal for a marital home buyout?

In most cases, yes. A buyout needs a defensible market value, and if a refinance funds it, the lender requires an appraisal anyway. An informal estimate can work only when neither spouse contests the value and no lender is involved, which is rare in a real buyout.

Who pays for the buyout appraisal?

It varies. The spouses often split the fee, the party who orders it pays, or the court allocates the cost. Many couples share one neutral appraisal rather than commissioning two competing reports, which saves money and avoids a battle over whose number is right.

How long is a buyout appraisal valid?

There is no fixed expiration, but the value is tied to a specific effective date. Lenders and courts generally want a recent appraisal, often within the last few months. In a moving market, an older figure gets questioned, so timing the report close to the buyout matters.

Can one spouse force the sale of the home?

That is a legal question for the court, not the appraiser. A court can order the home sold if an equitable division requires it, or it can approve a buyout that lets one spouse keep the house. Either way, the appraisal supplies the market value the decision runs on.

Need an Independent Buyout Appraisal?

PahRoo Appraisal & Consultancy prepares buyout and divorce valuations across Cook County and the wider Chicago area. For more on how we support attorneys, lenders, and their clients, see our residential appraisal services and our overview of appraisals in divorce proceedings, or contact us to order a buyout appraisal.

Modest single-family suburban home with gray siding and a small covered entry, used to illustrate valuing a marital home in a divorce.
The Date of Value Problem: Why Timing Changes What the Marital Home Is Worth

Two appraisers can look at the same marital home and reach different numbers, both correct. The reason is usually the date of value. Set it on one day and the house is worth one figure. Set it on another, and the number moves. In a divorce, that single choice can shift a settlement by thousands, which is why the date of value in a divorce appraisal deserves attention early, not after the report lands.

By the end of this article, you’ll know:

  • What the date of value is and why it changes the number
  • Which date Illinois courts generally use for the marital home
  • When a retrospective appraisal is the right tool

What the Date of Value Means in a Divorce Appraisal

The date of value, also called the effective date, is the exact day an appraiser’s opinion of value applies to. It is not always the day the appraiser visits the home. The appraiser can measure market value as of today, or as of a date in the past, and the report states which one it used.

This matters because markets move. Interest rates shift, inventory tightens, a neighborhood heats up or cools off. So a home worth one figure in the spring may carry a different figure by the fall. The Uniform Standards of Professional Appraisal Practice treat the effective date as a core part of the assignment, and a credible report ties every comparable sale back to it.

Which Date Illinois Courts Use

Illinois gives the court discretion here, but there is a strong default. Under 750 ILCS 5/503, marital property is generally valued as of the date of trial, or the date the marriage is dissolved, using a fair market value standard. The court can pick another date if the parties agree or if the facts call for it.

One rule trips people up. The separation date is usually not the valuation date. Value tends to keep accruing until the case is decided, so growth in the home’s worth between separation and trial often stays in the marital estate. Courts also avoid using different dates for different assets, which keeps the division consistent.

When a Retrospective Appraisal Comes In

Sometimes the question is not what the home is worth now, but what it was worth years ago. That is a retrospective appraisal. The appraiser sets a past effective date, such as the date of marriage, and reconstructs the market using sales that closed around that time.

This is often how a spouse traces separate property. If one party owned the home before the marriage, the value at the date of marriage helps separate premarital equity from the appreciation that built up during it. CPAs lean on the same figure to keep the tax and division math straight. So the choice of date is not a technicality. It decides what counts as marital in the first place.

How the Date Moves the Number

Picture a home that a couple bought near a market peak, then watched cool as rates climbed. An appraisal dated at filing might land higher than one dated at trial a year later. Neither is wrong. They answer different questions.

That gap is exactly why the effective date can become a bargaining point. A spouse hoping for a lower buyout may prefer a softer date, while the other pushes for the stronger one. The appraiser does not pick sides. But the attorney who sets the date early controls the terms of the fight instead of reacting to a number that already exists.

Set the Date Before You Order the Appraisal

Decide the effective date first, then order the work to match. If the case may need both a current value and a past one, say so up front, because a retrospective analysis takes different data. Confirm the appraiser can support the chosen date with real sales from that period, and can explain the choice if the report is challenged. Timing is a decision, so make it on purpose.

Need the Value Fixed to the Right Date?

PahRoo prepares both current and retrospective divorce appraisals, tied to the effective date your case needs and ready to defend.

Ask About a Date-of-Value Appraisal

Frequently Asked Questions

What is the date of value in a divorce appraisal?

The date of value, also called the effective date, is the specific day an appraiser’s opinion of value applies to. It fixes the moment the home’s market value is measured. Two appraisals of the same house with different effective dates can reach different numbers, because the market moves over time.

Does a home get appraised at the date of separation or the date of trial?

In Illinois, marital property is generally valued as of the date of trial or the date the marriage is dissolved, not the date of separation. Under 750 ILCS 5/503, the court has discretion to use the trial date or another date the parties agree to, so the separation date is usually not the valuation date.

What is a retrospective appraisal?

A retrospective appraisal estimates what a property was worth on a specific past date, such as the date of marriage. The appraiser reconstructs the market as of that date using sales that closed around then. It is common when tracing how much of a home’s value is separate versus marital property.

Can the chosen date change the settlement?

Yes. Because home values shift over time, the effective date can change the appraised value, and that changes the equity each spouse divides. In a fast-moving market, the gap between two candidate dates can be large enough to matter in a negotiation.

Can you appraise a home for a past date?

Yes. A licensed appraiser can prepare a retrospective appraisal with a past effective date, relying on comparable sales from that period rather than today’s market. The report states the effective date clearly, so everyone knows what point in time the value reflects.

Need an Independent Divorce Appraisal?

PahRoo Appraisal & Consultancy prepares current and retrospective valuations across Cook County and the wider Chicago area. For background on how we support attorneys and their clients, see our overview of appraisals in divorce proceedings and our residential appraisal services, or contact us to set the right effective date for your case.

Divorce home appraisal of a marital home, with keys and a property settlement document.
Why a Divorce Home Appraisal Is Not the Same as a Realtor’s Price Opinion

When a marriage ends, the house is usually the largest asset on the table. Both spouses want a number they can trust, and many start by asking a real estate agent what the home would list for. That figure has a job to do. A divorce home appraisal does a different job, and courts treat the two very differently.

By the end of this article, you’ll know:

  • What separates a divorce home appraisal from a broker price opinion
  • Why courts want an independent, standards-based value
  • When your situation actually calls for a formal appraisal

What a Divorce Home Appraisal Actually Measures

A divorce home appraisal is an independent opinion of a property’s market value, prepared by a licensed or certified appraiser. The appraiser inspects the home, studies comparable sales, and documents how each conclusion was reached. The report follows the Uniform Standards of Professional Appraisal Practice, or USPAP, the recognized rulebook for appraisers in the United States.

The point of the report is defensibility. A judge, an opposing attorney, or a spouse can question the number, and the appraiser has to stand behind it. So the work is built for scrutiny, not for a quick answer. PahRoo prepares these reports as part of its residential appraisal services, with the divorce context in mind from the first phone call.

Where a Broker Price Opinion Fits, and Where It Falls Short

A broker price opinion, or BPO, is an agent’s estimate of what a home could sell for. A comparative market analysis, the close cousin most sellers see, does much the same thing. Both are useful tools. Agents produce them quickly, often at no charge, to help set a listing price or win the listing.

The catch is the purpose behind the number. A pricing tool is built to move a house, so it leans toward what will attract buyers or reassure the seller. It also skips the formal standards an appraisal must follow. A trusted agent’s read on the market has real value early in a case. It just was not built to survive an opposing expert or a skeptical judge. So if you rest a contested value on a listing estimate, you hand the other side an easy target.

Appraisal vs. Broker Price Opinion at a Glance

  Divorce Home Appraisal Broker Price Opinion
Prepared by Licensed or certified appraiser Real estate agent or broker
Built for A defensible opinion of market value Setting or winning a listing
Follows USPAP Yes No
Holds up in court Designed to, and the appraiser can testify Easy for opposing counsel to challenge
Cost and speed Fee-based, takes longer to produce Often free and fast
Best use in divorce Contested value, buyout, refinance, trial Early ballpark when both sides agree

Why Courts Lean on the Appraisal

Illinois divides marital property by equitable distribution. Under 750 ILCS 5/503, the court splits property in “just proportions,” which does not always mean a straight 50/50 cut. The statute also directs judges to make specific findings on the value of each asset.

A court cannot make those findings on a guess. It needs a value that was developed under recognized methods and can survive cross-examination. An appraisal is designed to do that. A price opinion, however helpful for listing, was never meant to carry that weight.

When Your Case Actually Needs One

Not every separation calls for a formal appraisal. If both spouses agree on the value and plan to sell, an agent’s pricing may be enough to get moving. The appraisal earns its cost when the number is contested or the stakes are high.

The most common trigger is a buyout, where one spouse keeps the home and pays the other for their share. You also want a defensible value when the parties disagree on price, when a lender requires it for a refinance, or when the case is heading toward trial. In each of those, a soft number invites a challenge down the road.

Start With a Value That Holds Up

If the house sits at the center of your settlement, begin with a number built to withstand pressure. An independent appraisal costs more than a quick estimate and takes longer to produce. It also removes a common source of delay, because neither side can easily wave it away. Ask early whether your situation needs one, then order it from an appraiser who will explain and defend the work.

Need a Value Both Sides Can Trust?

PahRoo prepares court-ready, USPAP-compliant appraisals for divorcing homeowners and their attorneys. Get one number that stands up to scrutiny.

Request Your Appraisal

Frequently Asked Questions

What is a divorce home appraisal?

A divorce home appraisal is an independent, USPAP-compliant opinion of a marital home’s market value, prepared by a licensed or certified appraiser to support property division. It documents the comparable sales and reasoning behind the value, so it can hold up if a spouse, attorney, or judge questions it.

Is a realtor’s price opinion accepted in a divorce?

A realtor’s price opinion can inform early discussions, but courts generally prefer a formal appraisal when the value is contested. A price opinion is built to set a listing price, not to meet appraisal standards, so it is easier to challenge in a property division dispute.

Who should appraise a house in a divorce?

A licensed or certified real estate appraiser should value the home, ideally one experienced with divorce work and willing to testify if needed. Some couples save time and money by jointly retaining one neutral appraiser instead of each hiring their own.

How much does a divorce home appraisal cost?

The cost depends on the property type, its complexity, and whether court testimony may be required. A standard single-family home runs less than a luxury or multi-unit property that needs deeper analysis. PahRoo quotes each assignment individually, so you can request an estimate for your specific home.

Can you use a Zillow estimate in a divorce?

A Zillow estimate is an automated model, not an appraisal, and it cannot account for a specific home’s condition or recent updates. Courts do not treat it as reliable evidence of value, so it should not anchor a settlement. An appraisal gives a defensible figure instead.

Need an Independent Divorce Appraisal?

PahRoo Appraisal & Consultancy has valued homes across Cook County and the wider Chicago area since 1999. Our team prepares reports for attorneys, homeowners, and other professionals who need a value that stands up. To learn more, read our overview of appraisals in divorce proceedings, or contact us to talk through your situation.

Family lawyer reviewing divorce property documents in Illinois
Disputed Property Value in Illinois Divorce: 3 Documents


The two numbers are $640,000 and $515,000, and each spouse is sure of theirs. Disputed property value in an Illinois divorce usually starts this way. One side quotes a listing site, the other a neighbor’s sale. Before anyone pays for an expert, three records already exist. They will tell you which number is closer, and whether either one is worth defending.

By the end of this article, you’ll know:

  • Which three records to request, where each one lives in Cook County, and what each can and cannot prove
  • The tells inside each record that point to a soft number on the other side
  • When the file needs an independent appraisal, and what a broker should hand over in the meantime

Why Disputed Property Value Gets Settled on Paper First

Illinois divides marital property in just proportions, not an automatic half. That comes from 750 ILCS 5/503, and the court applies it asset by asset. The house is often the largest line on the marital balance sheet, and the court has to land on a value before it can divide anything.

When spouses ask the judge to decide property, each one completes a financial affidavit with supporting documents, as Illinois Legal Aid Online explains. The value on that affidavit has to come from somewhere. Your job, early, is to find out where.

Three records answer that question at almost no cost. Each was created for a different purpose, so none is a value opinion you can take to trial. But together they show you the shape of the dispute. And they do it before you spend a dollar on an independent divorce appraisal.

Record One: The Assessor’s Property Record

Start with the Cook County Assessor. The office values about 1.8 million parcels, and it says plainly that it does not value them one at a time. It uses mass appraisal, a regression model that relates your client’s house to the sales around it. One-third of the county gets reassessed each year on a three-year cycle. The Board of Review then finalizes values after appeals.

Pull the property detail page by PIN. It shows the estimated market value, the assessed value, the property class, and the year of the next reassessment. It also shows an exemption history and a characteristics table: square footage, baths, basement, garage, age. Read the market value line, not the assessed line. For most homes the assessed figure is a fraction of the market estimate. A spouse who quotes it as the value misread the page.

A value reduced at the Board of Review means someone argued, in writing, that the house is worth less. If that same spouse now claims it is worth more, you have the exhibit. A table showing three baths and a full basement when the house has two and a crawl space means the record is wrong. An unpermitted addition or a finished lower level can push the gap the other way. Two homeowner exemptions across two properties is a separate problem your client should hear about now.

Consider a hypothetical Evanston bungalow. The Assessor’s estimated market value reads $480,000. One spouse claims $640,000 and the other claims $515,000. The record proves neither number, but it puts the burden where it belongs. The $640,000 figure sits $160,000 above a model built on nearby sales, so that spouse owes you a report.

Record Two: Any Prior Appraisal on the Property

If either spouse bought, refinanced, or opened a home equity line during the marriage, a lender appraisal exists. Ask for it in discovery, and ask the lender if the spouse cannot find it. It answers a lender’s question as of a lender’s date, so the value itself is stale. The rest of the report is not.

A prior appraisal gives you a measured square footage, a sketch, and interior photos. It also gives a condition rating, the updates the owner claimed at the time, and the comparable sales an independent appraiser chose back then. If one spouse says the kitchen was gutted in 2019, the 2021 refinance photos settle it. Under USPAP, the standard every licensed appraiser works to, the report must state its effective date and intended use. Hold it to that date. Then it is a record of what the house was, not an argument about what it is worth today. Our piece on the date of value in a divorce appraisal explains why that distinction moves settlements.

Three things deserve a second look. A value that lands exactly at the number the loan needed. A property described differently than it stands today, which can mean work done since, or work never done. And a report dated after a deed changed hands, because a quitclaim transfer mid-case changes which date the court cares about. When I get a prior appraisal in a new assignment, I do not adopt its value. I use it to check what changed and to confirm the square footage.

Record Three: Broker Price Opinions and Market Analyses

A broker price opinion, or the comparative market analysis most sellers see, is an agent’s estimate of what a home could list or sell for. In a divorce file they show which comparables each side leans on and whether a range is a listing range or a value. A pricing tool built to win a listing will not survive an opposing expert, which is why a divorce home appraisal and a price opinion land so differently in front of a judge.

If you are the broker being asked for that CMA, here is what makes yours useful instead of a liability. Date it. State on the first page that it is a pricing analysis and not an appraisal. List every comparable with its closed date, closed price, and any seller concessions you know about. Say whether you walked the interior or worked from photos. Then keep your file. In a contested case you may get a subpoena for it, and a range you stretched for one spouse is a bad afternoon under oath. A CMA that shows its work gets read alongside the appraisal. One that does not gets read against you.

For counsel, the practical move is to request both sides’ opinions at once and lay the comparables next to each other. If both agents used the same four sales and landed $90,000 apart, the difference is in the adjustments. That is an appraisal question. If they used different sales, someone is shopping for comps.

When the Paper Runs Out and the File Needs an Appraisal

The three records frame the dispute. They rarely end it. Order an independent appraisal when the gap survives the paper. Order one when the equity is large enough that a five percent error costs real money, or when a buyout or refinance depends on the number. The same goes for an unusual property, a rental unit, or a case likely to reach a hearing. A retrospective date, such as the date of marriage for a premarital equity claim, is its own reason. None of the records will give you one.

Online estimates do not fill the gap. In April 2026 the Appraisal Standards Board adopted Advisory Opinion 41 on automated valuation models, regression software, and generative AI in appraisal work. An appraiser who uses those tools still owns the result and has to support it. A spouse citing a website estimate has none of that behind the number.

Cook County adds a local wrinkle. A block in Oak Park, a two-flat in Hyde Park, and a bungalow in Norwood Park each sit in a market that moves on its own schedule. A report built for Cook County reads those markets and supports each adjustment. Our article on what makes an appraisal defensible on the witness stand goes through that test in detail.

Pull the Records Before the First Settlement Conference

The sequence is simple. Pull the Assessor’s property record on day one; it costs nothing and needs only a PIN. Put prior appraisals and any broker opinions in your first document request. Ask the lender directly if the spouse comes up empty. Lay the three records side by side and see where the gap lives: the square footage, the condition, the comparables, or the date. Then decide whether an appraisal is needed, and if so, agree the effective date with opposing counsel before either side orders one.

Two Numbers on the Table and No Way to Choose?

PahRoo prepares independent divorce appraisals for contested marital property across Cook County and the Chicago area, built to be disclosed, deposed, and defended.

Order an Independent Appraisal

Frequently Asked Questions

What documents should a family lawyer request when property value is disputed?

Request the county assessor’s property record, any prior purchase, refinance, or home equity appraisal, and any broker price opinion or comparative market analysis either spouse relied on. Together they show where the two numbers came from and whether an independent appraisal is needed.

Can a Cook County assessment be used as market value in a divorce?

Not as a value opinion. The Cook County Assessor values property by mass appraisal for tax purposes and does not inspect the individual home. The estimated market value is useful background, and the characteristics table and appeal history can expose errors, but it should not replace an appraisal when value is contested.

Is a broker price opinion the same as an appraisal?

No. A broker price opinion or comparative market analysis is a pricing tool prepared by a real estate agent, usually to set a listing price. An appraisal is an independent opinion of value developed under USPAP by a licensed or certified appraiser, with a stated effective date, intended use, and supported adjustments.

Can a prior refinance appraisal set the value in a divorce?

Rarely. The value in a refinance appraisal applies to the lender’s effective date, which is usually well before the divorce. The report is still valuable for its measured square footage, sketch, photos, condition notes, and comparable sales, which document what the house was on that date.

When should a divorce attorney order an independent appraisal?

When the gap between the spouses survives the three records, when the equity is large, when a buyout or refinance depends on the number, when the property is unusual or includes a rental unit, when a past effective date is needed, or when the case is likely to reach a hearing.

Appraisal Support for Contested Marital Property in Cook County

The records above are where PahRoo starts too. Since 1999 the firm has prepared divorce, estate, and litigation appraisals across Cook County and the wider Chicago area, along with Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, signs every report and is available for deposition and testimony. See our residential appraisal services, or contact us with the PIN and the records you already have.

NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712