Tag: Illinois divorce

Request a quote

Our blog

Latest news
& events

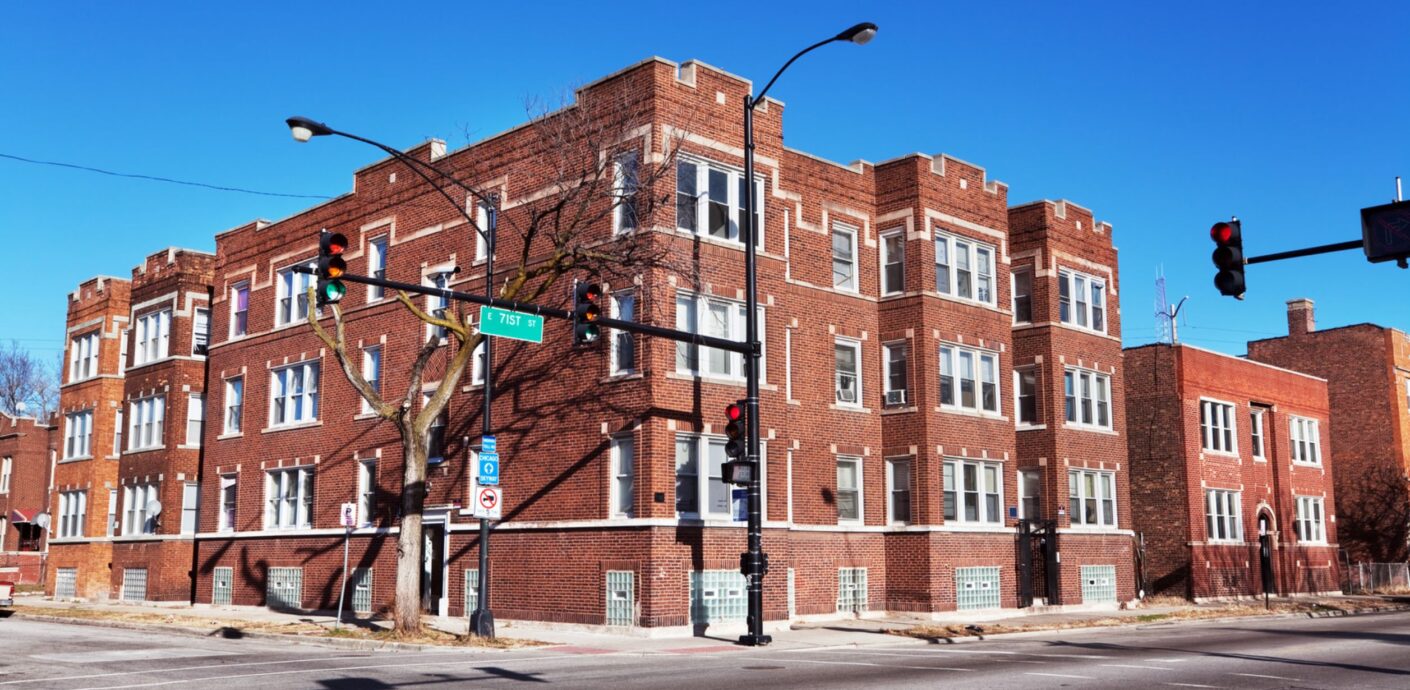
Chicago six-flat apartment building valued in a commercial real estate divorce appraisal
How Commercial Property Gets Appraised in a Divorce

A divorce with a six-flat, a strip center, or an office condo on the balance sheet needs more than a house appraisal. A commercial real estate divorce appraisal values the building the way investors do, by what it earns and what buyers pay for that income. For divorce attorneys, that changes what you ask for at engagement and what you can defend later.

By the end of this article, you’ll know:

  • Why commercial property needs a different appraisal than the marital home
  • How the valuation date, the leases, and the business affect the number
  • What CPAs should line up for the tax side of the split

Why a Commercial Real Estate Divorce Appraisal Works Differently

Most marital homes get valued mainly from recent sales of similar houses. A rented building is different, because the rent is a big part of what a buyer is paying for.

So the appraiser looks at more than sales. Federal banking guidelines sum up the USPAP rule well. According to the Interagency Appraisal and Evaluation Guidelines, an appraisal must include each approach to value that applies, whether sales comparison, income, or cost. It also has to explain any approach it leaves out. Our guide to the three approaches to value covers how each one works.

In a leased building, that usually puts real weight on the income. Our article on the income approach for commercial property shows how rent becomes a value.

Illinois also sets the standard the report has to meet. Under 750 ILCS 5/503, the court uses a fair market value standard. It also has to make specific factual findings on values. So the report should support a number a judge can actually write into those findings.

Settle the Valuation Date Before the Appraiser Starts

Illinois gives the court room on timing. Under Section 503, the valuation date is the date of trial or another date the parties agree to or the court orders. That flexibility matters more for a building than for a house.

Commercial values move with leases and capitalization rates. The federal guidelines list changes in cap rates and lease terms among the things that can make an older appraisal stale. A tenant leaving, or a lease renewing at a new rent, can shift the number between filing and trial.

So agree on the date, or ask the court to set it, before the work begins. If that date has already passed, the assignment becomes a retrospective appraisal as of the earlier date. Our piece on the date of value problem in divorce explains why timing moves value, and our explainer on cap rates shows how small rate changes add up.

Other states handle valuation dates their own way. If the building sits in another market we serve, our Dallas, Philadelphia, Phoenix, and Naples teams appraise under that state’s rules. In Cook County, our Chicago appraisal team handles the work.

Leases Can Raise or Lower What the Building Is Worth

A building with tenants comes with its leases. A long lease at below-market rent can hold value down for years. An above-market lease with a strong tenant can do the opposite, at least until it ends.

Lenders already watch for this. The federal guidelines require lending appraisals to account for partially leased buildings and non-market lease terms. A divorce file raises the same facts, so the report should compare each lease with market rent and show the effect.

Also watch for leases between family entities. If the couple’s own company rents the space, the rent may not match the market. The appraiser can report what market rent would be, and counsel can decide what that means for the case. We cover that setup in more detail in our article on the family business’s real estate.

Keep the Building Separate From the Business

A building and the business inside it are two different assets. The federal guidelines draw the same line for lenders. They say going concern value and value in use may not stand in for market value, and any such opinion has to be identified separately.

That matters when one spouse runs a restaurant, clinic, or shop in a building the couple owns. The real estate appraisal should value the land and building only. Any business value belongs with a business valuator, and the two reports should not count the same dollars twice. Our conversation on going concern appraisal with Bruce Jones, MAI covers how appraisers think about that split.

Ownership through an LLC raises a related point. PahRoo values the real estate itself. What a spouse’s share of that LLC is worth can be a separate question, so confirm early who is answering it.

For CPAs, the Same Value Can Carry Different Tax Results

Federal tax rules usually let a building pass between divorcing spouses without immediate gain or loss. Under Treasury Regulation 1.1041-1T, that applies to transfers incident to divorce. The spouse who receives the building also takes the other spouse’s adjusted basis.

So two buildings with the same appraised value may not be equal after tax. Consider a hypothetical. Building A and Building B each appraise at $2,000,000. Building A has an adjusted basis of $600,000, and Building B has $1,800,000. On a later sale at that price, Building A would show $1,400,000 of gain, while Building B would show $200,000.

Illinois courts can weigh this too, since Section 503 lists the tax consequences of the division as a factor. A few steps help. First, ask the transferring spouse for basis and holding period records, which the regulation says the transferor must supply. Second, match the appraisal’s effective date to the business valuation date when both assets are in play. Third, get the appraiser the rent roll, the leases, and three years of operating statements early.

What to Put in the Engagement Letter

Start with the intended use and the intended users. The federal guidelines note that an engagement letter identifies both, as USPAP defines them, and that sets who can rely on the report. Then state the valuation date, the property interest, and whether you expect testimony. Illinois courts can also bring in their own financial experts under Section 503, and counsel may examine a professional the court designates as its witness. A tight engagement letter gives you a report that is easier to defend if the other side attacks its scope.

Dividing a Commercial Building in the Divorce?

PahRoo appraises the real estate on its own, with the valuation date, the leases, and the property interest spelled out. Tell us about the building and the date the case needs.

Order a Commercial Appraisal

Frequently Asked Questions

How is commercial property appraised in a divorce?

The appraiser considers the sales comparison, income, and cost approaches and uses each one that applies. For a leased building, the rent and the leases usually drive much of the analysis.

What valuation date does an Illinois divorce use?

Under 750 ILCS 5/503, it is the date of trial or another date the parties agree to or the court orders. Settle the date before the appraisal starts.

Do tenant leases change a building’s value in a divorce?

Yes. A lease above or below market rent can raise or lower value, so the report should compare each lease with market rent.

Does a commercial real estate appraisal include the business?

No. It values the land and building. A business operating there, or a spouse’s share of an LLC that owns the building, is a separate valuation question.

Is transferring a building between divorcing spouses taxable?

Generally not at the time of transfer. Under Treasury Regulation 1.1041-1T, the receiving spouse takes the other spouse’s adjusted basis, so the gain can show up on a later sale. A tax advisor should confirm the details.

Commercial Appraisals for Family Law Cases

PahRoo Appraisal & Consultancy appraises commercial and investment property for family law attorneys and CPAs in Chicago and Cook County, Dallas, Philadelphia, Phoenix, and Naples. Michael Hobbs, MAI, SRA, signs our Illinois reports. See our commercial appraisal services to learn how we work.
Owner-occupied family business real estate being valued in a divorce
The Family Business’s Real Estate and What Gets Appraised in a Divorce

When a divorcing client owns a business, the building often gets lost in the business valuation. Maybe the company owns it outright. Maybe a spouse holds it in a separate LLC and charges rent. Either way, family business real estate usually needs its own appraisal, and how that appraisal fits with your valuation decides whether the numbers hold together.

By the end of this article, you’ll know:

  • Which real estate questions the appraiser answers, and which stay with you
  • How related-party rent can count the building twice
  • What to settle with counsel before anyone sets a value

Family Business Real Estate Is Its Own Asset

A business and the building it occupies are different things to value. The business earns its money from customers, staff, and know-how. The building earns its value from location, size, condition, and the rent it could command.

So an appraiser values the real estate, and a business valuator values the company. In practice, the two reports have to speak to each other. If they don’t, one asset can show up twice, or the building can vanish into a goodwill number nobody can test.

The appraiser’s job here is narrow on purpose. It covers the market value of the land and building. The enterprise, its equipment, and its customer list belong in the business valuation. When a property runs as a going concern, like a restaurant or a car wash, the appraiser separates the real estate from the business. Our conversation on going concern appraisal with Bruce Jones, MAI walks through how that split works, and our piece on special use property covers buildings with few comparable sales.

Who Holds Title Changes the Work

Start with the deed. Ownership usually falls into one of three patterns, and each one asks something different of your model.

First, the operating company may own the building. Then the real estate sits on the company’s balance sheet, often at depreciated cost. That book figure can be far from market value, so an asset-based method needs an appraised number in its place.

Second, one or both spouses may own the building personally or through a separate LLC. The company then pays rent, or sometimes pays none. Now there are two assets to account for, the business and the real estate holding.

Third, the company may rent from an unrelated landlord. In that case there is usually no family real estate to appraise at all. Still, the lease terms affect the business’s costs.

Whether any of these interests is marital, separate, or mixed is a legal question for counsel and the court. Under 750 ILCS 5/503, property acquired during the marriage is presumed marital. But the appraisal stays the same either way. It reports what the property is worth, and the attorneys argue what that value means.

Related-Party Rent Is Where Values Get Counted Twice

This is the part that matters most for your normalization work. When spouses own the building and the business pays them rent, that rent is a related-party number. It may not match the market.

Consider a hypothetical. A family distribution company uses a warehouse owned by the spouses’ LLC and pays no rent. The appraiser concludes the market rent is $60,000 a year. If the business valuation never deducts that rent, the company’s earnings look $60,000 richer than they would under a market lease. That extra income then gets capitalized into business value.

Meanwhile, the appraisal values the warehouse using that same $60,000 of income. At a hypothetical 8% capitalization rate, the building comes in near $750,000. Now the same stream of rent props up two values. The fix is to adjust the business’s rent expense to the market rent from the appraisal, so each asset carries only its own income.

The reverse happens too. Rent can rise before a divorce, which drains reported business income into the real estate entity. Either way, the market rent figure from the appraisal gives you a tested benchmark. For how appraisers build that income figure, see our guide to the income approach for commercial property.

Fee Simple or Leased Fee Should Be Decided Up Front

If a lease exists between the business and the property owner, the appraiser has to know which interest to value. A fee simple value assumes the building is free of that lease and could rent at market terms. A leased fee value reflects the owner’s position subject to the actual lease, including its rent and remaining term.

When the contract rent matches market rent, the two values tend to land close together. When a related-party lease sits well above or below market, they can split apart. A reading on leased fee valuation from Illinois State University lays out how contract rent and market rent drive that difference.

Because the lease was written inside the family, it may not survive the divorce. So the right interest to appraise is a scoping call to settle with counsel and the appraiser before any work begins. Write it into the engagement letter.

For Divorce Attorneys, Settle the Scope Before Anyone Values Anything

Attorneys can head off most of these problems early. A few steps make the experts’ work fit together.

Pull the deed and the entity records first. Who holds title, and through what entity, tells everyone which pattern you have. Then request every lease and the rent actually paid for several years, including any recent changes.

Next, align the valuation date. Section 503(k) sets the date of trial unless the parties agree on another date or the court orders one. The appraiser and the business valuator should work to the same date. Our article on the date of value in a divorce appraisal explains why mismatched dates cause trouble.

Finally, have both experts share their real estate figures before either report is final. That includes the market value, the market rent, and the interest appraised. Section 503(l) also lets the court seek advice from financial experts or other professionals, so a clean, consistent record helps if the court brings in its own.

Get the Building Valued Before the Business Number Is Set

If your engagement involves a business that owns or occupies real estate, ask for the appraisal early. You need the market rent to normalize earnings and the market value to complete the balance sheet. Waiting until the business valuation is done invites rework, or worse, competing appraisals in divorce court that disagree on facts nobody checked.

Is the Building Hiding Inside the Business Value?

PahRoo appraises the real estate on its own, with a market rent figure your business valuation can use. Tell us about the property and who holds title.

Value the Building Separately

Frequently Asked Questions

Is the family business’s building marital property?

That is a legal question for counsel and the court. Illinois presumes property acquired during the marriage is marital, but title, timing, and contributions all matter. The appraisal reports the property’s value either way.

How is company real estate valued in a divorce?

An appraiser sets the market value of the land and building, usually relying on comparable sales and an income analysis based on market rent. Illinois courts value divided assets at fair market value.

Does the business or the building get appraised?

Usually both, by different experts. A real estate appraiser values the property, and a business valuator values the company. Their reports should share the same date and the same market rent figure.

Who owns the property a business uses?

Check the deed. The company may own it, the spouses may hold it personally or through a separate LLC, or an unrelated landlord may own it. Each pattern changes what needs appraising.

Can the building be counted twice in a divorce?

Yes. If the business pays no rent or below-market rent to the spouses, its earnings look higher and the building’s income can inflate the business value too. Adjusting rent to market avoids that.

Real Estate Valuation That Fits the Financial Picture

PahRoo Appraisal & Consultancy appraises commercial and owner-occupied property for CPAs and family law attorneys across Cook County and the Chicago area. Michael Hobbs, MAI, signs our Illinois reports and is available to testify on them. See our commercial appraisal services, our overview of appraisals in divorce proceedings, and our Chicago appraisal coverage.

NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712