Author: Michael Hobbs

Request a quote

Our blog

Latest news
& events

Suburban neighborhood with red HOA risk sign, representing potential impact of homeowners associations on property value.
Can Your HOA Kill Property Value? 5 Things Every Homeowner Must Know

Your home might be your biggest investment — but what if the HOA is quietly killing its value?

Whether it’s aggressive rules, financial mismanagement, or lawsuits, some HOAs can seriously damage your resale price. Here’s what you need to know before it’s too late.

The Hidden Power of Your HOA

Most homeowners don’t realize how much influence an HOA has over their home’s market appeal. From enforcing neighborhood standards to managing shared spaces, HOA actions (or inactions) can shape how buyers and appraisers view your property.

Real Examples of HOAs Hurting Property Value

  • Ongoing lawsuits can scare away lenders and buyers
  • Strict rental or pet rules shrink your buyer pool
  • Deferred maintenance in common areas pulls down condition ratings for every unit

These issues don’t just affect perceptions. They can directly influence your home’s appraised value.

Appraiser Perspective: What We Look For

As appraisers, we consider more than just your home’s interior. If the HOA is underfunded, facing litigation, or showing signs of poor management, it can reduce demand and reduce value.

“A struggling HOA doesn’t just impact one unit. It creates a ripple effect that appraisers and buyers both notice.”

What You Can Do as a Homeowner

  • Attend HOA meetings and ask questions
  • Request and review financial statements before buying
  • Watch for large planned assessments or legal red flags
  • Talk to neighbors about their experience with the HOA

When to Call an Appraiser

If you’re unsure how your HOA might be impacting your home’s value, a professional appraisal can give you clarity. Pre-listing appraisals can uncover issues before they derail a sale.

Need help? We’ve got your back.

At PahRoo Appraisal & Consultancy, we’ve appraised thousands of properties in HOA-managed communities. We know what to look for and how to make sure you’re not blindsided when it matters most.

Get in touch with us today for a consultation or pre-listing appraisal and protect your home’s value.

Want more insights into how property value is shaped by hidden factors like HOAs, zoning, and market trends?

Subscribe to our podcast, Appraisers on Purpose
Or visit our YouTube channel @PahRooZings

We regularly feature real estate experts, appraisers, and professionals shari3ng actionable advice to help you protect your investment and make informed property decisions.


Michael Hobbs is the President of PahRoo Appraisal & Consultancy LLC, a leading Chicago-based firm providing residential and commercial real estate valuation services for over 25 years.


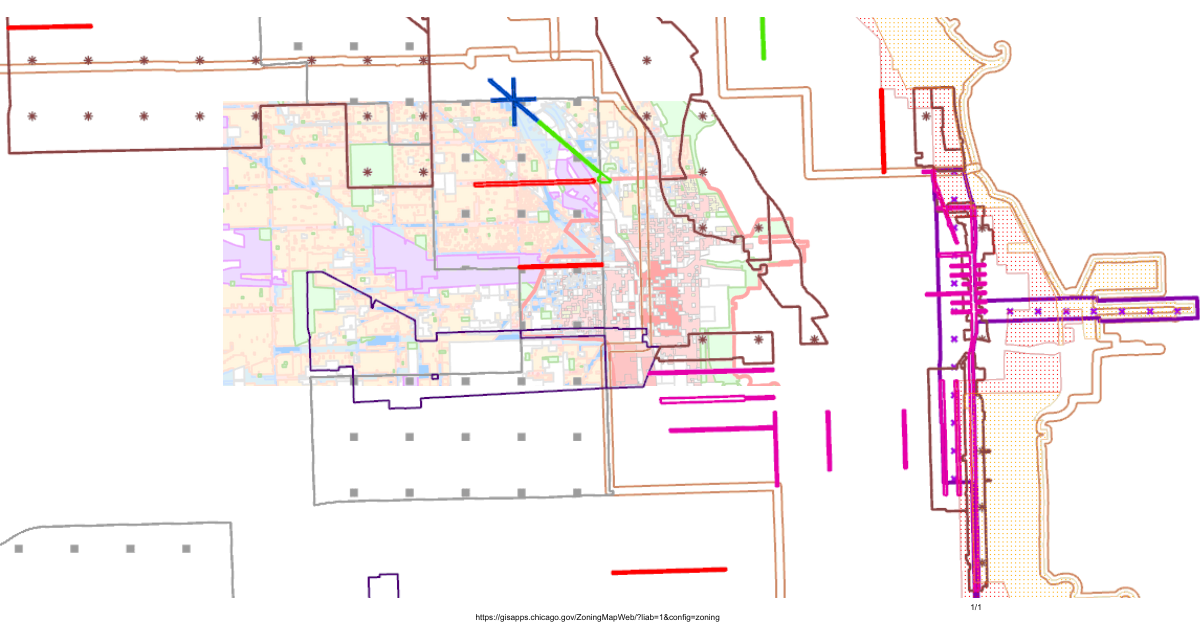
Zoning map overlay demonstrating impact on property values in Chicago
Zoning: The Most Boring Topic That Can Change Everything

You might think zoning is just lines on a map, but it’s the invisible lever that drives hundreds of thousands (even millions) in property value.

Skip this topic, and you may underestimate or overprice assets by massive margins.

Real Stories: Zoning = Money
1. The Big Boost: Wyndham Vale, Australia

In Wyndham Vale, a rural-to-residential rezoning added AU$280 million in value to one 897-acre site. That’s nearly US$190 million in upside—all from a zoning change.

Source: Reserve Bank of Australia

What this means for you: Even a small parcel in an unassuming Chicago suburb could hold a hidden $200K–$500K swing depending on zoning potential.

2. Duplex Gold Mine: Arlington, VA

Arlington allowed duplexes in single-family zones. One teardown bought for $570K was split into two units projected to sell at $1.2M each.

Value unlocked: ~$630K increase from zoning shift alone.

Source: Washington Post

3. Housing Price Shock: Major Metros

Studies show zoning restrictions inflated home prices in Sydney & Melbourne by up to 69%. That’s $150K–$400K baked into every home due to policy—not property.

Source: Cato Institute

Why This Matters in 2025
  • Chicago & Cook County: Exploring transit-oriented and middle-housing zoning reform.
  • Phoenix (AZ), Tampa (FL), Dallas (TX): Growth markets experimenting with higher density.

Zoning changes are active—not theoretical. A rezoning today can reshape value tomorrow.

What Appraisers & Realtors Should Do
Role What to Watch Why It Matters
Appraisers Policy meetings, zoning board agendas, draft maps A variance can 10x a site’s highest and best use
Realtors/Investors Look for underutilized properties near zoning reform zones Buy before zoning shifts hit public comps
General Audience Stay informed on local planning efforts Even your backyard might be worth more than you think
Final Thought: Making the Invisible Visible

Zoning appears dull, but it’s the hidden force that can convert hayfields into neighborhoods and C-grade properties into six-figure jackpots. Whether you’re valuing or advising, ignore zoning at your peril.


Evaluating a property near a growth zone? Let’s uncover hidden upside together.

Contact us today to make smarter, zoning-savvy real estate decisions.

Home interior showing durable upgrades that boost value in 2025
The 5 Upgrades That Actually Boost Property Value in 2025
Thinking about renovations?

The key isn’t in flashy finishes, it’s in upgrades that add real value. Appraisers and buyers alike now prioritize practical, lasting improvements that impact usability and efficiency. In this blog, we uncover the 5 upgrades that boost home value in 2025, from energy-saving systems to functional layouts that support modern living

Will this upgrade actually raise my property value?

In 2025, the market is smarter and more cautious than ever. Buyers want function, not flash. Appraisers? We look past the granite countertops to what truly counts.

What You Can Start Doing Today

You don’t need a massive budget to begin boosting your home’s value. Small, smart steps now can set you up for long-term gains.

1. Energy-Efficient Systems

What it is: Smart thermostats, solar panels, upgraded insulation, efficient HVAC

Why it adds value: Lower utility bills = long-term savings for buyers. Eco-conscious homes sell faster and often at a premium.

Pro Tip: Look for ENERGY STAR certifications when replacing systems.

2. Finished Lower Levels or ADUs

What it is: Finished basement, legal in-law suite, or detached guest house

Why it adds value: It increases usable (and rentable) square footage. Appraisers factor that in and so do investors.

Pro Tip: Ensure code compliance and proper permits to maximize appraisal value.

3. Updated Major Systems

What it is: New roof, plumbing, electric panel, foundation work

Why it adds value: These upgrades reduce buyer risk. No one wants a fixer-upper surprise post-closing.

Pro Tip: Keep records of installations and warranties to support appraisal documentation.

4. Functional Layout Improvements

What it is: Removing awkward walls, adding a second bath, improving bedroom access

Why it adds value: Flow matters more than fashion. A home that “lives better” appraises better — period.

Pro Tip: Consult an architect or designer for minor layout changes that have a major impact.

5. Curb Appeal That’s Built to Last

What it is: Quality siding, new windows, clean landscaping, modern doors

Why it adds value: Buyers form opinions before stepping inside. Exterior upgrades are both.

Pro Tip: Avoid over-personalized landscaping that might deter future buyers.

Why These Upgrades Work in 2025

In today’s market, both appraisers and buyers are looking for practical value. Aesthetics matter, but functionality and efficiency drive higher valuations. These five upgrades provide lasting returns financially and in livability.

What You Can Start Doing Today

You don’t need a massive budget to begin. Here’s how to take the first steps:

  • Schedule a home energy audit to identify savings opportunities.
  • Plan one project per quarter to upgrade essential systems.
  • Consult with a local appraiser to understand which improvements matter most in your neighborhood.
Final Thoughts

If you’re investing in home improvements, make them count. The best upgrades are the ones that blend smart functionality with lasting value. These five strategies are not just trends, they’re the future of homeownership in 2025.

Want tailored advice before your next renovation? Contact PahRoo Appraisal & Consultancy today for expert appraisal services, local market insights, and data-backed guidance tailored to your real estate goals.

Prefer to watch instead? Visit the PahRoo YouTube channel for videos on home appraisals, real estate insights, and expert renovation tips.

Side-by-side comparison of a Zestimate and professional home appraisal in Chicago, Dallas, and Philadelphia
Zestimate vs Appraisal: Which One Tells the Truth About Your Home’s Value?

Zillow might say your home is worth $625,000.
Your neighbor claims $700,000.
A professional appraiser? Comes in at $580,000.

So… who’s right?

Welcome to the world of Zestimates — algorithm-driven price estimates that can shape expectations and sometimes derail real estate deals. In 2025’s competitive market, relying solely on a Zestimate could cost you time, money, and opportunities.

The Problem with Zestimates

Zestimates use algorithms that pull public records, recent sales, and statistical modeling. While this sounds advanced, there are serious gaps:

  • No property-specific inspection — Zestimates don’t consider the condition of your home.
  • No awareness of unique location factors — Many assume nearby homes are identical, even when they’re on a busier street or zoned differently.
  • Assumes nearby homes are the same — Renovations, layout changes, or deferred maintenance often go unnoticed.

It’s like diagnosing a health issue using a generic online search — you might get a rough idea, but would you stake thousands of dollars on it?

What a Professional Appraisal Delivers That Zestimates Miss

Licensed appraisers provide a detailed, in-person, and market-specific assessment. We look at:

Property Condition: Roof age, HVAC status, flooring quality, and any repairs or upgrades.

Neighborhood Nuance: Position on the block, proximity to amenities, and local demand patterns.

Market Trends: Real-time pricing from the MLS and confirmed, closed sales.

Impact of Upgrades: Knowing which improvements add value versus those that are cosmetic.

Appraisals are backed by expertise, market insight, and regulatory standards — something an algorithm cannot match.

Why It Matters More Than Ever in 2025

Real estate in 2025 is anything but stable. Interest rates fluctuate, inventory is tight, and price sensitivity is higher than ever.

  • Sellers who overprice based on a Zestimate often sit on the market for weeks or take a price cut.
  • Buyers risk overpaying, and appraisals coming in low can kill deals.
  • Lenders must comply with regulatory standards,  they rely on licensed, certified valuations.

Remember: Zestimates are not legally defensible.
Appraisals are.

The Smart Next Step for Homeowners and Buyers

If you’re planning to sell, buy, or refinance, skip the guesswork:

  1. Get a pre-listing appraisal to price your home right the first time.
  2. Rely on real, local data not neighborhood rumors.
  3. Work with trusted professionals who know the market inside and out.

Work With Chicago, Dallas, and Philadelphia’s Trusted Appraisal Experts

At PahRoo Appraisal & Consultancy, we’ve helped thousands of clients in Chicago, Dallas, and Philadelphia get accurate, reliable home appraisals. Our team combines years of market expertise with thorough, property-specific assessments.

📞 Contact us today to discuss your property and book your professional appraisal.
Click here to get started →

Urban coastal neighborhood with modern homes and ocean view, representing factors considered in urban property appraisals
Rural vs. Urban Appraisals: Why They’re Completely Different Beasts

Rural vs Urban Appraisals: Why Being Local Makes All the Difference

When people hear the word appraisal, they often picture a clipboard, a calculator, and a real estate pro measuring square footage.

But did you know that a downtown condo and a farmhouse with a barn need totally different approaches?

That’s because urban and rural appraisals aren’t just about location, they’re about two completely different ways of thinking about value.

City Living: Urban Appraisals at a Glance

In the city, appraisers are spoiled (kind of). There’s a high volume of recent sales, meaning:

  • You can find comparable properties (comps) within a few blocks.
  • Square footage, number of bedrooms, and condo amenities drive value.
  • Adjustments are minimal—because everything’s similar.

Example:
Appraising a 2-bed condo in downtown Chicago?
You’ll likely find 5+ sales in the same building within the last year. Easy peasy.

Country Life: The Rural Appraisal Challenge

Now let’s head to the countryside.

Fewer homes. Fewer sales. More variables. Welcome to rural appraising.

  • You might have to go 10–20 miles to find comps.
  • You’re not just valuing the house—you’re valuing the land, outbuildings, septic systems, and even well access.
  • Adjustments get creative (and must be defensible).

Example:
You’re appraising a 10-acre ranch with a pole barn, private lake access, and a partially finished second structure.
Good luck finding a perfect comp. It doesn’t exist.
You’ll need to blend cost, market, and income approaches just to land on a value.

So What Actually Changes?
Factor Urban Appraisal Rural Appraisal
Comps Recent, nearby, similar units Sparse, distant, often imperfect
Value Drivers Square footage, updates, location Land size, ag use, outbuildings, utilities
Methodology Sales comparison w/ tight adjustments Sales + cost approach + HBU logic
Biggest Challenge Standing out in a crowded market Justifying value with limited data
Urban Appraisals = Precision | Rural Appraisals = Flexibility

Think of it this way:

  • Urban appraisal is like playing chess with clear rules and tight strategy.
  • Rural appraisal is like building a puzzle when some pieces are missing and you have to carve a few yourself.
It takes skill. And patience.
Appraisers Need Local Smarts

A rural property can’t be appraised by just any appraiser.

You want someone who:

  • Understands agricultural land and zoning
  • Knows the value of things like fencing, grain silos, or livestock buildings
  • Can defend comps that are 18 months old and 15 miles away

Urban appraisers, meanwhile, live and breathe neighborhoods, walkability, and micro-markets.

Both roles are skilled—but they’re very different games.

FAQ

Q: Why are there fewer comps in rural areas?
A: Simply put—fewer properties and fewer transactions. Some towns might only see a handful of sales a year.

Q: Can you use comps from other counties in rural appraisals?
A: Sometimes, yes. As long as the market dynamics are similar and it’s justified.

Whether you’re buying in the heart of the city or out where the nearest neighbor is a mile away, understanding how appraisals work can make all the difference in your negotiations and investment decisions. By knowing what factors matter most in both rural and urban settings, you’ll be better prepared for your next property transaction.

If you’re ready to explore your property’s true market value, connect with our Chicago, Dallas and Philadelphia appraisal experts today. You can also dive deeper into related topics like how zoning can change property value and what factors influence a home appraisal to strengthen your real estate knowledge.

Property Taxes, But Make It Easy

A Beginner-Friendly Guide on How Property Taxes Work, What They Fund, and How to Lower Your Bill

Confused about property taxes? Understanding how property taxes work is essential for homeowners and investors alike. In this guide, we explain how local governments calculate property taxes, where your tax dollars go, and actionable steps to lower your bill.

What Are Property Taxes?

Property owners pay annual taxes based on the assessed value of their real estate. These taxes help fund essential local services like schools, roads, and emergency responders. But despite how common they are, many homeowners don’t fully understand how they’re calculated or how to challenge them if something seems off.

How Are Property Taxes Calculated?

Understanding your property tax bill starts with two key components:

1. Assessed Property Value

This is the dollar amount your local tax assessor says your home is worth. It’s not always equal to market value and may be reassessed every few years. In some areas, only a percentage of the market value is taxed, this is called the assessment ratio.

2. Property Tax Rate (Millage Rate)

A mill equals $1 for every $1,000 of assessed value. If your home is assessed at $250,000 and your local tax rate is 20 mills, your property tax would be:
250 × 20 = $5,000 annually

Pro Tip: Check if your area has a property tax calculator on the county assessor’s website.

What Do Property Taxes Pay For?

Local governments invest your property taxes back into your community. Here’s where that money usually goes:

  • Public Schools

  • Police and Fire Departments

  • Roads and Transportation

  • Public Health and Sanitation

  • Libraries, Parks, and Recreation

In most counties, you can see a breakdown of how your tax dollars are allocated on your property tax statement or local government website.

Why Did My Property Taxes Go Up?

A common question homeowners ask is: “Why are my property taxes increasing every year?”

Here are a few reasons:

  • A reassessment increased your property’s value.

  • Voters approved new levies or bond measures.

  • Local government budget changes raised the tax rate.

Understanding these causes helps you figure out whether your tax increase is fair, or something you can dispute.

How to Lower Your Property Tax Bill

Feeling the pinch? Good news: you may be able to lower your property taxes by taking a few smart steps.

1. Review Your Property Tax Assessment

Assessors may make mistakes. Check for errors like:

  • Wrong square footage

  • Inaccurate number of rooms

  • Non-existent upgrades

2. Compare with Similar Homes

If your assessed value is way higher than similar homes nearby, gather comps to support your case.

3. File a Property Tax Appeal

You can file an appeal in most counties. Bring evidence, such as:

  • An independent appraisal

  • Sale prices of nearby properties

  • Photos of damage or needed repairs

4. Apply for Property Tax Exemptions

You may qualify for exemptions:

  • Homestead Exemption

  • Senior Citizen Exemption

  • Disability or Veterans Benefits

These exemptions can reduce your home’s taxable value..

Final Thoughts: Be a Proactive Homeowner

Understanding your real estate taxes doesn’t have to be overwhelming. When you know how property taxes are calculated and what you can do to challenge them, you’re in a much better position to protect your investment and avoid overpaying.

Need Help Navigating Your Property Tax Assessment?

At PahRoo Appraisal & Consultancy, LLC, we specialize in helping homeowners and property investors understand, manage, and appeal their property tax bills.

Contact us today

How One Man Turned a Motel Into Affordable Housing — With Help from TikTok
TL;DR

A 24-year-old from South Carolina turned an 80-room motel into 40 affordable studio apartments — inspired by TikTok, powered by crowdfunding, and driven by community need. This isn’t just a personal success story — it’s a glimpse into the future of housing solutions.

TikTok Isn’t Just for Dances Anymore

When most people scroll TikTok, they’re looking for laughs or inspiration.
But for Corvon Burgess, a young man from Manning, South Carolina, it became a classroom — and then a launchpad.

At just 24, Corvon stumbled on videos about real estate investing. Months later, he closed on an abandoned 80-room motel — and began converting it into affordable studio apartments.

The Vision: Affordable Living, Built From the Bones of the Past

In a town with limited rental options, this wasn’t just a real estate flip. It was a lifeline.

“I realized people were more willing to support something they felt part of,”
— Corvon Burgess via Business Insider

Each unit is designed to rent for under $950/month — utilities included.

The Numbers Behind the Project

Let’s break it down:

Purchase Price of Motel: $2.3 million

Number of Units: 40 studio apartments

Target Rent: <$950/month

GoFundMe Raised: $345,000+

Funding Sources: Crowdfunding, private lending, and direct community support

This Is Not an Isolated Case

Charlotte, NC offers another example:
Nonprofit Heal Charlotte turned a former Baymont Inn into transitional housing for up to 100 families. Funded by a $2.25M city grant, they’ve added:

  • A children’s art room
  • Community gardens
  • A market stocked with local produce

This is more than shelter. It’s support. It’s restoration.

Why It Matters: Turning Old Rooms Into New Futures

Here’s what this trend tells us:

  • Affordable housing can be creative and beautiful
  • Vacant motels can meet modern needs
  • Social media can inspire action — not just attention

And importantly: you don’t need to be a millionaire developer to make a difference.

Want to See the Transformation?

👉 Check out Corvon’s journey on TikTok:
@simplerealestate

Know a vacant motel in your area? Think beyond its past. Contact us if you need help!

🔗 Share this post with someone looking for real estate inspiration.

Housing Market 2025: What $1 Million Gets You Today

A Million Dollars Used to Buy Luxury. Now It Buys… the Basics?

Once upon a time, a $1 million home meant luxury: space, privacy, and maybe even a pool.
Today? In cities like San Francisco, Seattle, and parts of LA, $1 million might get you a dated 2-bedroom, and a bidding war.

We’re in a new era of housing where $1M no longer equals high-end. It’s entry-level. So how did we get here?

What’s Driving the Shift?

This isn’t just a coastal problem. Even secondary markets like Austin, Denver, and Phoenix are seeing seven-figure starter homes.
Here’s why:

  • Low Inventory: Decades of underbuilding have led to a serious supply crunch.

  • Rising Construction Costs: Inflation, materials, and labor shortages drive prices higher.

  • Zoning Restrictions: Local regulations make new, affordable builds nearly impossible.

  • Remote Work Migration: High-earning buyers are leaving coastal cities and driving up prices in previously “affordable” areas.

  • Fear of Missing Out: Many first-time buyers are jumping in now, afraid prices will rise further.

Where $1 Million Doesn’t Go Far

Let’s look at what $1M gets you today:

  • San Francisco: Maybe a 1-bed condo. If you’re lucky.

  • Los Angeles: A modest fixer-upper, with multiple offers.

  • Seattle: A small single-family home… with a long commute.

  • Austin: A cookie-cutter new build 45 minutes outside the city.

Even in the suburbs, buyers are finding themselves priced out or forced to compromise on size, location, or condition.

What Is a “Starter Home” Now?

Traditionally, a starter home was affordable for entry-level buyers, often smaller, modest, and budget-friendly.
Now, “starter” just means the lowest price available in the market. For many, that’s still $800K to $1.2M.

Worse yet, many first-time buyers rely on family help, jumbo loans, or co-buying with friends to compete.

Is This Sustainable?

Experts say this level of pricing pressure isn’t sustainable long-term.

While mortgage rates have cooled slightly, affordability remains near historic lows. Wages aren’t rising fast enough, and many buyers are already at their financial limits.

Still, limited supply means prices are unlikely to drop dramatically anytime soon.

Final Thoughts

In today’s market, $1M doesn’t guarantee luxury, it simply gets your foot in the door.

For aspiring homeowners, this shift is frustrating. For real estate professionals and appraisers, it’s a reminder of how location, demand, and perception continue to reshape value.

The “starter home” hasn’t disappeared, it just has a new price tag.

For insights into how zoning laws impact property values, explore our post on Zoning: The Most Boring Topic That Can Change Everything. Additionally, for official and up-to-date market data, the National Association of Realtors is a trusted resource.

Ready to navigate the evolving housing landscape? Contact us today, and our team will provide expert guidance tailored to your real estate goals.

Multigenerational family enjoying time together at home in 2025
Multigenerational Living and What It Does to Home Value

Multigenerational living has quietly become one of the most durable forces in American housing. Fourteen percent of recent buyers purchased a multigenerational home, near the record 17% set a year earlier. Behind the trend sits a practical question most articles skip: what do in-law suites, second kitchens, and converted garages actually do to a home’s value? As appraisers, we get to answer that one.

By the end of this article, you’ll know:

  • Who is buying multigenerational homes and why the trend is here to stay
  • Which features buyers consistently pay for, and which ones can backfire
  • How an appraiser actually values an in-law suite, a second kitchen, or a garage conversion

Why Multigenerational Living Became Mainstream

The National Association of Realtors 2026 Generational Trends report puts numbers on what families already feel. Gen X leads the trend, with 19% of buyers in that group choosing a multigenerational home. The top motivations are caring for aging parents, cost savings, and adult children moving back home.

None of those drivers is going away. Housing costs remain high, the population keeps aging, and baby boomers now account for 42% of all buyers, many of them moving specifically to be closer to family. So this is not a pandemic blip or a design fad. It is a structural shift in what a meaningful share of buyers need a house to do.

The Features Multigenerational Buyers Pay For

When families combine households, they are really buying privacy and independence under one roof. A few features deliver that consistently. A suite with its own entrance, bathroom, and sitting area lets a parent or adult child live semi-independently. A main-floor bedroom with an accessible bath serves aging relatives without a renovation later. Kitchenettes or full second kitchens let two households keep separate routines.

Flexible space matters almost as much as finished space. A basement that could become a suite, or a bonus room over the garage, gives buyers room to adapt. In neighborhoods where multigenerational demand runs strong, homes with these features often draw a deeper buyer pool and sell with less friction. But “often” is doing real work in that sentence, and this is where valuation gets interesting.

How an Appraiser Values an In-Law Suite or Second Kitchen

The honest answer: a feature is worth what the local market pays for it, not what it cost to build. Appraisers measure that through comparable sales. If homes with in-law suites in your area sell for more than similar homes without them, that difference is the feature’s contributory value. A $90,000 suite addition might contribute $60,000, or $110,000, depending entirely on local demand.

A quick example shows how this plays out. Two owners on similar blocks each spend $85,000 finishing a basement suite with a bath and kitchenette. One neighborhood has a steady stream of Gen X buyers housing aging parents, and suites there routinely command a premium. The other skews toward first-time buyers who just want the cheapest three-bedroom they can find. Same project, same cost, very different contributory value. Cost tells you what you spent. Only the market tells you what you got.

A second kitchen is the classic mixed signal. To a multigenerational buyer, it is exactly what they need. To others, it whispers “former illegal apartment,” and in some municipalities it raises real zoning questions about whether the home is being used as two units. An appraiser has to consider both the market’s reaction and the legal use of the property. The same feature can be a premium in one neighborhood and a mild drag in another.

Permits decide whether space counts at all. A garage converted to a bedroom suite without permits may not be included in the home’s finished living area, because unpermitted space carries legal and safety risk that lenders and buyers discount. Owners are sometimes shocked that their most expensive project added little on paper. The lesson runs the other direction too: a permitted, well-executed suite in a high-demand area is among the strongest value adds a home can have.

Buyers face the mirror image of this problem. Listings now advertise “in-law suite” and “related living” as premium features, and sellers price accordingly. Some of those premiums are earned. Others rest on unpermitted space, awkward layouts, or a second kitchen the city never approved. Before you pay extra for a multigenerational setup, it is worth knowing whether the feature will hold its value when you eventually sell, or whether you are buying someone else’s permit problem at a markup.

Check Three Things Before You Build or Buy

First, permits and zoning. Confirm that any existing conversion was permitted, and that your municipality allows what you plan to build. Second, the comps. If no home in your area has sold with a second suite, the market may not yet reward one, however useful it is to your family. Third, the resale pool. A design that serves your household beautifully should still make sense to the next buyer.

An appraisal answers the value side of all three before money moves. For buyers, it tells you whether the multigenerational home is priced on real contributory value or on wishful thinking. For owners planning a suite, it tells you what the market will likely give back. Either way, you decide with a number instead of a hunch.

Adding a suite or buying a home with one?

Find out what that in-law suite, second kitchen, or converted space is actually worth in your market before you commit the money.

Value the Feature First

Frequently Asked Questions

Does an in-law suite increase home value?

Usually, but the amount depends on local demand. An appraiser measures the suite’s contributory value by comparing sales of similar homes with and without one. A permitted suite in an area with strong multigenerational demand can add substantial value; the same suite elsewhere may return less than it cost to build.

Does a second kitchen add or hurt value?

It cuts both ways. Multigenerational buyers often pay for the convenience, while other buyers may see zoning risk or a former illegal conversion. An appraiser weighs the local market’s reaction and whether the kitchen complies with the property’s legal use before crediting it with value.

Does unpermitted converted space count in an appraisal?

Often it does not count as finished living area. Unpermitted conversions carry legal and safety risk, so lenders and buyers discount them, and appraisers may exclude the space from the home’s reported square footage. Permitting work before selling protects the value of the investment.

How common is multigenerational home buying?

Very common now. NAR’s 2026 Generational Trends report found 14% of recent buyers purchased a multigenerational home, near the record 17% the year before. Gen X buyers led the trend at 19%, motivated by caring for aging parents, cost savings, and adult children moving home.

Should I get an appraisal before adding an in-law suite?

It is a smart first step. An appraiser can tell you what similar suites contribute to sale prices in your specific area, so you know the likely return before construction starts. That protects you from overbuilding for your neighborhood.

Know What the Suite Is Worth Before the Market Tells You

PahRoo Appraisal & Consultancy values homes across the Chicago area and beyond, led by an appraiser holding both MAI and SRA designations. From a residential appraisal before a purchase or renovation to full appraisal services for estates, divorce, and tax matters, we put a defensible number on the property so your family can plan around it.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712