Our blog

Latest news
& events

Newly built commercial property valued through a cost approach commercial appraisal
The Sales Comparison and Cost Approaches in Commercial Appraisal

Two of the three approaches to value get less attention than they deserve. The income approach dominates most commercial reports, so brokers and lenders tend to skim the rest. That is a mistake on the wrong property. A cost approach commercial appraisal is often the only credible path to value on a new building or a special-use facility. And the sales comparison approach tells you whether a buyer’s likely price lines up with what the income says. So here is how each one works, when it leads, and what to check when you read one.

By the end of this article, you’ll know:

  • How the sales comparison approach is adapted for commercial property with thin data
  • What a cost approach actually adds up, and how depreciation is measured
  • When each approach should carry the weight, and how to check that it does

How the Sales Comparison Approach Works for Commercial Property

The sales comparison approach values a property by what similar properties sold for, adjusted for the differences. Residential appraisers usually have several nearby sales from the last few months to work with. Commercial appraisers rarely have that luxury. A submarket may produce four flex-industrial sales in two years, and none of them is a twin of the subject.

So the method bends to fit the data. The search area widens, sometimes to the whole metro. The time window stretches too. Then a market conditions adjustment has to account for price movement between the comparable’s sale and the effective date. The unit of comparison also changes with the property type: price per square foot for industrial and office, price per unit for apartments, price per net rentable square foot for self-storage, price per key for hotels.

Adjustments are where the work lives. Location, size, age and condition, construction quality, ceiling height, loading, parking ratio, and lease status all get weighed. Where possible, paired sales or market participants support each adjustment, not the appraiser’s instinct. A grid of round-number adjustments with nothing behind them is the first thing a reviewer questions. Our overview of the three approaches to value covers how they fit together. This piece goes deeper on the two that get skipped.

One more commercial wrinkle. A sale of a leased building reflects the leases, not just the bricks. A comparable with a credit tenant on a ten-year lease is not the same as a vacant building of the same size. So the appraiser has to know the terms of each sale. Confirming them with a broker or a principal is part of the job, not a courtesy.

What a Cost Approach Commercial Appraisal Adds Up

The cost approach asks a simple question. What would it cost to buy the land and build this property new today, less the value the existing building has lost? The formula runs: site value, plus replacement cost new, plus entrepreneurial incentive, minus accrued depreciation.

Site value comes from land sales, so the cost approach starts with its own small sales comparison analysis. Replacement cost new is the cost to build a modern equivalent with the same utility, not an exact copy. That distinction matters on older buildings. Reproducing a 1920s masonry warehouse with its original details would cost far more than replacing its function with a tilt-up box. Buyers pay for function. Cost figures come from published cost services, contractor bids, and recent local projects. They cover direct costs such as labor and materials, plus indirect costs such as architecture, permits, financing, and lease-up.

Entrepreneurial incentive is the profit a developer would need to take on the project. Leaving it out understates cost. Including it without market support overstates it. Either way, it should be visible in the report, not buried.

The Uniform Standards of Professional Appraisal Practice require a developed cost approach to address site value, cost new, and accrued depreciation. That last item is where most of the judgment sits.

How Depreciation Is Measured

Depreciation in an appraisal is not the tax schedule. It is the gap between what the building would cost new and what it contributes to value today. It comes in three forms.

Physical deterioration is wear. Roofs age, parking lots crack, mechanical systems reach the end of their lives. Some of it is curable, meaning the cost to fix is less than the value it adds back, and some is not. Functional obsolescence is a design problem. Think 14-foot clear height in a market that wants 32 feet, or too little power for modern loads. External obsolescence comes from outside the property line, such as rising submarket vacancy or a highway interchange that moved the traffic.

Appraisers measure depreciation several ways. The age-life method compares effective age to total economic life. Market extraction pulls depreciation out of actual sales. Subtract land value from the sale price, then compare what remains to cost new. Breakdown analysis prices each form of depreciation separately. On a new building the number is small and easy to support. On a 45-year-old building it can exceed half of cost new. The further the estimate has to reach, the less weight the approach deserves.

A Worked Example on an Industrial Building

Consider a 36,000 square foot warehouse, twelve years old, in a stable industrial submarket. The cost approach might run like this:

  • Site value from land sales: $900,000
  • Replacement cost new, including indirect costs and entrepreneurial incentive: $4,200,000
  • Less accrued depreciation at 30 percent: $1,260,000
  • Depreciated cost of improvements: $2,940,000
  • Indicated value by the cost approach: $3,840,000

Now the sales comparison approach. Four metro warehouse sales, adjusted for location, age, clear height, and market conditions, bracket $98 to $112 per square foot. The appraiser reconciles to $105 per square foot, which indicates $3,780,000.

The two approaches land within two percent of each other. That agreement is itself evidence. When the approaches disagree by 20 percent, something is wrong with an input, and the reconciliation should say which one.

When There Are No Comps

Some properties have almost no market. A fire station, a school, a church, or a purpose-built manufacturing plant may trade once in a generation, and often not as the same use. These are special-use properties. Income struggles because there is no rental market. Sales comparison struggles because there are no sales. Cost is usually the only approach with real evidence behind it.

New construction is the other clear case. A building completed last year has minimal depreciation, current cost data, and a land value that can be supported. Lenders financing construction lean on cost for exactly that reason. Still, they expect it to reconcile against the completed value from the other approaches.

Cost also plays a quieter role on ordinary income property. When the income approach lands well below what it would cost to build, new supply is not feasible at current rents. That gap tells a lender something about competitive risk. It tells a broker something about how long existing stock will hold its pricing. An appraiser who develops cost even when it does not lead is giving you that signal for free.

Where Each Approach Earns Its Weight

On a stabilized multi-tenant building, income leads and sales comparison supports it. On an owner-occupied building with an active market, sales comparison may lead. Owner-user buyers think in price per square foot, not cap rate. On a special-use facility or a building still in its first year, cost leads. Our piece on what drives office building value shows the income-led case in detail.

The weighting is a judgment the appraiser has to explain. A report that develops all three approaches and then averages them has not reconciled anything. A report that leans on one approach should say why its evidence is stronger. Read the reconciliation with that question in mind, and you will know quickly whether the report was built or assembled.

Ask Which Approach Carried the Weight, and Why

Before relying on a commercial value, find the reconciliation and check three things. First, was the leading approach the right one for this property type and its data? Second, do the sales adjustments and the depreciation estimate have market support the report actually shows? Third, do the approaches agree, and if not, is the gap explained? If any answer is no, the cover-page number rests on less than it appears to. So ask the appraiser. A good one will walk you through it.

Selling a Building With No Clean Comps?

PahRoo develops the sales comparison and cost approaches with the support shown, so brokers can price with confidence and lenders can see the evidence.

Scope a Commercial Appraisal

Frequently Asked Questions

When is the cost approach used in commercial appraisal?

It leads on new or nearly new buildings, where depreciation is small and costs are current, and on special-use properties such as schools, churches, and purpose-built plants that have few or no comparable sales. On ordinary income property it usually supports the conclusion and serves as a feasibility check against the income approach.

How does the sales comparison approach work for commercial property?

The appraiser locates sales of similar properties, confirms the terms of each sale, and adjusts for differences in location, size, age, condition, lease status, and market conditions. Because commercial sales are scarce, the search often covers a wider area and a longer time period, and the unit of comparison changes by property type.

Why is the cost approach used for special-use property?

Special-use properties rarely sell and rarely rent, so the sales comparison and income approaches have little evidence to work with. The cost approach can still be developed from land sales, current construction costs, and a supported estimate of depreciation, which makes it the most credible path to value for those properties.

How is depreciation measured in a commercial appraisal?

Appraisal depreciation is the gap between cost new and the building’s current contribution to value. It includes physical deterioration, functional obsolescence, and external obsolescence. Appraisers estimate it through the age-life method, market extraction from actual sales, or a breakdown of each form, and the estimate should be supported in the report.

Are there enough comps for commercial property?

Often not many. A submarket may produce only a handful of relevant sales over two years. Appraisers widen the geography, extend the time window, and adjust for market conditions to compensate. When comparable sales are too thin to support a conclusion, the report should say so and lean on the cost or income approach instead.

Sales, Cost, and Income Analysis From One Appraisal Team

PahRoo Appraisal & Consultancy develops all three approaches to value on commercial assignments across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, from single-tenant industrial to special-use facilities. Our commercial appraisal services page covers scope and property types, our guide to net operating income explains the income side, and you can contact our team or call 773-388-0003 to discuss a specific property.
Homes for sale on a Chicago street during the fall 2026 housing market
Fall 2026 Housing Market Brings Buyers More Choices

Buyers heading into the fall 2026 housing market will find more homes to choose from than they did a year ago. Prices, on the other hand, are barely moving. The national numbers for mid-August describe a market that is loosening slowly rather than breaking, and Chicago is quietly running against the grain.

By the end of this article, you’ll know:

  • Where inventory, sales, and prices stand as of mid-August 2026
  • Why Chicago home values are still rising while the national market flattens
  • What a flat market with heavy price cutting means for your home’s appraised value

What the Fall 2026 Housing Market Numbers Show

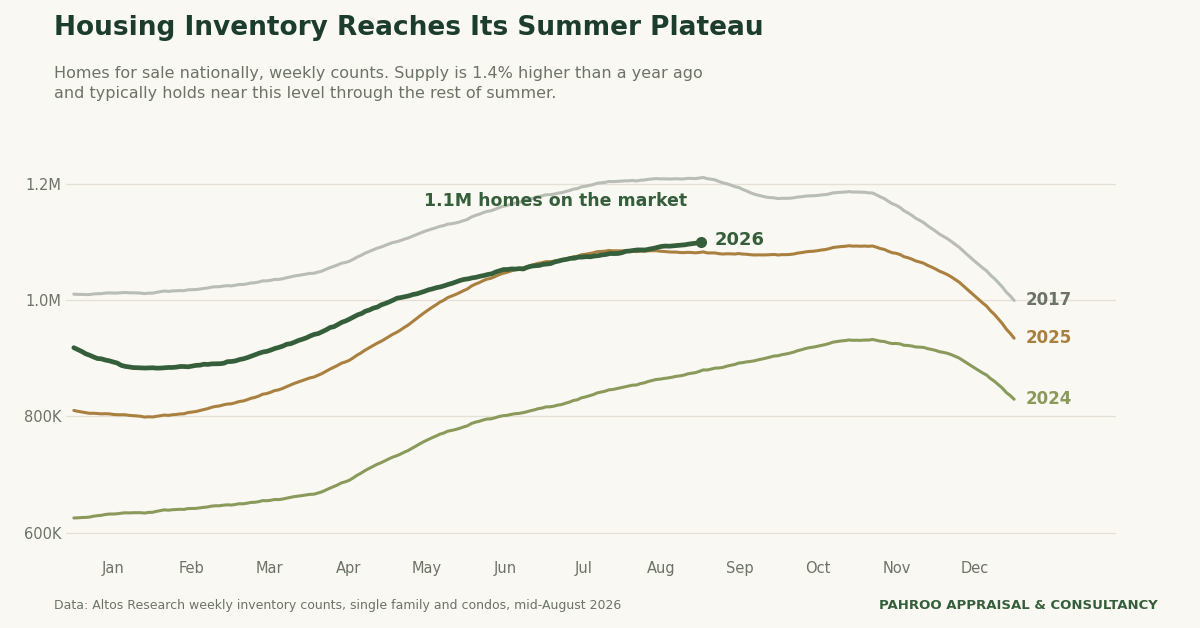
Four numbers tell the story. Mortgage rates climbed about 30 basis points in July and now sit near their highest levels of the year. Pending home sales came in around 77,000 new contracts in a recent week. That is down 3.9 percent from a year ago. Total inventory sits just above 1.1 million homes, about 1.4 percent higher than last year. The national median price for single family homes is holding near $399,000, essentially flat year over year.

Fall 2026 housing market inventory at 1.1 million homes compared to 2025, 2024, and 2017

The weekly tracking comes from Altos Research, which counts every active listing in the country. The longer arc shows up in the Federal Reserve’s national active listing data as well: supply has been rebuilding for several years, but it is still climbing gradually, not flooding the market.

Compare this to September 2023, when rates jumped 70 basis points in a single month and demand fell hard. Rates have moved a similar amount this time, but over five months. So the squeeze is real, just slower and easier to miss.

Why Chicago Is Running Against the National Grain

National averages hide a lot. Markets with plenty of supply, including Las Vegas and Seattle, are seeing slightly negative price movement. Recovering metros such as San Francisco and Miami have flipped back to appreciation. Tight supply markets, and Chicago is the clearest example, are still posting gains.

Chicago never overbuilt during the pandemic run, and listing activity here has stayed thin relative to demand. When few homes come to market, even modest buyer interest keeps prices firm. That is why a homeowner in Portage Park or Evanston can still see values inching up while the national headline reads flat.

In practice, this split means national coverage tells you very little about your own block. A Chicago real estate appraisal works from local sales, local supply, and the specific condition of your property, which is where the real answer lives.

Price Reductions Are the Early Warning System

One national figure deserves special attention: 41.7 percent of homes on the market have taken a cut from their original list price. At the current pace, that share will pass last year’s level sometime in September.

Price reductions matter because they lead sale prices by roughly three to six months. Sellers adjust their asking price before closed sales show any weakness. So a rising reduction rate in August hints at softer closing prices heading into winter, even while the median holds steady today.

Still, a price cut is not a crash signal. Reduction rates ran at similar levels last fall, and national prices finished the year flat rather than down. The takeaway is direction, not disaster: sellers have less pricing power than the headline median suggests.

What a Flat Market Means for Your Home’s Appraised Value

A flat market is deceptively tricky for valuation. When prices rise or fall steadily, recent sales point clearly in one direction. When the market goes sideways with four in ten listings cutting price, the spread between asking prices and closed prices widens. Two similar homes on the same street can sell months apart at noticeably different numbers.

This is where automated estimates struggle. Algorithms lean heavily on list prices and older sales, and both are unreliable guides right now. An appraiser instead works from verified closed sales, adjusts for condition and timing, and weighs how long comparable homes actually sat before selling.

For homeowners, the flat national picture cuts both ways. If you are selling, pricing to the market on day one matters more than usual, because chasing the market down with reductions costs both time and money. The stakes rise further in an estate, a divorce, or a tax appeal. In those settings, a defensible number matters most exactly when public data sends mixed signals. Our residential appraisal services exist for exactly these moments.

Waiting for Lower Rates Carries Its Own Cost

Plenty of buyers are sitting out this fall, waiting for rates to drop. That is understandable, but the trade is rarely free. When rates fall, sidelined demand tends to return quickly, and competition comes back with it. More inventory and less competition almost never arrive at the same time.

Buyers shopping this fall face higher borrowing costs but more choices, more negotiating room, and sellers who have already trimmed their expectations. Buyers who wait may get a cheaper loan on a more expensive, more contested house. Neither path is wrong. But each one has a price tag, and it helps to see both clearly.

How to Read Your Own Market This Fall

Ignore the national median and watch three local signals instead. First, how many homes like yours are actually for sale within a mile or two. Second, what share of those listings have cut their price. Third, how long recent sales sat on the market before going under contract. Those three numbers reveal whether your neighborhood behaves like flat national America or like tight supply Chicago. Then, if a real decision rides on the answer, skip the algorithm. Get a professional opinion of value instead.

Your Block Is Not the National Average

Flat headlines, rising Chicago values, and four in ten listings cutting price. An independent appraisal cuts through the noise with a number built from your street, not the country’s.

Get a Local Value

Frequently Asked Questions

Is fall 2026 a buyer’s market?

Not fully, but it leans that way in many metros. Inventory is above 1.1 million homes and 41.7 percent of listings have cut their price, so buyers have more choices and more room to negotiate. Tight supply markets like Chicago remain closer to balanced.

Why are home prices flat when inventory is rising?

Inventory is rising slowly, about 1.4 percent year over year, while demand has cooled by a similar amount. Supply and demand are weakening together, so the national median price near $399,000 has stayed essentially unchanged from last year.

Are Chicago home prices still going up in 2026?

Yes. Chicago remains a tight supply market, and homes here are still posting modest gains even as the national median stays flat. Local supply, not the national headline, is what drives values on your block.

What does a 41.7 percent price reduction rate mean?

It means 41.7 percent of active listings have lowered their price from the original asking number. Price reductions lead closed sale prices by roughly three to six months, so a rising rate suggests softer prices ahead, though not necessarily declines.

Should I wait for mortgage rates to drop before buying?

Waiting can backfire. When rates fall, sidelined buyers return and competition rises with them. Today’s market offers more inventory and more negotiating room, so the choice is between a cheaper loan later or a better selection now.

Get a Number You Can Act On

Founded in Chicago and led by designated MAI and SRA appraisers, PahRoo Appraisal & Consultancy values residential and commercial property across Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Whether you need a market value opinion before listing, an estate or divorce appraisal, or support for a tax appeal, our real estate appraisal services deliver independent, defensible answers you can build a decision on.

Property owner reviewing a 2026 Cook County reassessment notice at home
South Suburbs Reassessment 2026: When to Get a Second Opinion

The 2026 south suburbs reassessment is landing in mailboxes, and some of the numbers are startling. Jumps of 30 percent are common in reassessment years, and some properties see far more. Before you accept a number that will follow you for three years, it is worth understanding how it was produced and how to test it.

By the end of this article, you’ll know:

  • Why the 2026 reassessment matters through 2028, not just this year
  • How mass appraisal produces large jumps, and where it goes wrong
  • When an independent appraisal justifies a formal appeal

What the 2026 South Suburbs Reassessment Actually Sets

Cook County reassesses one third of the county each year on a triennial cycle. In 2026, it is the turn of the south and west suburban townships. The Cook County Assessor’s assessment calendar shows townships opening on a rolling schedule, with reassessment notices mailed as each township opens. The value on that notice becomes the base for the 2026 through 2028 tax years unless it is successfully challenged.

That three-year reach is the point people miss. An inflated 2026 value does not just raise one bill. It compounds across three billing cycles, and reassessment generally wipes out prior relief, so reductions won in earlier appeals reset to zero.

Why the Jumps Are So Large This Cycle

The south and west triad was last reassessed in 2023, a cycle remembered for steep increases and well-publicized errors. Three years of market movement now gets recognized all at once. That is why a 30 percent jump can appear even when nothing about the property changed. On top of that, 2025 closed with some of the largest tax increases in county history. The average residential bill rose around 16 percent as falling commercial values shifted burden onto homeowners.

So a large 2026 increase sits on top of an already elevated bill. The reassessment itself does not set your tax, but it sets your share of it. If your value rose faster than your township’s overall, your share grows.

Mass Appraisal Gets Averages Right and Individual Properties Wrong

The Assessor values hundreds of thousands of parcels with statistical models, not property-by-property inspections. Mass appraisal is a legitimate technique for that job, but it works from recorded characteristics and neighborhood-level trends. It cannot see deferred maintenance, a functionally awkward floor plan, or the busy arterial road behind your lot line. It also inherits data errors: wrong square footage, wrong classification, improvements that no longer exist.

That gap between the model and the property is exactly what an appeal tests. The question is never whether values rose in your township. They did. The question is whether your specific number reflects what your specific property would sell for.

When a 30 Percent Jump Deserves a Second Opinion

Not every increase warrants a fight. A single-point appraisal of every reassessed parcel would waste money, and some new values are simply accurate. But a few situations justify independent review. The new value implies a sale price the local market cannot support. Similar nearby properties carry meaningfully lower assessments. The characteristics on file are wrong. Or the parcel is income-producing and the implied value ignores actual rents and vacancy. In those cases, an independent appraisal gives you a defensible market value to measure the assessment against. It is developed to USPAP standards, not modeled from averages.

For commercial owners, the stakes multiply. Larger assessed values, higher assessment levels, and three years of exposure mean even a modest percentage error carries six-figure consequences over the triennial.

Act Inside the Window, Because It Closes Fast

Each township’s appeal window opens when its notices mail and closes on a firm deadline. The first stop is the Assessor’s office, then the Board of Review. Windows roll through the fall, and once your township closes, the next chance is a year away with the new value already locked in. So the sequence is simple. Check your notice against reality when it arrives. Get an independent read on value if the number looks wrong. Then file inside your township’s window with evidence attached. Our breakdown of the 2026 Cook County reassessment walks through what that evidence should look like.

Did your new assessment pass the sniff test?

A 2026 value follows you through 2028. PahRoo delivers an independent appraisal that tells you whether the number holds up, before your appeal window closes.

Question Your Reassessment

Frequently Asked Questions

Why did my Cook County assessment increase in 2026?

If your property is in the south or west suburbs, 2026 is your triennial reassessment year. The Assessor updated your value to reflect three years of market change since 2023. That is why increases arrive all at once rather than gradually.

How often does Cook County reassess property?

Every three years. The county is divided into three sections, and one is reassessed each year. The south and west suburbs are reassessed in 2026, and those values generally apply through 2028.

What townships are reassessed in 2026?

The townships of the south and west suburban triad. Each township opens on a rolling schedule through the year, and the Cook County Assessor’s website lists mailing dates and appeal deadlines for each one.

Should I appeal a reassessment?

Appeal when the new value exceeds what your property would realistically sell for. Also appeal when comparable properties are assessed lower, or when the county’s records about your property are wrong. An independent appraisal is the cleanest way to test the number first.

Does an appeal lower my taxes for all three years?

A successful appeal reduces the assessed value that carries through the triennial, so relief won in 2026 generally benefits the 2027 and 2028 bills too. You can also appeal again in the following years if grounds remain.

Independent Valuation for the 2026 Cycle

PahRoo Appraisal & Consultancy provides independent residential and commercial appraisals across Cook County, supporting owners, attorneys, and CPAs through reassessment years. For context on how heavy appeal volume has reshaped the process, see our analysis of record Cook County appeal filings. Or start with our property tax appeal FAQs.

Renovated Chicago home kitchen listed for sale with unpermitted work
How to Sell a House With Unpermitted Work in Chicago

I was appraising a home in Bucktown last month. Beautiful renovation: open kitchen, custom cabinetry, new bathrooms, updated electrical. None of it had ever been permitted. So can you sell a house with unpermitted work? Yes, but not at the price her broker had assumed, and not to every buyer.

When unpermitted work surfaces during an appraisal, four things happen at once. The appraiser must disclose it. The lender’s underwriting shifts. The buyer pool narrows. And the seller lands in a conversation nobody planned for. Here is how each plays out, and what to do before the appraisal is ordered.

By the end of this article, you’ll know:

  • How appraisers and lenders are required to treat unpermitted renovations
  • How Chicago’s retroactive permit process works, and what it costs in time
  • Three pricing strategies for listing a home with unpermitted work

What Happens When You Sell a House With Unpermitted Work

The appraiser cannot look away. Under USPAP and the Fannie Mae Selling Guide B4-1.3-05, an appraiser who identifies unpermitted additions or improvements must comment on the quality and appearance of the work. Then they must assess its effect, if any, on market value.

That analysis turns on three questions. Was the work done in a workmanlike manner, with sound structure and materials that match the neighborhood? Would a typical buyer in this market accept it, or treat it as a negotiating problem? And if the work had to be permitted retroactively or removed, what would that cost?

Unpermitted work is not automatically excluded from value. A skilled renovation, typical of the market, may contribute close to its full worth. A poorly executed one may contribute very little. But either way, it gets analyzed and disclosed. Our residential appraisers see this in Chicago constantly, and the sellers who fare best are the ones who knew before the report landed.

How Different Lenders React to Unpermitted Work

Financing programs do not treat unpermitted work the same way, and this is where the buyer pool starts shrinking.

Fannie Mae and Freddie Mac will generally finance a property with unpermitted work once the appraiser has addressed quality and market impact. The space can even count toward gross living area if it is workmanlike and typical for the market. Individual lenders may layer on stricter overlays.

FHA is tougher. The property must meet the Minimum Property Requirements in HUD Handbook 4000.1. Significant unpermitted work can push the appraisal to “subject to” status, meaning the loan cannot close until the work is permitted or corrected. VA loans follow a similar pattern under their own property requirements.

Cash buyers face no lender rules at all. They simply use the unpermitted status to negotiate the price down. So a home with substantial unpermitted work often ends up competing for cash buyers and flexible conventional borrowers, while government-insured buyers drop out entirely.

The Chicago Retroactive Permit Process

For many sellers, permitting the work after the fact is the cleanest fix. The Chicago Department of Buildings handles it in a recognizable sequence: application, plan submission, plan review, inspection, correction of any deficiencies, then permit issuance.

The plans are usually the first surprise. Electrical, plumbing, and structural work typically require professional drawings of what was already built, which means architect or engineer fees before the city sees anything. The second surprise is the inspection. The completed work must meet current code, so older wiring, unvented plumbing, and unsupported structural changes all trigger correction orders before the permit issues.

Plan for roughly two to four months on a typical residential project, longer when corrections stack up. Costs run from a few thousand dollars for simple work to far more when code fixes are required. Chicago also charges more for work started without a permit, and fines can apply on top. Worse, if the city discovers the work before the seller addresses it, a stop-work order can freeze everything mid-transaction.

Three Ways to Price a Home With Unpermitted Work

Brokers have three workable strategies, and each trades money for time in a different direction.

The first is pricing at unpermitted market value. List at what the property is worth given its actual permit status. This attracts cash and flexible conventional buyers immediately. It is the fastest path to closing and the lowest number.

The second is permitting before listing. The seller completes retroactive permitting first, then lists a fully documented property to the entire buyer pool at full market value. It usually produces the best financial outcome, if the seller can absorb the months of delay and the upfront cost.

The third is disclosing and negotiating. List near full market value with the unpermitted status clearly disclosed, then handle it through price reductions or credits during the deal. This approach is common. It also produces the most extended escrows and the most collapsed contracts, because the buyer’s lender gets a vote.

Ask About Permits Before the Listing Agreement Is Signed

The intake walkthrough is where this problem should surface, not the appraisal. Ask every seller: What has been renovated since you bought the home? Which projects had permits pulled, and do you have the final inspection approvals? Was anything done by a prior owner? Has the electrical panel been upgraded, plumbing rerouted, or rooms reconfigured?

If the answers point to unpermitted work, the broker can recommend retroactive permitting, adjust the pricing strategy, or walk away from the listing. The one option that fails is assuming the appraisal will not catch it. A pre-listing appraisal answers the value question before a lender’s appraiser answers it for you, and it gives the seller real numbers to choose a strategy with.

Listing a Home With Unpermitted Work?

A pre-listing appraisal from PahRoo tells you what the property is worth as it stands, and what permitting would change, before a buyer’s lender decides for you.

Get a Pre-Listing Appraisal

Frequently Asked Questions

Can you sell a house with unpermitted work in Chicago?

Yes. Unpermitted work does not block a sale, but it must be disclosed, the appraiser must analyze it, and some financing programs will not close until it is permitted or corrected. The practical effect is a smaller buyer pool and pricing pressure.

Does unpermitted work count in the appraised value?

Sometimes. Fannie Mae guidance lets appraisers give value to unpermitted improvements that are workmanlike and typical for the market. Poor-quality work may contribute little or nothing. The appraiser must comment on the work and its market impact either way.

Will FHA finance a home with unpermitted renovations?

Only if the property still meets FHA Minimum Property Requirements under HUD Handbook 4000.1. Significant unpermitted work often makes the appraisal “subject to” repairs or permits, which delays or blocks closing until resolved.

How long does a retroactive permit take in Chicago?

Plan for roughly two to four months on a typical residential project. The timeline covers application, professional drawings, city plan review, inspection, and any code corrections. Complex projects or required repairs extend it.

Should a seller permit the work before listing or just disclose it?

Permitting first usually brings the best price because the full buyer pool returns. Disclosing and negotiating is faster to market but tends to mean longer escrows and lender complications. A pre-listing appraisal quantifies the gap so the seller can decide with real numbers.

Know the Number Before the Buyer’s Lender Does

PahRoo Appraisal & Consultancy provides pre-listing, lending, and litigation-ready real estate appraisal services across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Our team appraises renovated and Chicago-area homes with unpermitted improvements every week. Questions about a specific property? Contact our team or call 773-388-0003.


What Drives the Value of an Office Building

An office building appraisal comes down to one question: how reliably will this building produce income, and for how long? Everything the appraiser examines feeds that answer. So when owners ask why two similar-looking buildings carry very different values, the explanation almost always sits in the leases, the tenants, and the submarket rather than the architecture.

By the end of this article, you’ll know:

  • The five factors that carry the most weight in office value
  • How leases, rollover, and tenant credit shape the income analysis
  • Why Class A buildings and older stock are moving in opposite directions

What an Office Building Appraisal Weighs Most

Five factors do most of the work in an office valuation:

  • Occupancy and lease terms: how much space is leased, at what rents, and for how long
  • Tenant credit: the financial strength behind each signature on the rent roll
  • Location and submarket: the vacancy, rent, and demand picture on that block, not the metro average
  • Building class and condition: where the property sits in the flight to quality
  • Market cap rates: what buyers currently pay for a dollar of office income

Office buildings are valued mainly through the income approach, because buyers purchase them for their income streams. The appraiser tests each factor above and translates it into the numbers behind the value.

Income Is the Engine: Leases, Rollover, and NOI

The rent roll gets read line by line. Contract rents are compared against market rents. Expirations are mapped across the holding period, because a building with 40 percent of its leases rolling in two years carries more risk than one with staggered ten-year terms. Rent steps, expense reimbursements, tenant improvement obligations, and leasing commissions all shape the projection.

Those inputs flow into net operating income, and we covered how that number gets built in our guide to net operating income in commercial real estate. For office specifically, the vacancy assumption does heavy lifting. Actual occupancy, submarket vacancy, and realistic downtime between tenants all get weighed rather than assumed away.

Tenant Credit: The Rent Roll Behind the Rent Roll

A lease is only as good as the tenant paying it. Ten years of income from an investment-grade company is worth more than the same rent from a startup, so appraisers consider tenant quality when weighing the durability of income. Concentration matters too. A single-tenant building lives or dies with one renewal decision, while a diversified roster spreads that risk across many decisions.

This is why two buildings with identical NOI can appraise differently. The income may match today, but the probability of it continuing does not, and buyers price that difference.

Building Class, Condition, and the Flight to Quality

The office market is splitting by quality. According to the CBRE Q1 2026 U.S. office market report, overall vacancy stood at 18.6 percent while prime buildings ran at 12.7 percent, and asking rents grew at their fastest pace in six years. Tenants are concentrating in the best space and abandoning the rest.

For the appraisal, class is not a label but a set of measurable traits: systems, amenities, floor plates, energy performance, and the capital spending needed to stay competitive. An older Class B building may need substantial investment just to hold its tenancy, and that cost comes out of value. In some cases, highest and best use analysis even asks whether the building should remain an office at all.

Why Office Values Fell, and How an Appraisal Reads the Recovery

Office values dropped for two stacked reasons. Hybrid work cut demand for space, which pushed vacancy up and rents down in weaker buildings. Then higher interest rates pushed cap rates up, which cut the price of every dollar of income. National vacancy has now edged past its peak and demand has turned positive, but the recovery is uneven across markets and building classes.

That unevenness is exactly why office work demands submarket-level analysis. A metro average tells you little when one corridor is tightening and the next is emptying. Our commercial appraisal services build the value from the property’s actual leases and its actual submarket, so the conclusion reflects your building rather than the headlines.

What is your office building actually worth right now?

In a market moving this unevenly, last year’s number is stale. PahRoo appraises office property from the rent roll up, with submarket evidence a buyer or lender can verify.

Request a Commercial Appraisal Quote

Frequently Asked Questions

What drives the value of an office building?

Occupancy and lease terms, tenant credit, submarket conditions, building class and condition, and market cap rates. These determine how much income the building produces, how durable that income is, and what buyers will pay for it.

How are office buildings appraised?

Mainly through the income approach. The appraiser analyzes the rent roll, compares contract rents to market rents, applies vacancy and expense assumptions, and converts the resulting net operating income into value using market-derived rates, checked against comparable sales.

Why have office building values fallen?

Hybrid work reduced demand for space, which raised vacancy and weakened rents, while higher interest rates pushed cap rates up. Both forces cut value at once. The decline has been uneven, hitting older buildings much harder than prime space.

What is a Class A office building?

The highest-quality tier in a market: modern systems, strong locations, competitive amenities, and creditworthy tenants. Class B and C buildings are older or less competitive. Class is relative to the local market rather than a fixed national standard.

How does vacancy affect office value?

Vacant space produces no income but still incurs expenses, so vacancy reduces net operating income directly. Appraisers also weigh submarket vacancy, because it sets how long re-leasing will take and what rent the space can realistically achieve.

Office Valuation Built From the Rent Roll Up

PahRoo Appraisal & Consultancy appraises office and other commercial property across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, for owners, investors, and lenders. Start with our Chicago appraisal services page, or review our appraisal consulting FAQ for scope and timing questions.

Qualified appraisal report for a charitable donation of Chicago commercial real estate.
Qualified Appraisal for Charitable Donation of Real Estate

A CPA called me last spring about a deduction under audit. Her client had donated a piece of Chicago commercial real estate to a nonprofit and deducted $850,000, the appraised value. A charitable donation of real estate rests on a qualified appraisal that meets the IRS definition. This one missed it three ways.

The appraiser was licensed but did not meet the federal definition of a qualified appraiser. The report lacked the required declarations. And the effective date fell three months after the donation. Any one of those flaws can sink the deduction on its own. Together, they put the full $850,000 at risk, plus possible accuracy-related penalties on top.

By the end of this article, you’ll know:

  • What the IRS requires from the report and the appraiser under Treas. Reg. 1.170A-17
  • How the 60-day window and the valuation effective date actually work
  • The Form 8283 steps that protect the deduction if the IRS examines it

What Counts as a Qualified Appraisal for a Charitable Donation of Real Estate

The rules live in one regulation. Under Treas. Reg. 1.170A-17, a qualified appraisal is a document prepared by a qualified appraiser in accordance with generally accepted appraisal standards. The regulation defines those standards as the substance and principles of USPAP, so a report that ignores USPAP fails at the starting line.

The report itself must carry specific content. It needs a detailed description of the property and its condition, the valuation effective date, and the fair market value as of that date. It also needs the appraiser’s identity, qualifications, signature, and date, along with a statement that the appraisal was prepared for income tax purposes.

Then come the declarations. The appraiser must state that they hold themselves out to the public as an appraiser and are qualified to value this type of property. They must also acknowledge that a substantial or gross valuation misstatement can trigger a civil penalty. Because the declarations are mandatory, a report without them can be rejected even when the value itself is defensible. So the engagement should specify a tax-purpose report from the start. We scope our own appraisal assignments around the intended use for exactly this reason.

Who Meets the Qualified Appraiser Definition

A state license is not enough. Neither is experience alone. The appraiser must have verifiable education and experience in valuing the specific type of property being donated, and the report has to document it.

There are two paths. The first is a designation from a recognized professional appraiser organization, earned for demonstrated competency in the relevant property type. For real estate, that includes the MAI, the SRA, and the ASA designations. The second path combines successful coursework in valuing that property type with at least two years of experience doing so.

The appraiser must also regularly perform appraisals for compensation. They cannot have been prohibited from practicing before the IRS during the three years before the appraisal date. Finally, the appraiser cannot be the donor, the donee, or a party to the transaction. So a broker who arranged the gift, however credentialed, is out.

The 60-Day Window and the Valuation Effective Date

Timing trips up more donations than valuation does. The appraisal must be dated no earlier than 60 days before the contribution and no later than the return’s due date, including extensions. The donor must receive it before that due date too.

The effective date follows its own rule. For a report dated before the donation, the effective date must fall within 60 days before the contribution. It cannot fall later than the contribution itself. If the report is dated after the donation, the effective date must be the contribution date exactly. My caller’s file failed here: the value spoke as of a date three months after the gift, which answers the wrong question.

Real estate values move, so this rule has teeth. The fix is usually straightforward. A qualified appraiser can prepare a retrospective appraisal with an effective date matching the donation. The analysis relies only on market evidence available as of that date. That is routine work for firms that handle tax assignments, but it has to be ordered, not assumed.

Form 8283 Is Where the Deduction Survives or Dies

The paperwork converges on one form. For real estate deductions over $5,000, Section B of Form 8283 must be fully completed and filed with the return. The qualified appraiser signs it, the donee organization acknowledges the gift on it, and an incomplete section can void the deduction by itself.

The threshold rises again at $500,000. Above that figure, the full qualified appraisal must be attached to the return, not merely retained in the file. And because the IRS is never required to accept an appraised value, high-dollar gifts draw closer review. Property recently purchased for far less than the claimed value, conservation easements, and unusual property types all invite scrutiny. The government’s own valuation guidance in IRS Publication 561 is worth reading before the return goes out, because examiners certainly have.

One more detail catches people. The appraisal fee cannot be based on the appraised value in any way. A contingent fee arrangement disqualifies the report outright.

Sequence the Appraisal Before the Deed Records

The protective timeline starts before the gift, not at tax time. First, verify the appraiser meets the qualified appraiser definition and will prepare the report to Treas. Reg. 1.170A-17 and USPAP. Then schedule the work so the report date lands inside the 60-day window, with the effective date tied to the planned donation date.

At the donation, document the contribution date clearly through the deed recording or transfer letter. When preparing the return, check the report against the regulation and complete Form 8283 Section B with the appraiser’s signature. Attach the full appraisal for deductions over $500,000. Then retain everything, because the burden in an examination sits with the taxpayer.

Our lane in this process is the value and the compliant report. How the deduction is claimed, timed, and defended on the return is properly the CPA’s work. When both sides do their part at the front end, the deduction that reaches the IRS is one that can hold.

Advising a Client on a Real Estate Donation?

PahRoo prepares qualified appraisals built to Treas. Reg. 1.170A-17 and USPAP, with the declarations, timing, and effective date the IRS expects.

Order a Qualified Appraisal

Frequently Asked Questions

What is a qualified appraisal for a charitable donation?

It is an appraisal prepared by a qualified appraiser under Treas. Reg. 1.170A-17, following USPAP, with required content and declarations. It must state fair market value as of the proper effective date and be timed to the donation and the return.

Who counts as a qualified appraiser under IRS rules?

An appraiser with verifiable education and experience valuing that property type. That is shown through a recognized designation such as MAI, SRA, or ASA, or through coursework plus two years of experience. They must regularly appraise for compensation and cannot be the donor, donee, or a party to the transaction.

When must the appraisal be dated for a real estate donation?

No earlier than 60 days before the contribution and no later than the return’s due date, including extensions. If the report is prepared after the gift, its effective date must be the contribution date, which usually means a retrospective appraisal.

When does Form 8283 require the full appraisal attached?

Real estate deductions over $5,000 require a completed Form 8283 Section B with the appraiser’s signature and the donee’s acknowledgment. Once the deduction exceeds $500,000, the entire qualified appraisal must be attached to the return itself.

Can the IRS reject a deduction even if the value is accurate?

Yes. Missing declarations, a wrong effective date, an unqualified appraiser, an incomplete Form 8283, or a value-based appraisal fee can each disallow the deduction. It does not matter whether the number was right. The rules are procedural, and they are enforced that way.

Appraisal Support for Charitable Gifts of Real Estate

PahRoo Appraisal & Consultancy prepares USPAP-compliant, tax-purpose appraisals for CPAs, attorneys, and property owners across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. Our team handles donated residential and commercial property, along with related estate planning valuations. Have a donation on the calendar? Contact our team or call 773-388-0003 before the deed records.


Tax appeal appraisal report and comparable sales evidence prepared for a Cook County Board of Review filing
Tax Appeal Appraisal: What the Cook County BOR Requires

A tax appeal appraisal is only as strong as the evidence rules it satisfies. The Cook County Board of Review has specific requirements, and a report that misses them loses weight before anyone reads the value conclusion. So attorneys and CPAs who order appraisals for appeals need to know exactly what the document must contain.

By the end of this article, you’ll know:

  • The specific evidence the Cook County Board of Review expects with an appraisal
  • Why the lien date, not the filing date, controls the valuation
  • The disclosure and documentation traps that sink otherwise solid appeals

What a Tax Appeal Appraisal Must Contain for the Board of Review

Start with the Board’s own rulebook. The official rules of the Cook County Board of Review spell out the baseline. An appraisal filed with an appeal must include an original photograph of the subject property’s front. It must also list the permanent index number of the subject and of every property used in the appraiser’s analysis. Miss either element, and analysts can discount the report without weighing its conclusions.

The report also has to stand on verifiable comparable evidence. Analysts pull the same public sales records the appraiser used, so every comparable needs a traceable sale that supports the adjustments. Because of that, we build our appraisal reports so each comparable can be checked against county records without a single follow-up question.

The Lien Date Controls Everything

Cook County values property as of January 1 of the assessment year, the lien date. An appraisal with a mid-summer effective date answers the wrong question, even if the analysis is otherwise careful. The report must establish market value as of that lien date, using sales that bracket it.

This trips up more appeals than any technical rule. A refinance appraisal from May, for example, was prepared for a different purpose and a different date. It can still matter, though, which leads to the disclosure problem below.

Disclosure Rules That Catch Filers Off Guard

The Board requires a completed Historical Summary Form for most non-residential appeals. Any transfers or prior appraisals must be disclosed on it. The Assessor’s rules go further. Filers must provide any appraisal or valuation report on the subject prepared within two years before the lien date. That includes reports done for financing or management purposes. So that May refinance appraisal is not optional background. It is discoverable evidence, and hiding it damages credibility.

Income-producing properties carry their own paper burden. Where the property is leased or available for lease, the Board asks for Schedule E filings for the three years before the lien date. Vacancy claims need current income and expense documentation. A tax appeal appraisal for these properties should anticipate that record set, not contradict it.

USPAP Compliance Is a Threshold, Not a Bonus

Appraisals in gross violation of USPAP standards will not be treated as credible evidence. Worse, the Assessor’s office can refer them to the IDFPR for investigation. That is a real professional consequence, and it explains why a cheap report is expensive. Standards published by The Appraisal Foundation govern how the analysis must be developed and reported, and appeal analysts know those standards well.

In practice, USPAP compliance shows up as documented adjustments, a supported highest and best use conclusion, and a clear reconciliation. Boilerplate gets noticed. So does an adjustment grid with no market support behind the numbers.

Build the Evidence File Before the Township Opens

Township windows open on a rolling schedule, and evidence deadlines follow quickly once a township closes. The Board accepts supplemental evidence only up to a set point before the hearing. So a report commissioned late arrives rushed, or after the door shuts. The better sequence starts early. Identify the properties worth appealing, then order the appraisal with the lien date and the Board’s rules written into the engagement. File with a complete package. Appeals resolved on the written file get the same review as those with hearings, which means the written file has to carry the whole case.

Filing at the Board of Review this season?

PahRoo prepares lien-date appraisals built to the Board’s evidence rules, with comparables an analyst can verify line by line.

Get Appeal-Ready Evidence

Frequently Asked Questions

What evidence does the Cook County Board of Review accept?

The Board accepts appraisals, comparable sales data, photographs, and closing documents from a recent purchase. Documentation of factual errors, such as incorrect square footage, also counts. Appraisals must include a front photo of the subject and the PIN of every property in the analysis.

What should a tax appeal appraisal include?

It should establish market value as of the January 1 lien date and comply with USPAP. It also needs verifiable comparable sales with permanent index numbers and a front photograph of the subject. Adjustments need market support an analyst can trace.

Can I appeal my Cook County property taxes myself?

Individual owners can represent themselves on residential appeals. Properties held by corporations, LLCs, or other entities must be represented by an attorney under the Board’s rules. Either way, the evidence requirements are the same.

Do I have to disclose a prior appraisal in my appeal?

Yes. Transfers and prior appraisals must be disclosed on the Historical Summary Form. Reports prepared within two years before the lien date must also be provided, even ones done for financing purposes.

What does a Board of Review appeal cost?

Filing at the Board of Review is free. The real costs are professional ones: an independent appraisal if your case needs valuation evidence, and attorney fees where representation is required or advisable.

Appraisal Support for Cook County Appeal Work

PahRoo Appraisal & Consultancy prepares independent, USPAP-compliant valuations for property tax attorneys, CPAs, and owners across Cook County. If the 2026 cycle has clients asking questions, our guide to the 2026 Cook County reassessment covers when a new assessment deserves a formal challenge. Our property tax appeal FAQs answer the questions clients raise most.

Direct capitalization calculation in a commercial appraisal
The Income Approach: How Appraisers Value Income-Producing Property

When a lender questions a commercial value, the question almost always lands on the same section. The income approach appraisal analysis is where the reasoning is most exposed, because every assumption in it has a dollar attached.

By the end of this article, you’ll know:

  • How the income approach converts income into value
  • The difference between direct capitalization and discounted cash flow
  • The five assumptions worth checking before you rely on the number

What the Income Approach Appraisal Method Does

The income approach converts a property’s expected future income into a present value. It rests on a simple idea. Buyers of income-producing real estate are buying a stream of money over time, so the price they pay reflects how much that stream is worth today.

This is recognized methodology rather than one firm’s house style. The Appraisal Institute standards of professional practice set requirements for the development and reporting of an appraisal, and identify the organization’s Body of Knowledge as an authoritative source of recognized methods and techniques. The income approach sits squarely inside that body of work.

Two methods do the converting. Direct capitalization handles one year. Discounted cash flow handles many.

Direct Capitalization: One Year, One Rate

Direct capitalization takes a single year of stabilized net operating income and divides it by a market capitalization rate. A property producing $560,000 of stabilized NOI, capitalized at 7 percent, indicates a value of $8,000,000.

The method assumes the income is representative of what the property will produce going forward. That assumption holds well when a building is fully leased, the leases run at market rates, and no large rollover is coming. It holds poorly when half the leases expire next year at rents far above or below market.

Direct capitalization is faster, easier to support with sales evidence, and easier for a reviewer to test. When it fits, appraisers use it.

Discounted Cash Flow: Many Years, Two Rates

Discounted cash flow projects the property’s income year by year across a holding period, usually five or ten years, then discounts each year back to present value. At the end of the period, the analysis adds a reversion, which is the projected sale price at the end of the holding period, discounted back as well.

The reversion is estimated using a terminal capitalization rate applied to the income in the year after the holding period ends. Two rates therefore appear in the analysis: the discount rate, which reflects the return an investor requires over the whole period, and the terminal rate, which reflects what a future buyer would pay.

Every projected year carries assumptions about rent growth, expense growth, renewal probability, downtime between tenants, and leasing costs. That is the strength and the weakness of the method. It can model a complicated property accurately, and it can also produce almost any answer if the assumptions drift.

When Appraisers Choose One Over the Other

The property picks the method. Direct capitalization suits stabilized property with steady income and market leases. Discounted cash flow suits property where the income pattern changes in a way one year cannot represent.

That includes a building in lease-up, a property with heavy lease rollover in the near term, leases with step rents or free rent periods, and any asset where major capital spending is scheduled. It also includes properties with a single tenant whose lease expires inside the projection period, since the value swing between renewal and vacancy is large.

Appraisers often develop both, then reconcile. When the two methods land far apart, that gap itself is informative and the report should explain it.

Five Assumptions Worth Checking Before You Rely on the Number

If you are reviewing an income approach, test these five inputs against the market rather than against the appraiser’s confidence:

  • Market rent. Is it supported by rent comparables, or borrowed from the subject’s own leases?
  • Vacancy and collection loss. Does it reflect the submarket, or does it assume the building stays full forever?
  • Operating expenses. Are they reconstructed to market levels, including a management fee and reserves?
  • The capitalization or discount rate. Is it derived from confirmed comparable sales, or lifted from a national survey?
  • Growth and rollover assumptions in a discounted cash flow. Are rent growth and renewal probability reasonable given the actual submarket?

Any one of those can move a value by hundreds of thousands of dollars. A good report lets you check all five without calling the appraiser. If it does not, calling the appraiser is the right next step.

Need an Income Analysis That Survives Review?

PahRoo builds income approaches lenders and reviewers can test, with every rate, rent, and expense assumption tied to market evidence.

Start a Commercial Appraisal

Frequently Asked Questions

What is the income approach in appraisal?

It is the method that converts a property’s expected income into a present value. Appraisers use it for income-producing property because buyers of such property are purchasing a stream of income rather than the building alone.

What is direct capitalization?

Direct capitalization divides one year of stabilized net operating income by a market capitalization rate to indicate value. It suits stabilized properties with steady income and leases at market rates, and it is easier for a reviewer to test.

What is the difference between direct capitalization and DCF?

Direct capitalization uses a single year of income and one rate. Discounted cash flow projects income across a holding period, discounts each year to present value, and adds a discounted reversion using a terminal capitalization rate.

When is discounted cash flow used?

When one year of income cannot represent the property, such as a building in lease-up, a property with heavy near-term lease rollover, leases with step rents or free rent, or an asset with scheduled major capital spending.

What is a discount rate in a commercial appraisal?

It is the rate of return an investor would require over the entire holding period, used to convert projected future cash flows and the reversion into present value. It differs from the capitalization rate, which applies to a single year of income.

Ask How the Income Approach Was Built, Not Just What It Concluded

PahRoo Appraisal & Consultancy develops direct capitalization and discounted cash flow analyses for commercial property in Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples, with assumptions documented so a reviewer can follow them. See our commercial appraisal services, browse the wider range of our real estate appraisal services, or call 773-388-0003.


Partially vacant retail property where vacancy reduces net operating income
Net Operating Income in Commercial Real Estate

Net operating income is the number a commercial appraisal is built on. Get it wrong by five percent and the value moves by five percent. Owners send us their profit and loss statement expecting it to be used as-is, and it almost never is.

By the end of this article, you’ll know:

  • How to calculate NOI step by step
  • Which expenses belong in NOI and which are excluded
  • Why an appraiser reconstructs the owner’s numbers before applying a cap rate

What Net Operating Income Actually Measures

Net operating income is the annual income a property produces after operating expenses, but before debt service, income taxes, depreciation, and capital expenditures. It measures the earning power of the real estate itself, separate from how any particular owner financed or structured it.

That separation is the point. Two buyers can pay the same price for the same building with completely different loans. The property still throws off the same income. NOI is what makes properties comparable to one another.

How to Calculate NOI, Step by Step

Start at the top of the rent roll and work down. Here is a simple example for a small multi-tenant building:

  • Potential gross income: $1,000,000, the rent if every space were leased at market
  • Less vacancy and collection loss at 7 percent: $70,000
  • Effective gross income: $930,000
  • Less operating expenses: $340,000
  • Less replacement reserves: $30,000
  • Net operating income: $560,000

Apply a 7 percent capitalization rate to that $560,000 and the indicated value is $8,000,000. Move NOI by $28,000, which is five percent, and the value moves by $400,000. Small errors in the income line become large errors in value.

What Belongs in NOI and What Does Not

Operating expenses are the recurring costs of running the property. Include property taxes, insurance, utilities not reimbursed by tenants, repairs and maintenance, management fees, janitorial and landscaping, and reserves for replacement of short-lived items such as roofs and parking lots.

Leave out mortgage principal and interest, income taxes, depreciation, capital improvements, leasing commissions and tenant improvement allowances, and any expense personal to the owner. A vehicle payment or a family salary that would disappear the day the property sold does not belong in a market-based analysis.

Owners often push back on the management fee. Even an owner who self-manages should show a market management expense, because a buyer would either pay a manager or value their own time. Leaving it out inflates NOI and produces a value the market will not support.

Why Appraisers Rebuild the Owner’s Numbers

An appraisal reflects what a typical buyer would expect, not what one owner happened to experience last year. So the appraiser reconstructs the statement using market rent, market vacancy, and market expense levels, then compares that reconstruction against the property’s actual history and against expense comparables.

Non-market conditions get adjusted too. Federal appraisal guidance addresses this directly. The Interagency Appraisal and Evaluation Guidelines require appraisers to analyze and report appropriate deductions and discounts for partially leased buildings and for leases with terms that do not reflect current market conditions. A building leased to the owner’s brother at half market rent will be analyzed on both the contract and the market basis, and the report will explain which one drives the value.

NOI Is Not Cash Flow, and It Is Not Taxable Income

Three numbers get confused constantly, and they are not interchangeable. NOI stops before debt service. Cash flow before taxes subtracts the mortgage payment from NOI. Taxable income follows a different set of rules again, with depreciation and interest treated the way the tax code says rather than the way an appraiser treats them.

Lenders care about the gap between NOI and debt service, because that gap is the debt service coverage ratio. Appraisers care about NOI because it feeds the income approach. Your CPA cares about the tax figures, and that is properly their work rather than ours. If your accountant and your appraiser show different numbers for the same building, both can be correct, because they are answering different questions.

So before you accept a value conclusion, look at the income reconstruction. If the vacancy assumption, the expense ratio, or the management fee looks off compared to your market, that is the conversation to have with the appraiser.

Your Value Starts With Your Income Line

PahRoo reconstructs income and expenses against real market evidence, then shows the reconstruction so you can see exactly where the value came from.

Request a Commercial Appraisal

Frequently Asked Questions

What expenses are included in NOI?

Recurring costs of operating the property, including property taxes, insurance, unreimbursed utilities, repairs and maintenance, management fees, janitorial and landscaping, and reserves for replacement of short-lived building components.

Does NOI include the mortgage?

No. Net operating income is calculated before debt service, so mortgage principal and interest are excluded. This lets properties be compared on the earning power of the real estate rather than on how a particular owner financed it.

How is NOI different from cash flow?

Cash flow before taxes equals NOI minus debt service. NOI stops before the mortgage payment. Taxable income differs again, because depreciation, interest, and capital costs are treated under tax rules rather than appraisal practice.

Why does an appraiser change my operating statement?

Because market value reflects what a typical buyer would expect, not one owner’s actual experience. The appraiser applies market rent, market vacancy, market expenses, and a market management fee, then compares that reconstruction to the property’s history.

Should replacement reserves be deducted from NOI?

In most commercial appraisal practice, yes. Reserves cover the periodic replacement of short-lived items such as roofs, HVAC units, and parking surfaces. The treatment should be consistent with how reserves were handled in the sales used to derive the cap rate.

Check the Income Reconstruction Before You Rely on the Value

PahRoo Appraisal & Consultancy analyzes rent rolls, leases, and operating statements for income-producing property across Chicago and Cook County, Dallas-Fort Worth, Philadelphia, Phoenix, and Naples. We show the reconstruction rather than hiding it in an appendix. Review our commercial appraisal services, request a preliminary consultation, or call 773-388-0003 to talk through a property.


NEWSLETTER

Knowing a property's true value is key
to making informed real estate decisions

Visit us

7383 Lincoln Ave Suite,
#100 Lincolnwood, IL, 60712