
PahRoo Appraisal & Consultancy prepares residential appraisal reports for homeowners, heirs, attorneys, lenders, and agents who need a value they can stand behind. We appraise single-family homes, condos, townhomes, and two-to-four unit buildings. Every report follows USPAP and is written for whoever will actually read it, whether that’s a judge, a tax board, or a loan servicer. Founded by Michael Hobbs, MAI, SRA, PahRoo has been appraising homes for more than 25 years.
Residential Appraisal Services We Offer
A fair value of the home as of the date your case needs, including past dates.
One value, so the court, the executor, and the heirs all work from the same number.
A retrospective value for the estate and the heirs’ tax basis.
A documented value before a home goes into a trust or to family.
Sales evidence for your appeal, since a mass assessment can miss what makes your home different.
A supportable value for the real estate listed in the case, so the number holds up.
A report built for cross-examination, plus review of the other side’s appraisal.
Before-and-after values when a project takes all or part of a property.
A verified value before the listing goes live or the offer goes in.
An independent value for a new loan, or a check on your equity before you apply.
Proof of value for your servicer when you ask to cancel PMI.
An as-is value for lenders, servicers, or owners on a home headed into foreclosure.
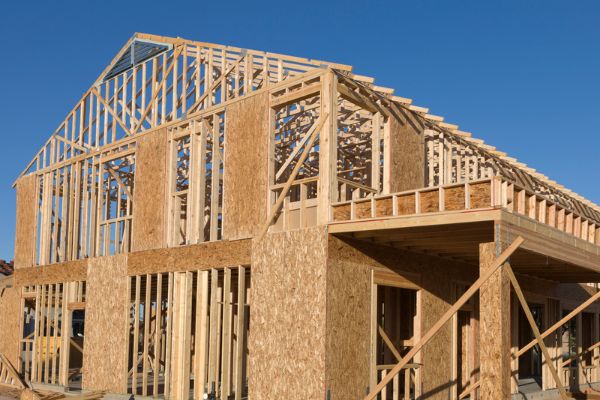
A value from plans and specs, so the loan can be sized before the house is built.
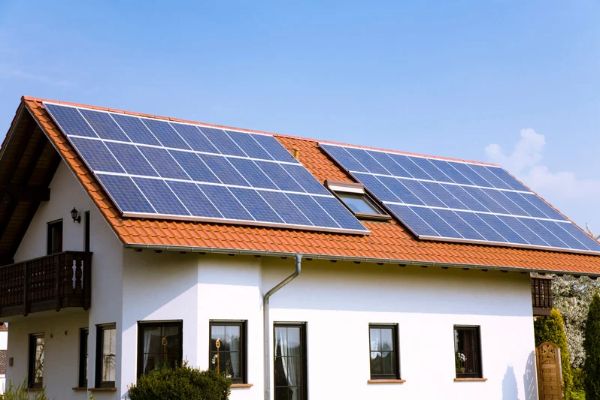
Credit for solar and efficient systems, since buyers often pay more for them.
An anticipated sales price on the form your company’s relocation program uses.
A qualified appraisal for IRS Form 8283 when the gift is worth more than $5,000.
A lot of this work comes to us through attorneys, bankers, brokers, and CPAs, so we write with each of them in mind. See how we work with each of them →
Homes We Appraise
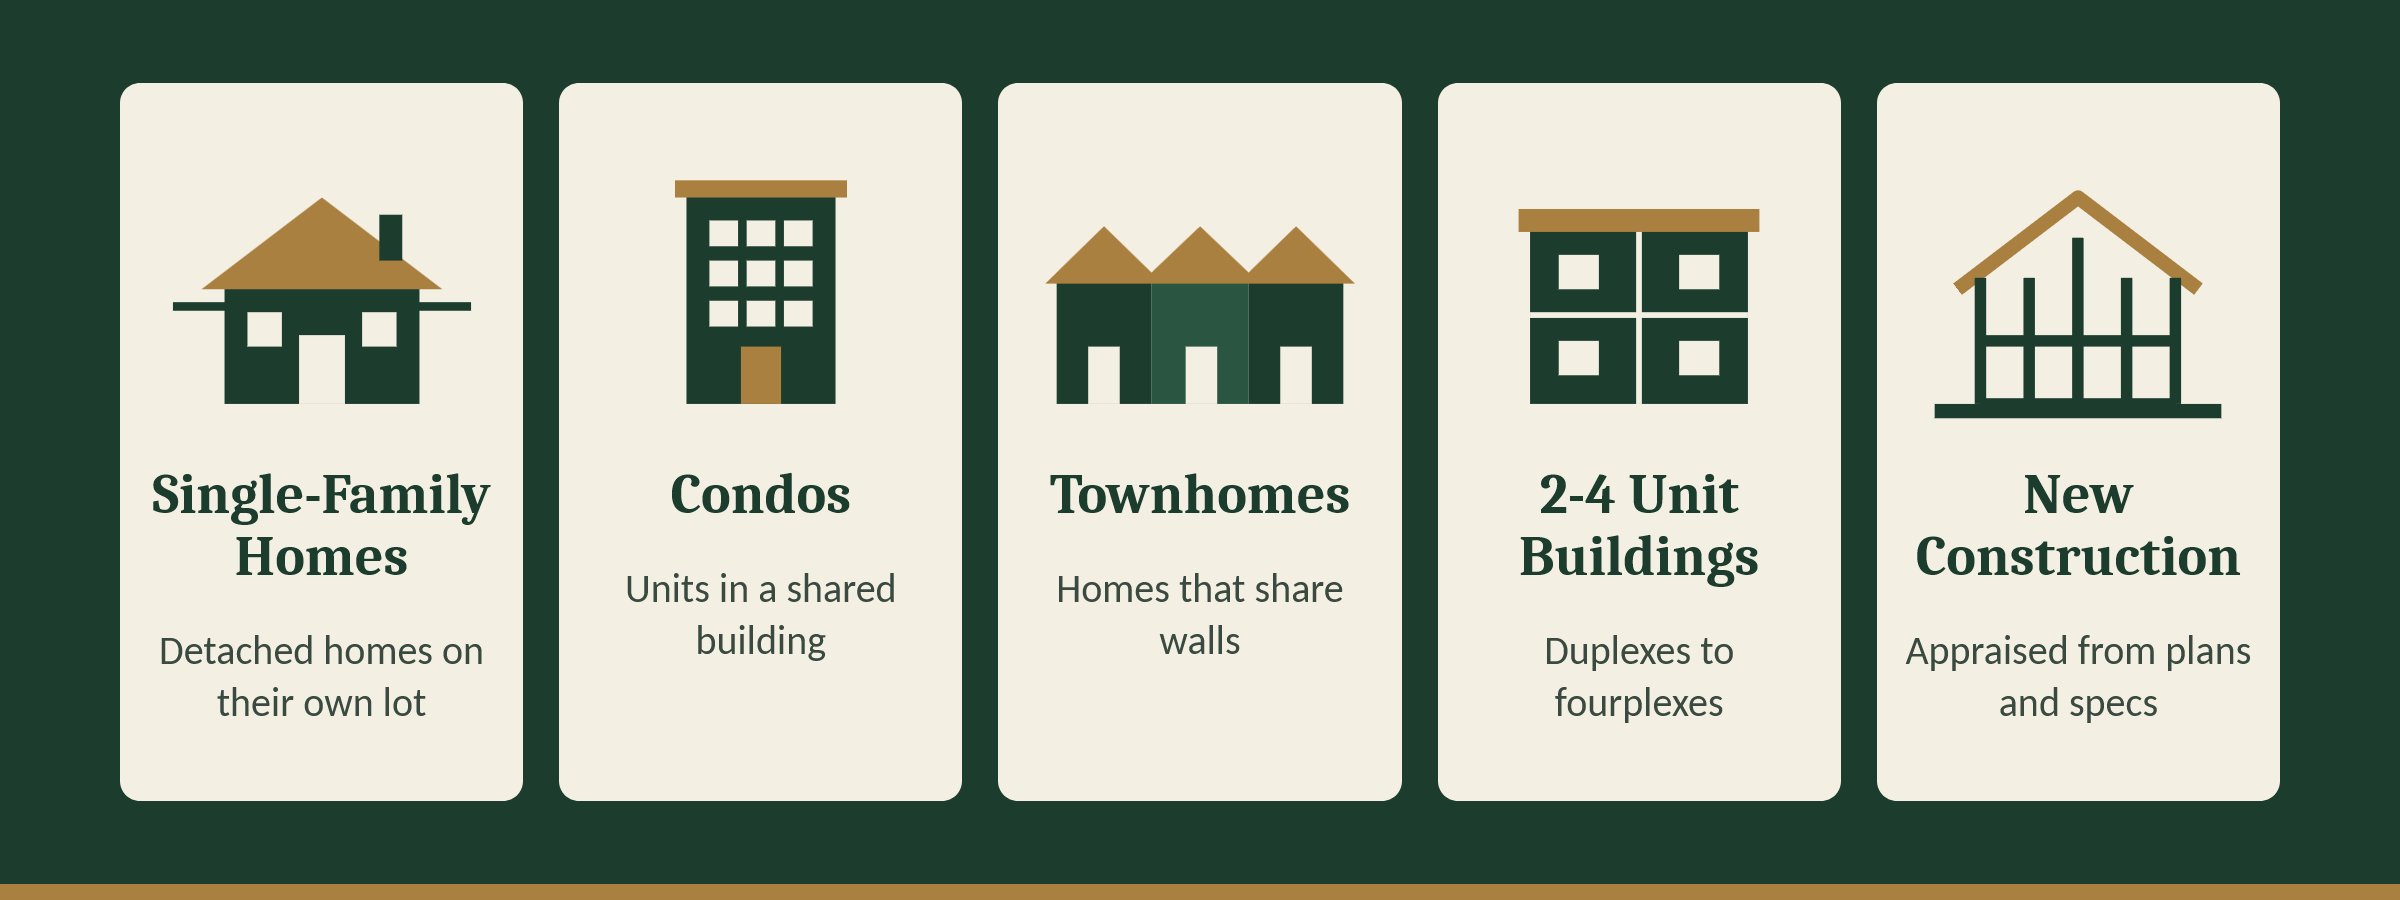
Most of our residential work is single-family homes, condos, and townhomes. We also appraise two-to-four unit buildings, one-of-a-kind and high-end homes, and new construction. Buildings with five or more units, on the other hand, are valued as commercial property.
Apartment buildings with five or more units, retail, office, industrial, mixed-use property, and land.
Full, exterior, and desktop reports each fit a different job.
Divorce Appraisal
The house is often the biggest asset in a divorce, so its value has to be tied to a specific date. Depending on the case, that could be the separation date, the filing date, or a date years back. Either way, we document the market as of that date rather than the day of the inspection. Our article on appraisals in divorce proceedings explains the process, and if one spouse is keeping the house, the marital home buyout calculator helps you run the numbers.
Probate, Date-of-Death, and Estate Planning Appraisals
An estate needs a value as of the date of death, often months or years before anyone calls an appraiser. That date also matters for taxes, because an heir’s basis in inherited property is generally its fair market value on the date of death, as the IRS explains for gifts and inheritances. For that reason, we use sales that bracket the date rather than today’s listings. Probate courts, executors dividing property among heirs, and families moving a home into a trust all rely on this kind of residential appraisal.
Property Tax Appeal Appraisal
Assessors value whole neighborhoods at once, so a mass model can miss what sets your home apart, like its condition or a busy street. An appraisal, by contrast, gives the board sales evidence for your specific property. The value also has to match the assessment date your county uses, which usually isn’t today. For more on dates, read about retrospective versus current market value.
Bankruptcy Appraisal
In a personal bankruptcy, real estate goes on Schedule A/B at its current value as of the filing date. That number then carries into the exemptions claimed on Schedule C, so it often gets a close look from the trustee. Our appraisal sets the value as of the date counsel needs and shows the sales behind it. That way, if anyone questions the number, the support is already in the report.
Litigation Support and Expert Witness Appraisal
When a home’s value is part of a lawsuit, the report has to hold up under cross-examination. First, we review the other side’s appraisal and put the problems in writing. Then we prepare our own reports with testimony in mind, and our appraisers can testify at deposition or trial. Let us know at the start, since that shapes how the report is written.
Eminent Domain and Right-of-Way Appraisal
When a government agency takes all or part of a property for a road, pipeline, or other project, the owner is owed just compensation. In a partial taking, that often comes down to the value before the taking compared with the value of what remains. For example, a strip off the front yard can change access, parking, or how the house sits on the lot, so our report measures those effects with sales evidence.
Pre-Listing and Pre-Purchase Appraisals
A pre-listing appraisal gives a seller a documented value before the house goes on the market. It helps most when the home doesn’t match its street, such as a big renovation among original houses. Buyers order a pre-purchase appraisal for the same reason, before they commit to a price. Online estimates can’t see inside the house, which is why our piece on a Zestimate versus an appraisal is worth a few minutes.
Refinance Appraisal
Lenders order refinance appraisals from us when they need an independent value for a new loan. Homeowners also call before they apply to see where their equity stands. Keep in mind, though, that a lender usually orders its own appraisal for the loan itself. So if you hope to use our report, ask your lender first. And if a lender offers to skip the appraisal altogether, read about the risks of an appraisal waiver before you agree.
PMI Removal Appraisal
Federal law lets you ask your servicer to cancel private mortgage insurance once your loan balance reaches 80 percent of the home’s original value. To approve the request, a servicer can ask for evidence, such as an appraisal, that the value hasn’t dropped. Some servicers also allow earlier removal when the home has gained value, under their own rules. Because requirements vary, call your servicer first and ask what they’ll accept. FHA and VA loans also follow different rules. The CFPB’s guide to removing PMI lays out the details.
Foreclosure Appraisal
Lenders and servicers need a current value on a home headed into foreclosure, usually as is, with whatever repairs it needs. Owners also order one at times, so they know where they stand before they talk with the lender. Vacant and distressed homes take extra care, because condition drives the value more than usual. Our article on as-is appraisals before foreclosure goes deeper.
New Construction Appraisal
A new home is often appraised before it exists, from plans and specifications. In that case, the report states exactly what it relied on, such as the plans, the cost breakdown, and the finish list. Construction lenders use the value to size the loan, while buyers use it to check the contract price. Afterward, once the house is finished, a completion inspection can confirm it was built as planned.
Green and Energy-Efficient Home Appraisal
Solar panels, high-efficiency systems, and green certifications don’t fit neatly on a standard appraisal form, so they can get missed. So we document these features and look for sales that show what local buyers actually pay for them. When it helps, we also attach the Appraisal Institute’s Residential Green and Energy Efficient Addendum. Bring any energy ratings, utility bills, or solar contracts you have, since owned and leased panels can be treated differently.
Relocation and ERC Appraisal
Corporate relocation programs don’t use a mortgage appraisal. Instead, they use the Worldwide ERC Summary Appraisal Report, which forecasts an anticipated sales price over a reasonable marketing time. We complete that form for relocation clients, so the program gets the format it asked for.
Charitable Donation Appraisal
When you give real estate to a charity and claim more than $5,000, the IRS generally requires a qualified appraisal by a qualified appraiser. The appraisal is then summarized in Section B of Form 8283, and the appraiser signs that section, too. Timing rules apply as well, so bring us in before you file. Our article on what makes an appraisal qualified for a donation covers the details.
How to Order a Residential Appraisal From PahRoo
Use the quote form with the address, what the appraisal is for, and any deadline.
Then someone from our team confirms the scope and quotes the fee.
Once you approve, we schedule the visit and work to your deadline.
Need a Residential Appraisal?
Tell us the address, what the appraisal is for, and when you need it. After that, we’ll come back with the scope and the fee.
Frequently Asked Questions
About the appraisal
What is a residential appraisal?
It’s an independent opinion of a home’s market value, prepared by a licensed or certified appraiser under USPAP. Unlike an online estimate, the appraiser looks at the property and supports the value with comparable sales.
Can you appraise a home as of a past date?
Yes. A retrospective appraisal sets the value as of an earlier date, such as a separation date or an assessment date. We use sales and market conditions from that time rather than today’s listings.
Do I need an appraisal if I inherited a home?
Often, yes. An heir’s tax basis is generally the home’s fair market value on the date of death, so a date-of-death appraisal documents that number for when the home is sold later. Your CPA or estate attorney can confirm what your situation needs.
How is an appraisal different from an agent’s price opinion?
An agent’s market analysis is a pricing opinion meant to help sell a home. An appraisal, on the other hand, is an independent opinion of value from a licensed or certified appraiser under USPAP. That’s why courts, tax boards, and lenders rely on it.
Working with PahRoo
Does an appraisal help with a property tax appeal?
It can. The appraisal gives the board sales evidence for your home as of the assessment date your county uses, not a general estimate. It doesn’t guarantee a lower assessment, but it gives your appeal a documented value to stand on. Since filing windows are short and vary by county, reach out as soon as your notice arrives.
Can one appraiser work for both spouses in a divorce?
Yes, if both sides agree. In that case, we prepare a neutral report that both spouses and their attorneys rely on, which usually costs less than two competing appraisals.
Can I use your appraisal with my mortgage lender?
Sometimes. Lenders usually order their own appraisal for a loan, and for PMI removal your servicer sets the rules. So ask your lender or servicer before you order, and tell us who will rely on the report.
Can your appraiser testify?
Yes. Our appraisers can testify at deposition or trial, and we can also review the other side’s appraisal. Let us know at the start if testimony is likely.
Where does PahRoo appraise homes?
We work in and around Chicago, Dallas, Philadelphia, Phoenix, and Naples. Call (773) 388-0003 or email appraisal@pahroo.com, and we’ll confirm we cover your address.
Who We Work With
Much of our residential work comes through the professionals who guide these decisions, so we write each report with their review, filing, or courtroom in mind.
Attorneys
Family law, estate, bankruptcy, property tax, eminent domain, and litigation, including testimony when the case needs it. See why a mid-case appraisal beats an early estimate.
Bankers
Refinance, PMI removal, and new construction, so underwriting has an independent value. See how appraisers choose comparable sales.
Brokers & Realtors
Pre-listing and pre-purchase values backed by verified sales. See how an appraisal sets a listing price.
CPAs & Accountants
Donation values for Form 8283, plus gift and trust values. See documented values in estate planning.
PahRoo Appraisal & Consultancy
PahRoo is an independent appraisal firm founded by Michael Hobbs, MAI, SRA. We appraise homes in and around Chicago, Dallas, Philadelphia, Phoenix, and Naples, and you’ll find local details on our areas we serve page. You can reach us at (773) 388-0003 or appraisal@pahroo.com. If you’re new to this, our home appraisal process guide explains what happens from order to report, while our appraisal FAQ covers the basics.